EACC

Trump Administration Secures an Additional $100 Billion U.S. Semiconductor Manufacturing Investment for a Total of $265 Billion from TSMC

As a result of the historic deal related to U.S. and Taiwan Trade and Investment announced in January 2026, TSMC has just announced an incremental $100 billion investment for a total of $265 billion in the U.S. This investment will result in four additional advanced semiconductor manufacturing facilities, bringing the total to 12 leading-edge semiconductor and packaging facilities.
Today, the White House and the Department of Commerce announced an incremental $100 billion investment by TSMC for advanced semiconductor manufacturing and packaging facilities in Arizona. With the additional facilities, TSMC’s $265 billion investment will provide a total of 12 facilities in the United States.
This follows the March 2025 announcement with President Trump and Secretary Lutnick, in which TSMC agreed to expand its original $65 billion investment commitment by an additional $100 billion. The total planned investment in the United States is now a record $265 billion.
The announcement comes just months after the signing of the historic deal on trade and investment between the U.S. and Taiwan, under the auspices of the American Institute in Taiwan and the Taipei Economic and Cultural Representative Office in the United States, and highlights the Trump Administration’s commitment to strengthening domestic manufacturing and U.S. technological leadership through strategic partnerships and investment.
This additional $100 billion investment marks a significant expansion of TSMC’s commitment to build multiple fabrication plants and advanced packaging facilities in the United States. TSMC’s investments in the United States are expected to create significant construction and high-tech jobs while driving billions of indirect economic output as TSMC executes its investment plan.
“President Trump’s leadership is driving companies to invest in American manufacturing. TSMC’s announcement of an additional $100 billion investment following our historic deal on trade and investment with Taiwan will create tens of thousands of American jobs and bring advanced semiconductor manufacturing back to America,” said Commerce Secretary Howard Lutnick.
“We appreciate the strong collaboration and support of the Trump Administration, Secretary Lutnick and our leading U.S. customers, and have announced an additional $100 billion investment in the U.S., bringing the total planned investment to $265 billion and adding to the largest foreign direct investment in U.S. history,” said Dr. C.C. Wei, TSMC Chairman and CEO. “This is to support the strong multi-year demand from our leading U.S. customers, and we believe this investment will further foster the development of the U.S. semiconductor ecosystem, strengthen the supply chain, and support significant job creation in the United States. We are very excited about the tremendous opportunities that lie ahead of us.”
Additionally, the trade and investment deal is expected to catalyze incremental Taiwanese investment in the United States. The deal provides $250 billion in direct investments by Taiwanese semiconductor and other enterprises and $250 billion of additional Taiwan investment to bring other critical elements of the semiconductor supply chain to the U.S.
 
Compliments of the U.S. Department of CommerceThe post Trump Administration Secures an Additional $100 Billion U.S. Semiconductor Manufacturing Investment for a Total of $265 Billion from TSMC first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

European Commission Outlines Measures to Strengthen Europe’s Banking Sector and Support Growth

The European Commission today adopted a Communication on the competitiveness of the EU banking sector, setting out measures to strengthen the Single Market for banking. 

President of the European Commission Ursula von der Leyen said: “Getting capital flowing is how we will get Europe growing. Our Savings and Investments Union needs a strong, competitive banking sector at its heart. And today’s Communication takes a clear step in this direction, recalibrating our approach to risk, and enabling growth and innovation while maintaining financial stability.” 

The objective is to build a more integrated, efficient, and competitive banking sector that can strengthen Europe’s economy by financing growth, innovation, and strategic priorities, underpinned by a better-balanced regulatory framework, creating the conditions for banks to take prudent risks while safeguarding the sector’s resilience, delivering better services to households and businesses, all while preserving financial stability and fostering sustainable growth. 

This Communication is a key pillar of the Commission’s Savings and Investments Union (SIU) strategy: having a banking sector with the strength and scale to finance growth and strategic priorities, such as innovation, the clean transition, and defence, while delivering high-quality financial services to households and businesses. 

Following a public consultation and exchanges with Member States, stakeholders, and supervisory authorities, the Commission has identified three main challenges that limit the banking sector’s ability to support the EU economy effectively. 

First, the sector remains too fragmented along national lines. This prevents EU banks from scaling up and competing globally in key market segments and finding efficiencies across borders. Second, the way international banking standards, known as Basel III standards, are transposed into the EU framework does not always reflect the specific features of the EU banking landscape. The framework needs to work better for both large and small banks. Third, some parts of the EU regulatory framework, including the interaction between microprudential, macroprudential and resolution rules, as well as reporting requirements, are too complex and burdensome and should be simplified. Addressing these three challenges is essential to building a banking sector that is not only resilient and competitive, but also able to support the EU economy. 

Boosting competitiveness calls for a cultural shift in banking towards responsible, measured risk-taking. Simplifying the regulatory framework, integrating the Single Market and completing the Banking Union would help EU citizens and businesses access better products and services at more competitive prices.  

Key measures 

The Communication identifies key measures that are built around three objectives. 

First: removing barriers to cross-border banking activity and fostering market integration. Today’s Communication sets out the path towards reducing prudential and non-prudential barriers to cross-border activity so that EU banks can reach the scale required to compete globally. This would include the following measures: 

Allowing cross-border banking groups to use capital and liquidity more efficiently across the EU: this would allow groups to redirect excess funds to where they can be more productive without hampering their capacity to finance local economies, and without prejudice to financial stability across the Single Market and in each Member State. 

Strengthening common safeguards: the Commission will seek to increase trust in the financial system and among supervisors by proposing a simpler and more effective common deposit protection mechanism in the Banking Union. This would replace the 2015 European Deposit Insurance Scheme proposal and build on existing central and national safety nets, which are now fully funded.  

Closer monitoring of EU anti-money laundering and consumer protection frameworks and their national implementation: this would make it easier for banks to offer services across borders.

Second: implementing international standards while taking into account EU specificities and proportionality. The EU remains committed to applying international standards while better reflecting the specificities of the EU banking sector. To preserve the international level playing field and support EU banks to compete globally, the measures set out in the Communication include: 

Re-assessing how the EU implements certain international standards, which may be in some cases limiting the lending capacity of EU banks.

Possible revisions of certain prudential and corporate governance rules to better reflect EU banks’ specificities in relation to banks’ size, business models, and activities.

Finally: the regulatory framework for banks should be simplified as part of the Commission’s wider objective of reducing administrative burden. Trust in the banking system depends on strong safeguards, but unnecessary complexity should be reduced and requirements made more predictable and transparent for banks and authorities alike. In particular, the Communication highlights:

Simplifying the capital stack and further harmonising banks’ macroprudential buffers.

Standardising and streamlining resolution capital requirements and processes.

Adjusting the criteria and thresholds for “small and non-complex institutions” and adapting their requirements.

Next steps

The Commission has sought stakeholder feedback, and respondents are welcome to submit views or comments in the months to come. The Commission will propose in the first quarter of 2027 a package of measures to amend the banking regulatory framework and deliver on this Communication, in line with the objectives of the One Europe, One Market roadmap. In parallel, the Communication calls on Member States, supervisory authorities, and the banking industry to continue their own efforts to improve bank competitiveness.

Background

The SIU strategy aims to improve how the EU financial system channels savings into productive investment. It envisages an efficient and integrated banking sector based on a single rulebook and a completed Banking Union. The strategy is aligned with the EU’s Competitiveness Compass, developed in response to the recommendations of the Letta and Draghi reports; the Single Market Strategy; and the One Europe, One Market roadmap. 

 
Compliments of the European CommissionThe post European Commission Outlines Measures to Strengthen Europe’s Banking Sector and Support Growth first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

European Commission Launches EU-Ukraine Drone Alliance to Boost Drone and Counter-drone Technology

The European Commission officially launched the EU-Ukraine Drone Alliance during the third EU-Ukraine Defense Industry Forum in Kyiv. The Alliance will help the EU and Ukraine work more closely on developing and using drones and systems to stop hostile drones. It is part of wider EU efforts to strengthen Europe’s defense in this fast-changing area.
The Alliance brings together companies, start-ups, researchers, armed forces and other users from EU countries and Ukraine. Its main goal is to help improve the security of both the EU and Ukraine by supporting a strong drone industry, encouraging the development of new drone and counter-drone technologies, and helping build Europe’s overall capacity in this area.
The Alliance begins to implement the Drone Deal, announced by President Ursula von der Leyen in Kyiv on Wednesday 15 July. Its objective is to build joint ventures between Ukrainian and European companies, and to accelerate the development and production of next-generation drones and counter-drone systems. By doing so, it will help ensure that Ukraine has the capabilities it needs today, while strengthening Europe’s defense readiness for the future.
The Commission is now preparing the first meeting of the 18 founding members scheduled to take place in Brussels in September.
These founding members, selected following an open call for expression of interest, include ORQA d.o.o., Indra Group, Fincantieri, WB Electronics/WB Group, Destinus, Delair, RSI Europe, TERMA A/S, Quantum Systems from EU Member States.
Selected Ukrainian members are LLC Skyfall Industries, LLC, Greentech Harvest, LLC, Tencore, LLC, Deviro, LLC, Vyriy Industry, Scientific production Company ‘ATHLON AVIA’ LLC, TEHAVTOFART PIVDEN” (TAF Industries), UFORCE and F-Drones.
Background
The EU-Ukraine Drone Alliance was first announced by President von der Leyen in her State of the European Union speech in 2025 to foster an innovative defence drone-industrial ecosystem. It is a key deliverable of the Joint Communication Preserving Peace – Defence Readiness Roadmap 2030, published in October 2025, and of the Communication on the Action Plan on Drone and Counter Drone Security of February 2026.
The announcement follows the selection of the 18 founding members, including both EU and Ukrainian companies, based on a call for expressions of interest. The application deadline was 25 May 2026.
 
Compliments to the European CommissionThe post European Commission Launches EU-Ukraine Drone Alliance to Boost Drone and Counter-drone Technology first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

Read More
EACC

IMF | The Oil Market Absorbed the War Shock, but Buffers Are Running Low

IMF Blog post | Less demand, more production, and inventory drawdowns prevented a larger price spike. A quick supply recovery is essential to avoid further damage to the global economy
 
The largest disruption to the global oil market in decades should have sent prices soaring. But after spiking at the start of the war in the Middle East, crude prices soon settled in a range of $90 to $100 per barrel, much lower than many had feared. Why didn’t prices climb higher? The answer is that a combination of factors helped cushion the initial blow. But much of that room has now been used up.
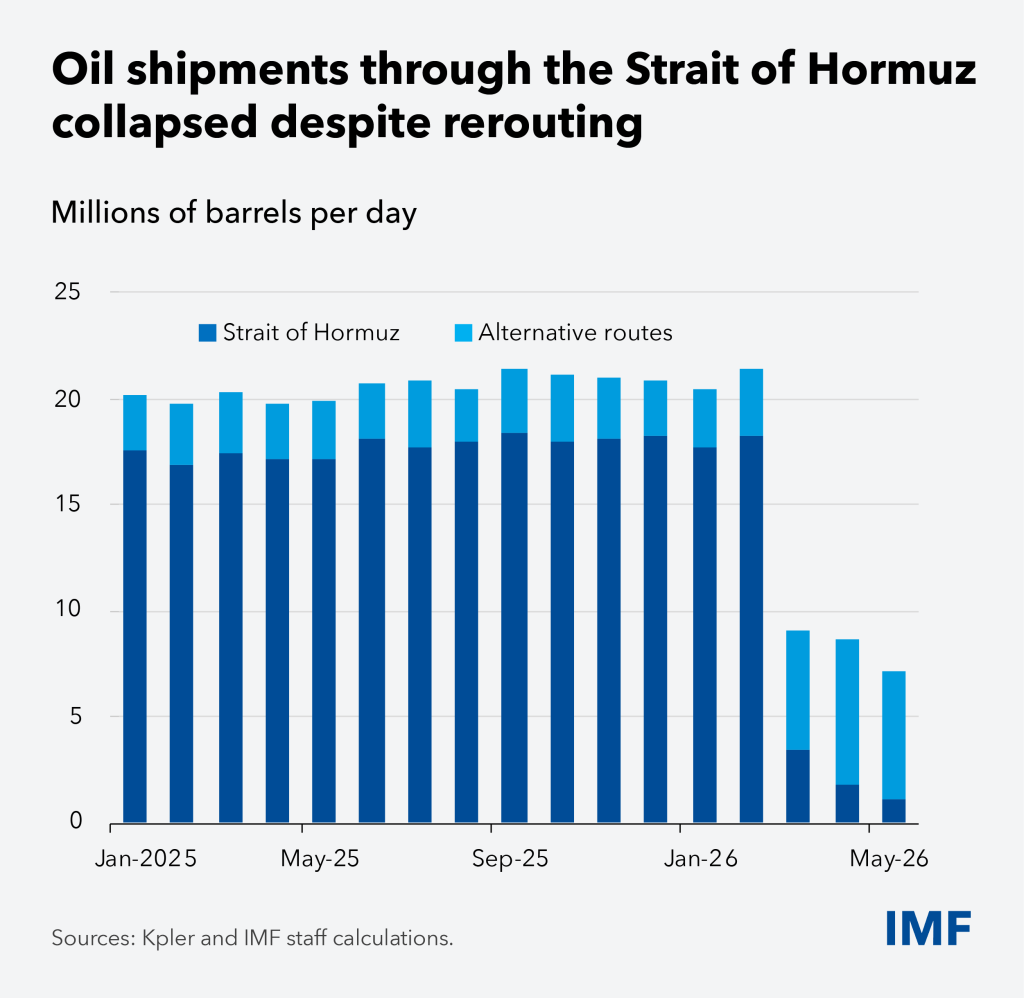
There are plenty of reasons why oil should have become cripplingly expensive. The war effectively closed the Strait of Hormuz, cutting off some 20 million barrels a day of crude oil and refined products, a fifth of global consumption. Gulf producers redirected what they could. Saudi Arabia sent oil through its pipeline to the Red Sea port of Yanbu. The United Arab Emirates pushed its Fujairah port, outside the strait, close to capacity. Even so, these workarounds offset only a fraction of lost Hormuz volumes.
Beyond crude, refined product output in the gulf region dropped significantly, hitting diesel and jet fuel hardest—products in which the region accounts for about 10 percent of global supply.

By the end of May, more than 1.1 billion barrels of crude—equivalent to about 10 days of typical global consumption—had not reached the market. At the same stage of the disruption, the shortfall exceeded those of the 1973 oil shock, the Iran-Iraq war, and the Gulf War.

Three shock absorbers
How did the global system absorb a disruption of this scale? In the days before the war, supply was running about 2 million barrels a day above demand, providing a head start. In the March-May period, three factors helped close the gap:

Demand compression did the heavy lifting, especially in Asia, as higher prices reduced consumption and economies turned to alternatives such as coal and renewables. Transportation demand proved stickier though, in part because of fuel price caps, subsidies, and tax rebates that contained the impact—but at a fiscal cost.
Production outside the gulf rose more than expected, by nearly 2 million barrels a day above 2025 levels. The United States led the way, with Venezuela, Guyana, and Russia also raising production.
Inventories did the rest. The estimated market deficit of about 4.0 million barrels a day in March–May was met almost entirely by drawing down global stocks, including commercial inventories in China and strategic reserves.

Recovery won’t be instant
Before the most recent escalation of tensions, the US-Iran framework agreement to reopen the strait sent prices sharply lower, in large part because stranded oil on tankers in the Gulf could rapidly return to the market. Still, much remains uncertain—including when freedom of navigation through the world’s most critical oil chokepoint will be effectively restored, and how quickly shipping, insurance, and operator confidence will follow.
Industry estimates suggest it will take two to three months before a significant share of oil flows can resume following a full reopening of the waterway. A longer-term concern is that prolonged production halts could cause permanent output losses, especially where financing to restart wells is scarce.
Whenever supply begins to recover, the oil deficit will close only gradually, drawing inventories closer to operational minimums—the level below which the physical system itself begins to bind.
Lessons for policymakers
Energy shocks still bite. What cushioned the initial blow this time is that energy markets had room to maneuver and absorb it. As tensions flare again in the Strait of Hormuz, that room is now smaller and shrinking further as spare capacity has been deployed, demand has compressed, and inventories have been drawn down. Unless inventories are replenished, the world will start from a weaker position when the next shock comes.
For policymakers, three lessons stand out:

Inventories matter. Rebuilding them is essential to prepare for future shocks.
A single chokepoint leaves the global economy heavily exposed. Diversifying energy sources—including renewables—is as important as diversifying routes.
Support to consumers should be targeted to the most vulnerable and temporary to protect government budgets and the price signals that encourage energy saving and efficiency.

Energy markets’ flexibility and prompt policy actions bought the global economy time. An enduring US-Iran agreement would create an opening to restore supply. But significant efforts are still critically needed to increase the resilience and diversification of energy supply and prevent oil shocks from destabilizing the global economy.
 
Authors:
Jean-Marc Natal,
Azim Sadikov
 
Compliments of the IMFThe post IMF | The Oil Market Absorbed the War Shock, but Buffers Are Running Low first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

ECB | How Banks Have Adjusted Their Lending in Response to Trade Tensions

Blog post | Changes in global trade policies and heightened trade tensions pose a challenge for euro area firms, particularly those operating internationally. For banks, these developments increase credit risk: the firms affected can face volatile demand, supply disruptions and squeezed margins, and may find it harder to service their debts.
This post looks at how euro area banks have responded to rising trade tensions since 2025, drawing on granular analyses of loan portfolios from AnaCredit and survey data from the euro area bank lending survey (BLS). It focuses on trade with the United States, which has been at the centre of recent policy shifts, including the broad-based tariffs imposed in 2025.[1]
Our findings show that banks have responded to these risks by stepping up their monitoring of exposed borrowers. They have also adopted a more cautious stance when lending to firms. These adjustments were more pronounced among the banks most heavily exposed to trade risks, particularly where such risks compounded existing corporate vulnerabilities. For firms, higher trade risks have not only led to tighter lending conditions, they have also dampened loan demand.
Uneven trade risk across euro area banks’ loan portfolios
Euro area banks’ exposure to trade risk depends on both the importance of trade for their corporate borrowers and the share of affected firms or sectors in their loan portfolios. We measure this exposure in two steps. First, we calculate the share of euro area value added consumed in the United States and the share of US value added embedded in euro area firms’ output. Second, we average these shares at bank level, weighting them by each individual bank’s exposure to specific countries and sectors.[2] This allows us to capture the exposure of euro area banks to trade with the United States through their loan portfolios, based on how reliant their corporate borrowers are on exports to and imports from the United States. Chart 1 shows how these exposures are distributed across banks.

Chart 1

Distribution of euro area banks’ exposures to trade with the United States

(y-axis: kernel density across banks, x-axis: trade exposure at bank level, percentage)

Sources: ECB (AnaCredit), European Commission (Figaro) and ECB calculations.
Notes: The chart shows euro area banks’ exposure to trade with the United States, calculated using value added in trade flows between the regions, including indirect links through other countries across value chains. Exports represent the share of euro area value added consumed in the United States, and imports represent the share of US value added embedded in euro area firms’ output. At the bank level, exposure is averaged based on the trade exposure of counterparties’ sectors, weighted by loan volumes. A kernel density chart estimates the distribution of a continuous variable with a smoothed curve; higher values indicate more common observations, and the total area under the curve equals 1. The chart combines 2023 trade data with December 2024 loan data to assess banks’ potential vulnerability to trade shocks in 2025.
Latest observations: December 2024 (AnaCredit) and 2023 (Figaro).

Three key insights emerge:[3]
First, euro area banks are more exposed to US export-related risks than to import-related risks. In Chart 1, the blue area (showing goods and services exported to the United States) is positioned further to the right, indicating higher overall exposure. Meanwhile, the yellow area (representing goods and services imported from the United States) is concentrated further to the left, reflecting lower exposure.
Second, export-related risks from trade with the United States vary from bank to bank, as indicated by the wide blue distribution, with many banks only moderately exposed. By contrast, import-related risks are concentrated in the low-exposure range, suggesting that most banks face limited risks from imports from the United States.
Third, a small number of banks are highly exposed to trade risks stemming from euro area exports to the United States, as shown by the long right tail of the blue distribution.
So how are these exposures affecting lending by euro area banks? In 2025, about half of the banks participating in the euro area BLS reported that trade risks were important, and expected similar levels of exposure in 2026.[4] High tariffs on EU exports to the United States and ongoing trade uncertainty may therefore influence banks’ credit conditions, as explored in the following section.
Trade tensions and tighter credit supply
Rising trade tensions are likely to have led to stricter lending conditions for firms, particularly those reliant on exports to the United States. To quantify this effect, we analyse the relationship between bank lending and banks’ exposure to trade risks in export markets. Since changes in lending can also reflect weaker loan demand, driven by a decline in investment owing to tariffs and uncertainty, we have used granular AnaCredit data to isolate the effect on bank loan supply.[5]
Chart 2 suggests that the banks most exposed to borrowers exporting to the United States have reduced their loan supply the most since April 2025. This decline coincided with heightened trade tensions, particularly the threat of tariffs. The dampening impact on loan supply is estimated to be have been most pronounced between April and October 2025, when US-EU trade disputes were at their peak. It then moderated later that year as trade sentiment improved following the preliminary US-EU trade framework agreement negotiated over the summer and as policy uncertainty eased.[6]
These findings highlight how a volatile trade environment and higher tariffs can influence banks’ risk assessment, leading to tighter credit supply.[7]
Chart 2
Relationship between bank loan supply and exposure to US-exporting borrowers

(impact of a one standard deviation increase in export exposure to the United States on supply-driven three-month loan growth (standard deviation, %))

Sources: ECB (AnaCredit), ECB Supervisory Reporting, Amiti and Weinstein (2018) and ECB calculations.
Notes: The chart shows the estimated effects of bank-level export exposure to the United States on supply-driven three-month loan growth. Loan supply is identified following Amiti and Weinstein (2018). The construction of the bank-level export exposure measure is described in the notes to Chart 1. Regressions include bank and time fixed effects and control for the interaction between bank size and time. Positive (negative) values indicate an expansion (contraction) in loan supply.

Data from the BLS bear this out.[8] Since mid-2025, several banks have reported changes in lending behaviour due to trade risks. While some banks opted to monitor the situation closely without altering credit standards, others tightened them, particularly for firms in sectors highly exposed to trade risks. In some cases (e.g. in the car industry) trade-related tightening compounded pre-existing structural vulnerabilities.
A net 11% of banks reported stricter credit standards in 2025 owing to changes in global trade policies and the associated uncertainty, with similar effects expected in 2026 (Chart 3). These decisions were driven by lower risk tolerance and concerns over credit quality, reflecting heightened prudence despite banks’ solid balance sheets overall. Meanwhile, trade tensions also dampened firms’ loan demand: a net -6% of banks reported a decrease in 2025, while a net -3% expected this decline to continue in 2026.[9]
Chart 3
Impact of changes in trade policies and related uncertainty on credit standards and firms’ demand for loans

(net percentages of banks reporting a tightening/easing impact on credit standards (+/-), a deterioration/improvement in banks’ situation (+/-) and a positive/negative impact on loan demand (+/-))

Sources: ECB (BLS).
Notes: Net percentages for credit standards (loan demand) refer to the difference between the percentage of banks reporting a tightening impact on credit standards (a positive impact on loan demand) and the percentage reporting an easing impact on credit standards (a negative impact on loan demand). For the impact of trade policies on banks’ situation, net percentages refer to the difference between the percentage of banks reporting a deterioration/tightening impact and the percentage of banks reporting an improvement/easing impact. “Credit quality” refers to the non-performing loan (NPL) ratio and other indicators of credit quality. Latest observations: 2025 (past) and 2026 (expected).

Conclusions
Overall, economic policy uncertainty has weakened credit dynamics.[10] Recent trade tensions have exacerbated this impact, not only by reducing loan demand but also by prompting the banks most exposed to firms exporting to the United States to further tighten their lending conditions. While euro area banks continue to maintain robust balance sheets, they have been forced to adjust their strategic planning regularly and adopt more cautious lending practices in order to navigate these trade-related risks.
The views expressed in each blog entry are those of the author(s) and do not necessarily represent the views of the European Central Bank and the Eurosystem.
 
Compliments of the European Central Bank.The post ECB | How Banks Have Adjusted Their Lending in Response to Trade Tensions first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

Read More
EACC

IMF | Financial Market Reforms Could Lift Europe’s Growth

IMF Blog post | Integrating and deepening banking and venture capital markets would boost output by at least 3 percent, and make business dynamism reforms more powerful
French startup Mistral AI’s recent financing round was led by ASML, a Dutch maker of semiconductor manufacturing equipment. Such cross-border investments—even when small relative to US deals—are not the norm in Europe. Far more often, good projects fail to scale. Among the reasons: Europe’s considerable savings are compartmentalized within national borders, and hard to connect to high-risk, high-return projects.
The main burden falls on Europe’s young and innovative companies, as we show in a new IMF Staff Discussion Note exploring how fragmented and shallow European financial markets continue to hold back their growth. For investors, especially individuals, this means less opportunity to diversify risks and insulate themselves from domestic turmoil by investing abroad. The note shows that differences in banking regulations, safety nets (notably deposit insurance) and insolvency regimes across countries impede cross-border bank lending. Meanwhile, rules that limit provision of risk capital by pension funds and insurers limit the scale of venture capital.
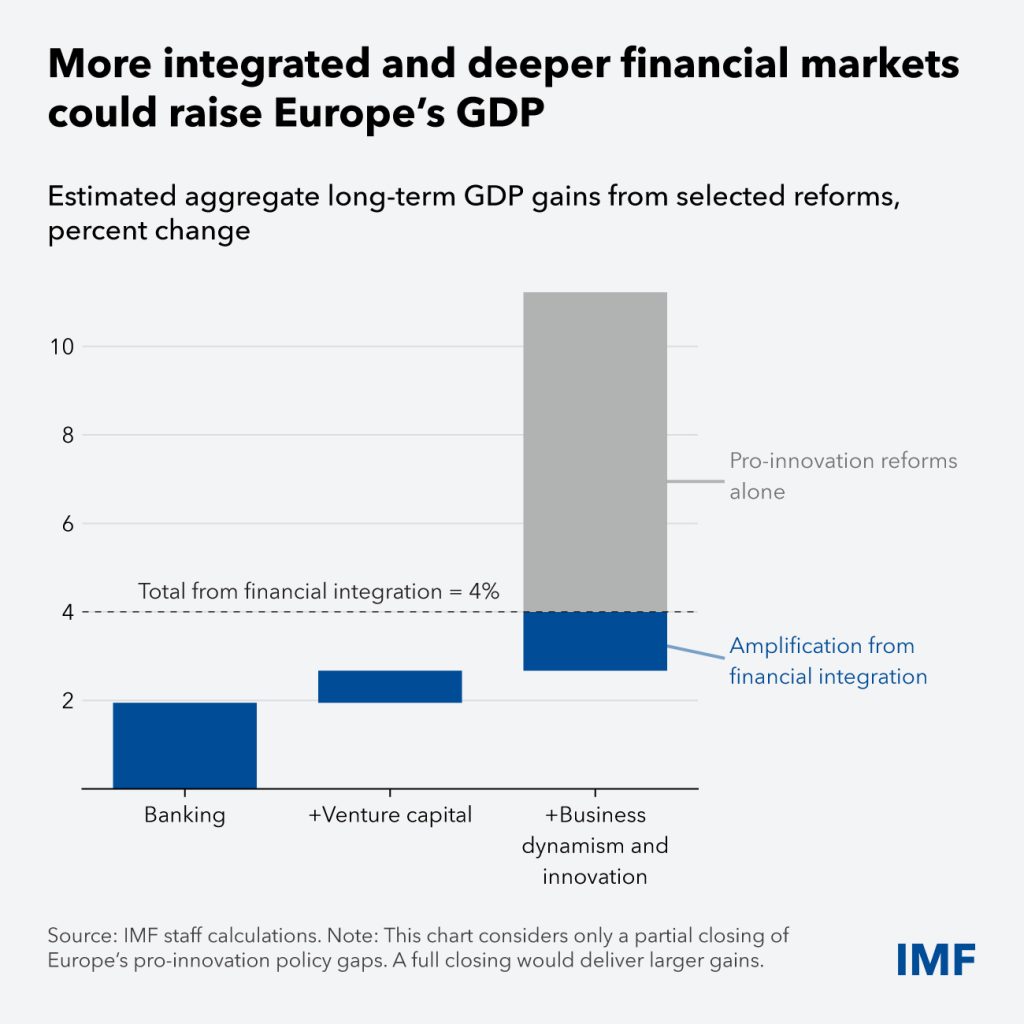
As this Chart of the Week shows, even a moderate reform effort that reduces barriers to cross-border banking could raise European Union GDP by about 2 percent in the long term. These gains would come from better allocating savings across countries and companies, as well as businesses being able to reach potential lenders, which would lower funding costs. Adding reforms to ease legal and tax-related impediments to cross-border venture capital investment, together with measures to expand long-term risk capital through pension and insurance reforms, could bring the estimated gain from financial reforms close to 3 percent.
These financial reforms reinforce significant gains that could come from boosting business dynamism and innovation. Making Europe a more dynamic place to start and grow new businesses—for example by improving the business environment, investing in skills, and supporting research and development—would raise the pool of projects with high potential returns. Combining financial and real economy reforms can lift the long-term GDP gain into double digits.

Europe needs action on three fronts:

Pressing ahead on the banking union by reducing regulatory and institutional differences, and harmonizing insolvency frameworks.  Completing the financial safety net, including through a European deposit insurance scheme, would reduce adverse sovereign-link bank feedback loops, supporting economic and financial resilience overall.
Strengthening venture capital and equity financing more broadly by expanding the pool of long-term risk capital, and easing cross-border investment frictions.
Improving the business environment so that this newly available capital finds more attractive projects to finance.

Innovation and finance go together: reforms that create more promising companies will go further when Europe’s savings can flow freely to fund them.
Authors:
Luis Brandão-Marques, Damien Capelle, Diego Cerdeiro, Rui C. Mano

 
Compliments of the IMFThe post IMF | Financial Market Reforms Could Lift Europe’s Growth first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

European Commission | Review Finds Foreign Subsidies Regulation Fit for Purpose, Commission Considers Targeted Changes

The European Commission’s first review of the Foreign Subsidies Regulation (FSR) has found that the regulation is fit for purpose to address distortions in the internal market caused by foreign subsidies. Its objective of maintaining a level playing field in the internal market is widely acknowledged and remains relevant.
The review of the first three years of FSR enforcement shows the instrument is working well in practice. The procedures for reviewing concentrations and foreign financial contributions in public procurement procedures are important components of the FSR framework, enabling the Commission to identify and address potentially distortive foreign subsidies before a merger is concluded or a high-value public contract is awarded. The Commission’s ‘ex officio’ powers provide an effective complementary framework to investigate and address potential distortive foreign subsidies in the internal market.
At the same time, the review shows certain concerns about complexity and administrative burden, so the Commission is looking into ways to simplify where possible.
Stakeholders confirm FSR’s relevance while calling for simplification
Feedback from most stakeholders through targeted consultations underlines that the FSR framework is overall fit for purpose.
In concentration cases, replies to consultations and early enforcement practice highlight the value of prenotification engagements, which improve clarity and efficiency in the notification process. Stakeholders have also welcomed the available exceptions to reporting obligations and the possibility of requesting waivers for certain information requirements.
In public procurement cases, the Commission successfully reviewed over 5,000 submissions, ensuring public authorities could secure essential goods and services without delays. While formal prenotifications remained low, the Commission proactively managed numerous requests from companies and public authorities to guarantee smooth and efficient procedures.
In ex officio cases, the recent opening of in-depth investigations in two cases, one concerning threat detection systems and the other in the wind sector, offers further insight into the Commission’s approach when assessing potentially distortive foreign subsidies.
At the same time, the review highlighted some areas of concern:

the administrative burden in the collection and reporting of data on foreign financial contributions (FFC);
the length and complexity of certain procedures linked to the investigations;
the uncertainty over the Commission’s call-in powers for below-threshold concentrations, despite their legitimate aim; and
the need for enhanced clarity regarding certain reporting obligations, as well as greater transparency in enforcement practice.

Commission to propose adjustments to FSR framework
Considering these findings, the Commission will launch initiatives to make some targeted adjustments to the FSR procedural framework. These adjustments may include, in particular:

Under the concentration chapter:

Increasing the turnover notification threshold through a delegated act;
Introducing a simplified notification possibility for specific cases or FFCs;
Moderately increasing the reporting thresholds for FFCs;
Introducing additional exemptions from reporting requirements for FFCs not categorised as foreign subsidies most likely to distort the internal market.

Under the public procurement chapter:

Introducing simplifications and clarifications in the forms used for notifications and declarations;
Revising the framework for companies to request waivers to limit the disclosure of information of certain FFCs;
Clarifying and limiting the reporting of FFCs not categorised as foreign subsidies most likely to distort the internal market;
Clarifying the rights and obligations of companies and the contracting authority, including for processing of confidential information, in the context of access to files.

These adjustments would reduce the administrative burden related to the number of submissions, streamline reporting requirements and ensure a focus on cases that are more likely to raise concerns, while preserving the effectiveness of the FSR.
The Commission has started work on the targeted adjustments. The draft targeted adjustments will be published in the autumn, giving stakeholders the possibility to submit comments. Based on the feedback and any additional evidence gathered, the Commission will adopt the targeted adjustments in 2027.
Background
Under Article 52(2) of the FSR, the Commission is obliged to review its practice of implementing and enforcing the rules every three years, and present a report to the European Parliament and the Council. This is to ensure that the regulation meets its objectives and remains effective in preventing distortions in the internal market caused by foreign subsidies.
The present review is based on a comprehensive analysis, including the assessment of 103 contributions received from two consultations, and on an independent study conducted by an external party. This input has helped the Commission assess the impact of the FSR and identify targeted adjustments to its framework.
 
Compliments of the European CommissionThe post European Commission | Review Finds Foreign Subsidies Regulation Fit for Purpose, Commission Considers Targeted Changes first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

USTR | Public Hearings on Proposed Responsive Action in the Section 301 Investigations Relating to Failures to Take Action on Trade in Forced Labor Goods

WASHINGTON – The Office of the United States Trade Representative (USTR) will hold public hearings starting on Tuesday, July 7 and continuing through Thursday, July 9, regarding proposed responsive action in the Section 301 investigations of the acts, policies, and practices, of 60 economies related to the failure to impose and effectively enforce a prohibition on the importation of goods produced with forced labor.
The hearings will be held at the U.S. International Trade Commission (500 E Street SW, Washington, DC) starting at 10:00 am ET.
Please consult the USTR website for the hearings schedule.
Note: The hearings are on the record but no external cameras or video recording will be allowed in the hearing room. The hearings will not be livestreamed. A full transcript of the hearings will be posted on ustr.gov after the hearings. Please contact media@ustr.eop.gov with questions or for more information on media arrangements.
 
 
Compliments of the Office of the United States Trade Representative The post USTR | Public Hearings on Proposed Responsive Action in the Section 301 Investigations Relating to Failures to Take Action on Trade in Forced Labor Goods first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

EU Commission | New EU Plan to Address the Risks and Opportunities of Advanced AI for Cybersecurity

The European Commission has presented a plan to address the risks and harness the opportunities of advanced artificial intelligence (AI) in cybersecurity.
While the AI can improve security, it can also be misused to identify vulnerabilities, automate attacks, and significantly increase the scale and speed of cyber incidents. The new plan will bring together EU countries, industry, and EU-level organisations to strengthen the cybersecurity of our digital landscape against the vulnerabilities posed by advanced AI.
Key actions

Evaluating AI models: The AI Act requires advanced AI models to be evaluated and their risks to be assessed before they are placed on the EU market. The Commission will help establish an EU evaluation capacity to strengthen third-party assessment of AI capabilities and risks globally, supporting the regulatory function of the AI Office.
Accessing advanced AI models: Europe needs clear and transparent conditions for accessing the most advanced AI systems. The Commission will work with the EU Agency for Cybersecurity to define a European blueprint for structured access to advanced AI capabilities for cybersecurity, supporting public and private organisations in accessing advanced AI models.
Testing AI for cybersecurity: The EU Agency for Cybersecurity and the Commission’s Joint Research Centre will create a secure platform to test AI for cybersecurity, including using simulated environments. This will bring know-how on the safe use of AI to operators in critical sectors.
Reinforcing the EU’s cybersecurity and fixing vulnerabilities: The EU must protect its critical infrastructure. In line with the EU’s cybersecurity rules, organisations should intensify cyber hygiene practices, risk management measures, and security by design principles. They should also start using available AI capabilities to fix vulnerabilities faster, as well as prevent and respond to cyberattacks. EU Agency for Cybersecurity will assist them in this transition, including guidance, recommendations, and best practices, as well as a campaign to secure critical open source software.
Scaling European AI capabilities for cyber: The EU must continue investing in its own advanced AI capabilities. For this, the AI Factories and future Gigafactories infrastructure and the European Tech equity capacity, announced in the Tech Sovereignty Package, are available. The Commission will also launch the EU Grand Challenge on AI for cybersecurity, bringing together companies, researchers, and organisations to develop AI solutions for cybersecurity and support the growth of the EU market.

The new plan aims to strengthen the EU’s cybersecurity framework. It builds on existing EU rules, including the AI Act, the Cyber Resilience Act, the Network and Information Systems Directive, and the Cyber Solidarity Act.
 
 
Compliments of the European Commission The post EU Commission | New EU Plan to Address the Risks and Opportunities of Advanced AI for Cybersecurity first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

European Parliament | MEPs Strengthen the EU’s Carbon Border Adjustment Mechanism and Close Loopholes

Long list of downstream products added to carbon border adjustment mechanism (CBAM)

Tougher anti-circumvention rules to prevent abuse

A temporary decarbonisation fund to protect EU firms in export markets

Environment Committee MEPs have backed extending the EU’s carbon border adjustment mechanism to downstream goods and setting up a fund to support industry’s low-carbon transition.

The Committee on the Environment, Climate and Food Safety adopted its position on proposed changes to the CBAM by 56 to 11, with 12 abstentions.
The MEPs agree with the Commission’s proposal to extend the scope of CBAM beyond basic materials to a long list of downstream products – finished steel and aluminium goods such as fasteners, wire, springs and household articles – but insist it must be based on transparent, quantitative methodologies. They also added an exemption for electricity flows from non-EU countries used by grid operators to keep networks stable.
Closing loopholes
On anti-circumvention rules, the MEPs clarified that the practice of “slightly modifying” goods must also cover slight processing and tightened the rule so it targets only arrangements set up purely to dodge CBAM, and not normal business decisions to lower a company’s costs.
They also empowered the Commission to apply the true country of origin’s default values where a pattern of circumvention is found. They deleted the Commission’s proposed safeguard that would have allowed goods to be removed from the scope in the event of price shocks.
The committee also wants new rules for online sales to close an online imports loophole. It recommends a single weight-based limit be applied to a seller’s shipments as a whole, rather than parcel by parcel, with new reporting duties, and retroactive liability for shipments that are split to stay under the threshold.
Finally, the MEPs propose simplified reporting for least-developed countries and a technical assistance framework, but removed the Commission’s option to count Paris Agreement Article 6 carbon credits against CBAM obligations, since this issue is likely to be discussed in the context of the upcoming revision of the EU emissions trading system (ETS).
Temporary decarbonisation fund
The Environment Committee also adopted their position on the related temporary decarbonisation fund (TDF) to protect EU producers on export markets, by 59 votes to 16, with 6 abstentions.
The MEPs want financial support from the TDF to run from 2027 to 2029 and not only from 2028 as proposed by the Commission. As fertilisers are a strategic input for food security, they also want to open the fund to fertiliser producers and downstream users facing higher carbon-related input costs, with products such as urea, ammonium nitrate and ammonium sulphate added to the list of eligible goods.
Finally, all downstream operators – firms that use CBAM-covered goods as inputs in their production – should be eligible for support from the fund, while leftover revenue could be redirected to the EU’s international climate finance commitments under the Paris Agreement instead of being returned to member states, as the Commission proposed.
Quotes
CBAM rapporteur Mohammed Chahim (S&D, NL) said: “This compromise makes the CBAM stronger, fairer and more resilient. We have closed important loopholes, strengthened enforcement against circumvention, and expanded the mechanism’s scope where it matters most. It is a balanced package that protects European industry as it decarbonises while safeguarding the environmental integrity of the mechanism.”
Rapporteur for the temporary decarbonisation fund Pascal Canfin (Renew, FR) said: “Today we have taken a big step towards making Europe a safe place for investment in decarbonisation: we are broadening product coverage to enhance the level playing field and we are setting out stronger anti-circumvention rules, notably against resource shuffling from China. We are also offering a more robust solution for our farmers hit by fertiliser costs, and an export scheme to protect our companies on export markets where their competitors do not pay a carbon price.”
Next steps
Parliament is scheduled to adopt its mandate for negotiations with EU member states on the final shape of the bill during the September plenary session.
Background
The EU’s carbon border adjustment mechanism is the EU’s tool to equalise the price of carbon paid for EU products operating under the ETS with that of imported goods, to reduce the risk of carbon leakage and to encourage greater climate ambition in non-EU countries. In 2025, Parliament adopted simplification measures to exempt 90% of importers from CBAM rules while still maintaining climate ambition, as 99% of CO2 emissions are still covered.


Compliments of the European Parliament The post European Parliament | MEPs Strengthen the EU’s Carbon Border Adjustment Mechanism and Close Loopholes first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.