
Last Thursday we held our 2024 M&A Summit in London, where we were joined by over 100 market experts, corporates intermediaries and investors to discuss the global deal landscape.
25
Apr
Last Thursday we held our 2024 M&A Summit in London, where we were joined by over 100 market experts, corporates intermediaries and investors to discuss the global deal landscape.
Loyens & Loeff New York regularly posts ‘Snippets’ on a range of EU tax and legal topics. In a previous Snippet, we described hybrid financing arrangements (HFAs) under article 3.2.7 of the Pillar Two (P2) model rules. This Snippet describes the treatment of certain HFAs under the P2 guidance published by the OECD in December 2023 (the Guidance) for purposes of the transitional country-by-country reporting safe harbour (SH) rules.
The leading Dutch legal journal on private international law (NIPR) published a commentary written by members of our Litigation & Risk Management team.
Middels de EU Green Deal en het EU Fit for 55 pakket komen er een hoop klimaatmaatregelen op Nederland af. Dat klimaatmaatregelen nodig zijn is duidelijk – en het klimaat heeft niet alleen baat bij bij het extra beprijzen van vervuiling (door bijvoorbeeld een co2-heffing), ook kan de overheid groene investeringen stimuleren. Dit maakt groene investeringen en ontwikkelingen interessanter en lucratiever. Natuurlijk ook met als doel: zo snel mogelijk minder uitstoot, op een duurzame manier.
On 12 March 2024, the European Parliament approved the proposed Cyber Resilience Act (Proposal for a regulation on horizontal cybersecurity requirements for products with digital elements; “CRA“). The CRA now has to be formally adopted by the European Council in order to come into law. This is expected in April 2024.
The Commission has adopted an amendment to the 2023-24 Work Programme of Horizon Europe, the EU’s research and innovation programme. The amendment mobilises previously unallocated Horizon Europe funding to increase the 2024 budget by nearly €1.4 billion to a total of €7.3 billion. This amendment includes an investment of nearly €650 million in the EU Missions aiming to contribute to solving some of the challenges facing Europe, for example, making more than 100 cities climate neutral, a New European Bauhaus facility, as well as experimental actions opening EU research and innovation opportunities to more newcomers, among other novelties.
Some of the main features of this update of the Horizon Europe Work Programme include:
EU Missions
The EU will invest €648 million in 2024 in research and innovation activities underpinning the EU Missions. The EU Missions cover five areas and are a novelty brought by Horizon Europe to bring concrete solutions to some of our greatest challenges. They have ambitious goals and will deliver concrete results by 2030. The new actions for 2024 should result in restoring at least 25 000 km of free-flowing rivers, Climate City Contracts with more than 100 cities, 100 living labs and lighthouses leading the transition towards healthy soils, local and regional authorities better prepared to face climate-related risks, better cancer diagnosis and support to young cancer sufferers.
New European Bauhaus
The New European Bauhaus (NEB) aims to bring the benefits of the European Green Deal into people’s daily lives and living spaces. In the three years since its launch, the NEB has provided solutions to concrete problems. Examples include the TOVA project from Spain that developed a 3D printing technique with earth to provide architectural solutions for sustainable, affordable, community-based housing. Another example is the WATSUPS project from Belgium that creates a new public space alongside the river Dyle to mitigate the risk of gentrification. These solutions are rooted in research and innovation that place the Europeans at the heart of the green transformation.
A new NEB Facility will ensure that Europe continues to make most of this potential. It brings multi-annual budget support for 2025-2027 through two pillars, a research and innovation part to develop new ideas and a roll-out part to scale-up such solutions. The amended Horizon Europe work programme 2023-24 allocates €20 million to preparing the ground for the implementation of the NEB Facility.
Experimental actions to attract newcomers
This amendment includes a package of new experimental actions to reinforce the openness of the programme, support the goals of the EU Missions and foster young researchers’ careers. They will test new approaches in view of preparations for the last three years of Horizon Europe as well as of its future successor programme.
The actions include four open topics giving researchers more freedom to focus their work on a subject they choose with a total budget of €76 million in Horizon Europe Clusters addressing ‘Health’, ‘Climate, energy and mobility’ and ‘Food, Bioeconomy, Natural Resources, Agriculture and Environment’. An experimental action of €15 million for the EU Missions will make knowledge institutions such as universities or research organisations focal points of local transdisciplinary research and innovation activities with European outreach. In addition, the NEB call ‘Transforming neighbourhoods, making them beautiful, sustainable, and inclusive’ also aims to attract newcomers to the programme to maximise impact. Finally, €20 million will support talent ecosystems for attractive early research careers.
Cultural Heritage
The amendment also dedicates €48 million to the European Collaborative Cloud for Cultural Heritage. This new digital collaborative space will support cultural heritage institutions and researchers as well as the cultural and creative industries to reap the benefits of the digital transition. It will complement the common European Data Space for Cultural Heritage (the Data Space) funded under the Digital Europe programme.
Pandemic preparedness
The COVID-19 pandemic highlighted the challenges faced by European health care systems in detecting, preventing, fighting and managing outbreaks of infectious diseases. To help equip Europe for potential future pandemics, the amended work programme includes an investment of €50 million for a European Partnership for pandemic preparedness.
Paving the way for 2025
Calls for 2025 are also included in the amendment to ensure continuity of certain recurrent actions, such as the Marie Skłodowska-Curie Actions (MSCA) and ‘Teaming for Excellence’ and ‘ERA (European Research Area) Fellowships’ in the ‘Widening participation and spreading excellence’ and ‘Reforming and Enhancing the European R&I system’ part. The Commission plans to roll out the full range of actions for 2025 in a dedicated work programme in 2025.
Background
Horizon Europe is the EU’s research and innovation programme for 2021-27. Originally working with €95.5 million over seven years, the European Council decided to reduce its budget by €2.1 billion as part of the mid-term revision of the EU’s long-term budget to allow the Union to finance other urgent priorities such as aid to Ukraine. The cut has been reduced by €100 million stemming from the re-use of decommitments, therefore, the reduction in 2025-27 will amount to €2 billion.
The 2023-24 Horizon Europe work programme was adopted on 6 December 2022 and first amended on 31 March 2023. It is based on Horizon Europe’s Strategic Plan 2021-2024, adopted in March 2021, which was co-designed with stakeholders, the European Parliament and the Member States.
Today’s amendment rolls out the investment for the EU Missions, which had been held back from the original work programme 2023-24 to enable the implementation of the Communication “EU Missions two years on: assessment of progress and way forward”, adopted on 19 July 2023.
Compliments of the European Commission.The post Commission Mobilizes Research and Innovation Funding for the Green and Digital Transitions first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.
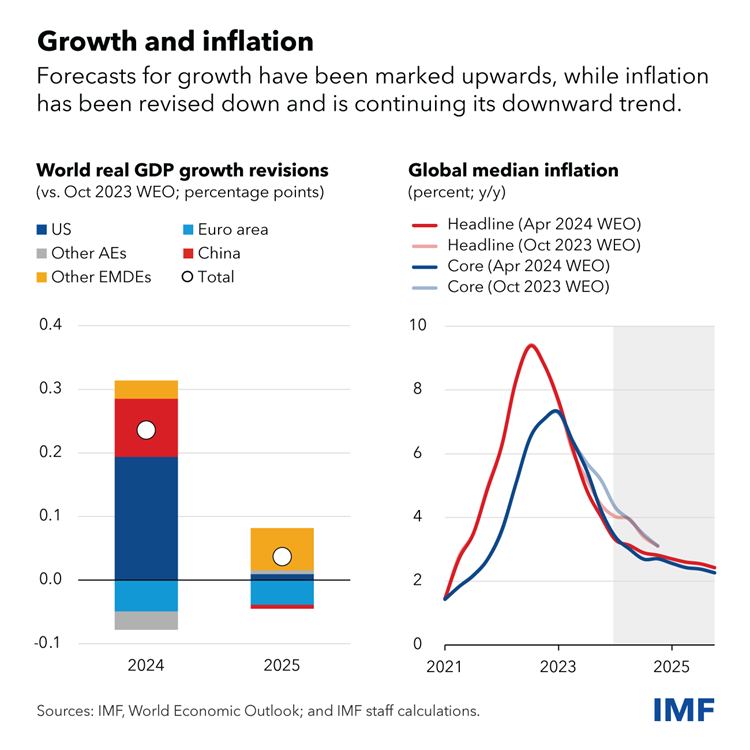
Despite gloomy predictions, the global economy remains remarkably resilient, with steady growth and inflation slowing almost as quickly as it rose. The journey has been eventful, starting with supply-chain disruptions in the aftermath of the pandemic, an energy and food crisis triggered by Russia’s war on Ukraine, a considerable surge in inflation, followed by a globally synchronized monetary policy tightening.
Global growth bottomed out at the end of 2022, at 2.3 percent, shortly after median headline inflation peaked at 9.4 percent. According to our latest World Economic Outlook projections, growth this year and next will hold steady at 3.2 percent, with median headline inflation declining from 2.8 percent at the end of 2024 to 2.4 percent at the end of 2025. Most indicators continue to point to a soft landing.
We also project less economic scarring from the crises of the past four years, although estimates vary across countries. The US economy has already surged past its prepandemic trend. But we now estimate that there will be more scarring for low-income developing countries, many of which are still struggling to turn the page from the pandemic and cost-of-living crises.
Resilient growth and rapid disinflation point toward favorable supply developments, including the fading of energy price shocks, and a striking rebound in labor supply supported by strong immigration in many advanced economies. Monetary policy actions have helped anchor inflation expectations even if its transmission may have been more muted, as fixed-rate mortgages became more prevalent.
Despite these welcome developments, numerous challenges remain, and decisive actions are needed.
Inflation risks remain
Bringing inflation back to target should remain the priority. While inflation trends are encouraging, we are not there yet. Somewhat worryingly, progress toward inflation targets has somewhat stalled since the beginning of the year. This could be a temporary setback, but there are reasons to remain vigilant. Most of the good news on inflation came from the decline in energy prices and in goods inflation. The latter has been helped by easing supply-chain frictions, as well as by the decline in Chinese export prices. But oil prices have been rising recently in part due to geopolitical tensions and services inflation remains stubbornly high. Further trade restrictions on Chinese exports could also push up goods inflation.
Economic divergences widen
The resilient global economy also masks stark divergence across countries.
The strong recent performance of the United States reflects robust productivity and employment growth, but also strong demand in an economy that remains overheated. This calls for a cautious and gradual approach to easing by the Federal Reserve. The fiscal stance, out of line with long-term fiscal sustainability, is of particular concern. It raises short-term risks to the disinflation process, as well as longer-term fiscal and financial stability risks for the global economy. Something will have to give.
Growth in the euro area will rebound but from very low levels, as past shocks, and tight monetary policy weigh on activity. Continued high wage growth and persistent services inflation could delay the return of inflation to target. However, unlike in the United States, there is little evidence of overheating, and the European Central Bank will need to carefully calibrate the pivot toward monetary easing to avoid an inflation undershoot. While labor markets appear strong, that strength could prove illusory if European firms have been hoarding labor in anticipation of a pickup in activity that does not materialize.
China’s economy remains affected by the downturn in its property sector. Credit booms and busts never resolve themselves quickly, and this one is no exception. Domestic demand will remain lackluster unless strong measures address the root cause. With depressed domestic demand, external surpluses could well rise. The risk is that this will further exacerbate trade tensions in an already fraught geopolitical environment.
Many other large emerging market economies are performing strongly, sometimes benefiting from a reconfiguration of global supply chains and rising trade tensions between China and the US. These countries’ footprint on the global economy is increasing.
Policy path
Going forward, policymakers should prioritize measures that help preserve or even enhance the resilience of the global economy.
The first such priority is to rebuild fiscal buffers. Even as inflation recedes, real interest rates remain high and sovereign debt dynamics have become less favorable. Credible fiscal consolidations can help lower funding costs, improve fiscal headroom and financial stability. Unfortunately, fiscal plans so far are insufficient and could be derailed further given the record number of elections this year.
Fiscal consolidations are never easy but it is best not to wait until markets dictate their conditions. The right approach is to start now, gradually, and credibly. Once inflation is under control, credible multiyear consolidations will help pave the way for further monetary policy easing. The successful 1993 US fiscal consolidation and monetary accommodation episode comes to mind as an example to emulate.
The second priority is to reverse the decline in medium term growth prospects. Some of that decline comes from increased misallocation of capital and labor within sectors and countries. Facilitating faster and more efficient resource allocation will boost growth. For low-income countries, structural reforms to promote domestic and foreign direct investment, and to strengthen domestic resource mobilization, will help lower borrowing costs and reduce funding needs. These countries also must improve the human capital of their large young populations, especially as the rest of the world is aging rapidly.
Artificial intelligence also gives hope for boosting productivity. It may do so, but the potential for serious disruptions in labor and financial markets is high. Harnessing the potential of AI for all will require that countries improve their digital infrastructure, invest in human capital, and coordinate on global rules of the road.
Medium-term growth prospects are also harmed by rising geoeconomic fragmentation and the surge in trade restrictive and industrial policy measures. Trade linkages are already changing as a result, with potential losses in efficiency. The net effect could well be to make the global economy less, not more, resilient. But the broader damage is to global cooperation. It is still time to reverse course.
Third, a great achievement of the past few years has been the strengthening of monetary, fiscal and financial policy frameworks especially for emerging market economies. This has helped make the global financial system more resilient and avoid a permanent resurgence of inflation. Going forward, it is essential to preserve these improvements. That includes protecting the hard-won independence of central banks.
Lastly, the green transition requires major investments. Cutting emissions is compatible with growth and activity has become much less emission-intensive in recent decades. But emissions are still rising. Much more needs to be done and done quickly. Green investment has expanded at a healthy pace in advanced economies and China. The greatest effort must now be made by other emerging market and developing economies, which must massively increase their green investment growth and reduce their fossil fuel investment. This will require technology transfer by other advanced economies and China, as well as substantial private and public financing.
On these questions, as well as on so many others, multilateral frameworks and cooperation remain essential for progress.
—This blog by Pierre-Olivier Gourinchas is based on Chapter 1 of the April 2024 World Economic Outlook.
Compliments of the IMF.The post IMF | Global Economy Remains Resilient Despite Uneven Growth, Challenges Ahead first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.
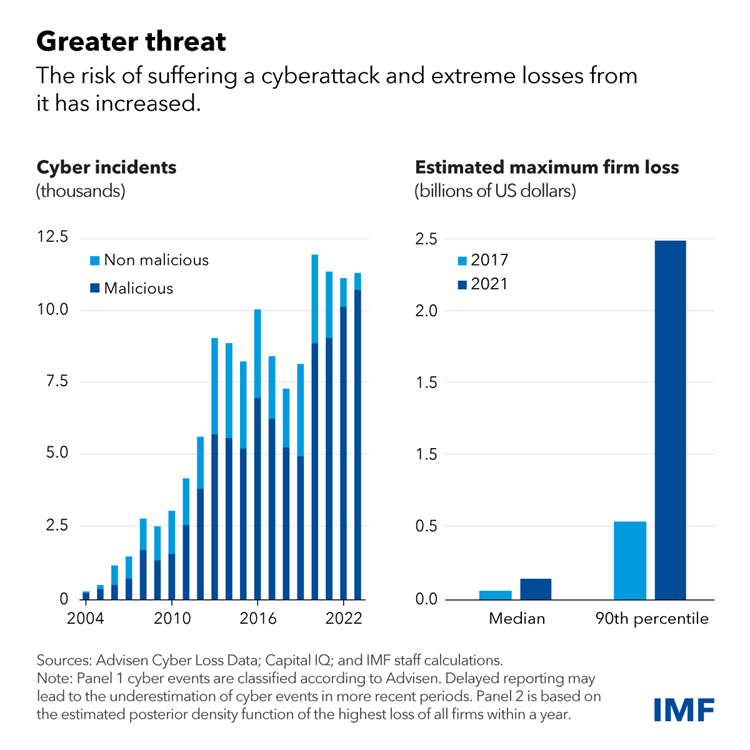
This blog is based on Chapter 3 of the IMF’s April 2024 Global Financial Stability Report | Cyberattacks have more than doubled since the pandemic. While companies have historically suffered relatively modest direct losses from cyberattacks, some have experienced a much heavier toll. US credit reporting agency Equifax, for example, paid more than $1 billion in penalties after a major data breach in 2017 that affected about 150 million consumers.
As we show in a chapter of the April 2024 Global Financial Stability Report, the risk of extreme losses from cyber incidents is increasing. Such losses could potentially cause funding problems for companies and even jeopardize their solvency. The size of these extreme losses has more than quadrupled since 2017 to $2.5 billion. And indirect losses like reputational damage or security upgrades are substantially higher.
The financial sector is uniquely exposed to cyber risk. Financial firms—given the large amounts of sensitive data and transactions they handle—are often targeted by criminals seeking to steal money or disrupt economic activity. Attacks on financial firms account for nearly one-fifth of the total, of which banks are the most exposed.
Incidents in the financial sector could threaten financial and economic stability if they erode confidence in the financial system, disrupt critical services, or cause spillovers to other institutions.
For example, a severe incident at a financial institution could undermine trust and, in extreme cases, lead to market selloffs or runs on banks. Although no significant “cyber runs” have occurred thus far, our analysis suggests modest and somewhat persistent deposit outflows have occurred at smaller US banks after a cyberattack.
Cyber incidents that disrupt critical services like payment networks could also severely affect economic activity. For example, a December attack at the Central Bank of Lesotho disrupted the national payment system, preventing transactions by domestic banks.
Another consideration is that financial firms increasingly rely on third-party IT service providers, and may do so even more with the emerging role of artificial intelligence. Such external providers can improve operational resilience, but also expose the financial industry to systemwide shocks. For example, a 2023 ransomware attack on a cloud IT service provider caused simultaneous outages at 60 US credit unions.
With the global financial system facing significant and growing cyber risks from increasing digitalization and geopolitical tensions, as shown in the chapter, policies and governance frameworks at firms must keep pace.
Because private incentives may be insufficient to address cyber risks—for example, firms may not fully account for the systemwide effects of incidents—public intervention may be necessary.
However, according to an IMF survey of central banks and supervisory authorities, cybersecurity policy frameworks, especially in emerging market and developing economies, often remain insufficient. For example, only about half of countries surveyed had a national, financial sector-focused cybersecurity strategy or dedicated cybersecurity regulations.
To strengthen resilience in the financial sector, authorities should develop an adequate national cybersecurity strategy accompanied by effective regulation and supervisory capacity that should encompass:
Periodically assessing the cybersecurity landscape and identifying potential systemic risks from interconnectedness and concentrations, including from third-party service providers.
Encouraging cyber “maturity” among financial sector firms, including board-level access to cybersecurity expertise, as supported by the chapter’s analysis which suggests that better cyber-related governance may reduce cyber risk.
Improving cyber hygiene of firms—that is, their online security and system health (such as antimalware and multifactor authentication)—and training and awareness.
Prioritizing data reporting and collection of cyber incidents, and sharing information among financial sector participants to enhance their collective preparedness.
As attacks often emanate from outside a financial firm’s home country and proceeds can be routed across borders, international cooperation is imperative to address cyber risk successfully.
While cyber incidents will occur, the financial sector needs the capacity to deliver critical business services during these disruptions. To this end, financial firms should develop, and test, response and recovery procedures and national authorities should have effective response protocols and crisis management frameworks in place.
The authors:
> Fabio Natalucci, Deputy Director of the Monetary and Capital Markets Department, IMF
> Mahvash S. Qureshi, Assistant Director and Division Chief – Monetary and Capital Markets Department, IMF
> Felix Suntheim, Deputy Division Chief in the Global Financial Stability Analysis Division – Monetary and Capital Markets Department, IMF
Compliments of the IMF.The post IMF | Rising Cyber Threats Pose Serious Concerns for Financial Stability first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.
With Up to $6.6 Billion in Proposed CHIPS Direct Funding, TSMC Announces 2 Nanometer Technology at Second Fab and a New Third Fab to Produce 2 Nanometer or More Advanced Chips. Proposed CHIPS Investment in Arizona Would Support AI, High-Performance Computing, 5G/6G Communications, and More Applications.
On April 8th, the Biden-Harris Administration announced that the U.S. Department of Commerce and TSMC Arizona Corporation (TSMC Arizona), a subsidiary of Taiwan Semiconductor Manufacturing Company Limited (TSMC), have signed a non-binding preliminary memorandum of terms (PMT) to provide up to $6.6 billion in direct funding under the CHIPS and Science Act. This proposed funding would support TSMC’s investment of more than $65 billion in three greenfield leading-edge fabs in Phoenix, Arizona, which will manufacture the world’s most advanced semiconductors.
Through this proposed investment in TSMC Arizona, the Biden-Harris Administration would take a significant step in strengthening U.S. economic and national security by providing a reliable domestic supply of the chips that will underpin the future economy, powering the AI boom and other fast-growing industries like consumer electronics, automotive, Internet of Things, and high-performance computing. After initially announcing two fabs in the U.S., TSMC Arizona is committing to build an additional third fab before the end of the decade. With this proposed funding, TSMC Arizona would be ensuring the formation of a scaled leading-edge cluster in Arizona, creating approximately 6,000 direct manufacturing jobs, more than 20,000 accumulated unique construction jobs, and tens of thousands of indirect jobs in this decade and bringing the most advanced process technology to the United States.
“Semiconductors – those tiny chips smaller than the tip of your finger – power everything from smartphones to cars to satellites and weapons systems. America invented these chips, but over time, we went from producing nearly 40% of the world’s capacity to close to 10%, and none of the most advanced chips, exposing us to significant economic and national security vulnerabilities. I was determined to turn that around, and thanks to my CHIPS and Science Act – a key part of my Investing in America agenda – semiconductor manufacturing and jobs are making a comeback,” said President Joe Biden. “TSMC’s renewed commitment to the United States, and its investment in Arizona represent a broader story for semiconductor manufacturing that’s made in America and with the strong support of America’s leading technology firms to build the products we rely on every day.”
“One of the key goals of President Biden’s CHIPS and Science Act was to bring the most advanced chip manufacturing in the world to the U.S., and with this announcement and TSMC’s increased investment in their Arizona campus, we are working to achieve that goal,” said U.S. Secretary of Commerce Gina Raimondo. “The leading-edge semiconductors that will be made here in Arizona are foundational to the technology that will define global economic and national security in the 21st century, including AI and high-performance computing. Thanks to President Biden’s leadership and TSMC’s continued investments in U.S. semiconductor manufacturing, this proposed funding would help make our supply chains more secure and create thousands of good-quality construction and manufacturing jobs for Arizonans.”
“America’s ability to maintain our competitive edge in advanced technologies like artificial intelligence is essential to igniting the next generation of research, innovation, development, and production,” said Under Secretary of Commerce for Standards and Technology and National Institute of Standards and Technology Director Laurie E. Locascio. “Our proposed support for TSMC Arizona represents an inflection point for America’s innovative capacity that would restore our nation’s leadership in an industry that is foundational to the U.S. and global digital economy.”
“The proposed funding from the CHIPS and Science Act would provide TSMC the opportunity to make this unprecedented investment and to offer our foundry service of the most advanced manufacturing technologies in the United States,” said TSMC Chairman Dr. Mark Liu. “Our U.S. operations allow us to better support our U.S. customers, which include several of the world’s leading technology companies. Our U.S. operations will also expand our capability to trailblaze future advancements in semiconductor technology.”
“We are honored to support our customers who have been pioneers in mobile, artificial intelligence and high-performance computing, whether in chip design, hardware systems or software, algorithms, and large language models,” said TSMC CEO Dr. C.C. Wei. “They are the innovators driving demand for the most advanced silicon that TSMC can provide. As their foundry partner, we will help them unleash their innovations by increasing capacity for leading-edge technology through TSMC Arizona. We are thrilled by the progress of our Arizona site to date and are committed to its long-term success.”
TSMC is widely recognized as a global leader in semiconductor manufacturing, having pioneered the pure-play foundry business model in 1987, and now manufactures over 90% of the world’s leading-edge logic chips. In Arizona, TSMC’s three fabs are expected to bring a suite of the most advanced process node technologies to the United States: the first fab will produce 4nm FinFET process technologies; today, TSMC Arizona announced that the second fab will produce the world’s most advanced 2nm nanosheet process technology, in addition to previously announced plans to produce 3nm process technologies; and TSMC Arizona’s third fab will produce 2nm or more advanced process technologies depending on customer demand. At full capacity, TSMC Arizona’s three fabs would manufacture tens of millions of leading-edge chips that will power products like 5G/6G smartphones, autonomous vehicles, and AI datacenter servers. TSMC Arizona expects to begin high-volume production in their first fab in the U.S. by the first half of 2025.
Thanks to investments like those at TSMC Arizona, the United States is now on track to produce roughly 20% of the world’s leading-edge chips by 2030. With total capital expenditures of more than $65 billion, TSMC Arizona’s investment is the largest foreign direct investment in a greenfield project in U.S. history. TSMC Arizona’s investment in the United States is catalyzing meaningful investment across the supply chain, including from 14 direct suppliers that plan to construct or expand plants in Arizona or other parts of the U.S., further strengthening U.S. domestic supply chain resilience.
TSMC’s advanced chips are the backbone of core processing units (“CPUs”) for servers in large-scale datacenters and of specialized graphic processing units (“GPUs”) used for machine learning. Through the proposed funding for TSMC Arizona, the United States would onshore the critical hardware manufacturing capabilities that underpin AI’s deep language learning algorithms and inferencing techniques. This would help strengthen America’s competitive edge in science and technology innovation. Furthermore, through its Arizona fabs, TSMC will be able to better support its key customers, including U.S. companies AMD, Apple, Nvidia, and Qualcomm, among others, by addressing their leading-edge capacity demand, mitigating supply chain concerns, and enabling them to compete effectively in the ongoing digital transformation era. With the proposed incentives, TSMC Arizona has also committed to support the development of advanced packaging capabilities – the next frontier of technology innovation for chip manufacturing – through its partners in the U.S., creating the opportunity for TSMC Arizona’s customers to be able to purchase advanced chips that are made entirely on U.S. soil.
The PMT also proposes $50 million in dedicated funding to develop the company’s semiconductor and construction workforce. To build the long-term construction workforce needed to support these projects, TSMC Arizona recently signed an agreement with the Arizona Building and Construction Trades Council. The company also plans to utilize registered apprenticeship programs to meet a 15 percent apprenticeship utilization rate on the Phoenix construction site.
As part of its commitment to developing local talent, TSMC Arizona established one of the first state-supported Registered Apprenticeship programs for semiconductor technicians, with support from the City of Phoenix. TSMC’s U.S.-based recruiting team is also actively collaborating with university engineering programs around the country, including Arizona State University, University of Arizona, and Purdue University, and is partnering with Maricopa Community Colleges and career technical education programs on initiatives to develop the skills for a career in the semiconductor industry. Site employees have access to discounts, reimbursements, and priority enrollment through partnerships for local area early education and childcare centers.
In addition to the proposed direct funding of up to $6.6 billion, the CHIPS Program Office would make approximately $5 billion of proposed loans – which is part of the $75 billion in loan authority provided by the CHIPS and Science Act – available to TSMC Arizona under the PMT. The company has indicated that it is planning to claim the Department of the Treasury’s Investment Tax Credit, which is expected to be up to 25% of qualified capital expenditures.
As explained in its first Notice of Funding Opportunity, the Department may offer applicants a PMT on a non-binding basis after satisfactory completion of the merit review of a full application. The PMT outlines key terms for a potential CHIPS incentives award, including the amount and form of the award. The award amounts are subject to due diligence and negotiation of a long-form term sheet and award documents and are conditional on the achievement of certain milestones. After the PMT is signed, the Department begins a comprehensive due diligence process on the proposed projects and continues negotiating or refining certain terms with the applicant. The terms contained in the long-form term sheet and the final award documents may differ from the terms of the PMT being announced today.
To learn more about CHIPS for America, visit www.chips.gov.
Compliments of the U.S. Department of Commerce.
The post Biden-Harris Administration Announces Preliminary Terms with TSMC, Expanded Investment from Company to Bring World’s Most Advanced Leading-Edge Technology to the U.S. first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.
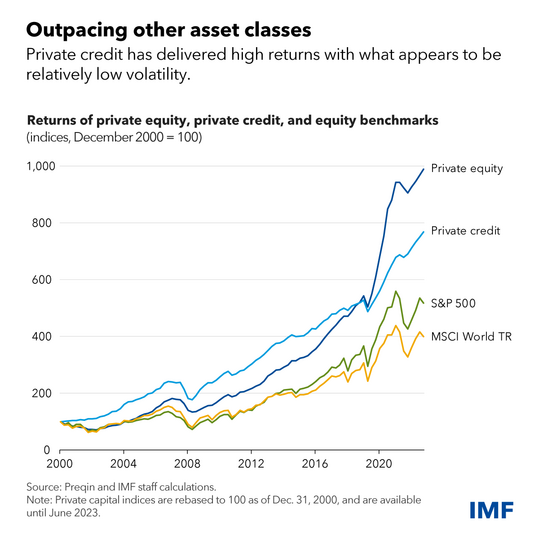
Blog post by Charles Cohen, Caio Ferreira, Fabio Natalucci, Nobuyasu Sugimoto | The private credit market, in which specialized non-bank financial institutions such as investment funds lend to corporate borrowers, topped $2.1 trillion globally last year in assets and committed capital. About three-quarters of this was in the United States, where its market share is nearing that of syndicated loans and high-yield bonds.
This market emerged about three decades ago as a financing source for companies too large or risky for commercial banks and too small to raise debt in public markets. In the past few years, it has grown rapidly as features such as, speed, flexibility, and attentiveness have proved valuable to borrowers. Institutional investors such as pension funds and insurance companies have eagerly invested in funds that, though illiquid, offered higher returns and less volatility.
Private corporate credit has created significant economic benefits by providing long-term financing to corporate borrowers. However, the migration of this lending from regulated banks and more transparent public markets to the more opaque world of private credit creates potential risks. Valuation is infrequent, credit quality isn’t always clear or easy to assess, and it’s hard to understand how systemic risks may be building given the less than clear interconnections between private credit funds, private equity firms, commercial banks, and investors.
Today, immediate financial stability risks from private credit appear to be limited. However, given that this ecosystem is opaque and highly interconnected, and if fast growth continues with limited oversight, existing vulnerabilities could become a systemic risk for the broader financial system.
We identify a number of fragilities in our April 2024 Global Financial Stability Report.
First, companies that tap the private credit market tend to be smaller and carry more debt than their counterparts with leveraged loans or public bonds. This makes them more vulnerable to rising rates and economic downturns. With the recent rise in benchmark interest rates, our analysis indicates that more than one-third of borrowers now have interest costs exceeding their current earnings.
The rapid growth of private credit has recently spurred increased competition from banks on large transactions. This in turn has put pressure on private credit providers to deploy capital, leading to weaker underwriting standards and looser loan covenants—some signs of which have already been noted by supervisory authorities.
Second, private market loans rarely trade, and therefore can’t be valued using market prices. Instead, they are often marked only quarterly using risk models, and may suffer from stale and subjective valuations across funds. Our analysis comparing private credit to leveraged loans (which trade regularly in a more liquid and transparent market) shows that, despite having lower credit quality, private credit assets tend to have smaller markdowns during times of stress.
Third, while private credit fund leverage appears to be low, the potential for multiple layers of hidden leverage within the private credit ecosystem does raise concerns given the lack of data. Leverage is deployed also by investors in these funds and by the borrowers themselves. This layering of leverage makes it difficult to assess potential systemic vulnerabilities of this market.
Fourth, there appears to be a significant degree of interconnectedness in the private credit ecosystem. While banks do not seem to have a material exposure to private credit in aggregate—the Federal Reserve has estimated that US private credit borrowing amounted to less than about $200 billion, less than 1 percent of US bank assets—some banks may have concentrated exposures to the sector. In addition, a select group of pension funds and insurers are diving deeper into private credit waters, significantly upping their share of these less-liquid assets. This includes private-equity-influenced life insurance companies, as we discussed in a recent report.
Finally, though liquidity risks appear limited today, a growing retail presence may alter this assessment. Private credit funds use long-term capital lockups and impose constraints on investor redemptions to align the investment horizon with the underlying illiquid assets. But new funds targeted at individual investors may have higher redemption risks. Although these risks are mitigated by liquidity management tools (such as gates and fixed redemption periods), they have not been tested in a severe runoff scenario.
Overall, although these vulnerabilities currently they do not pose a systemic risk to the broader financial sector, they may continue to build, with implications for the economy. In a severe downturn, credit quality could deteriorate sharply, spurring defaults and significant losses. Opacity could make these losses hard to assess. Banks could curb lending to private credit funds, retail funds could face large redemptions, and private credit funds and their institutional investors could experience liquidity strains. Significant interconnectedness could affect public markets, as insurance companies and pension funds may be forced to sell more liquid assets.
The cumulative effect of these links may have significant economic implications should stress in private credit markets result in a pullback from lending to companies. Severe data gaps make monitoring these vulnerabilities across financial markets and institutions more difficult and may delay proper risk assessment by policymakers and investors.
Policy implications
It is imperative to adopt a more vigilant regulatory and supervisory posture to monitor and assess risks in this market.
Authorities should consider a more active supervisory and regulatory approach to private credit, focusing on monitoring and risk management, leverage, interconnectedness, and concentration of exposures.
Authorities should enhance cooperation across industries and national borders to address data gaps and make risk assessments more consistent across financial sectors.
Regulators should improve reporting standards and data collection to better monitor private credit’s growth and its implications for financial stability.
Securities regulators should pay close attention to liquidity and conduct risk in private credit funds, especially retail, that may face higher redemption risks. Regulators should implement recommendations on product design and liquidity management from the Financial Stability Board and the International Organization of Securities Commissions.
—This blog is based on Chapter 2 of the April 2024 Global Financial Stability Report: “The Rise and Risks of Private Credit.”
Compliments of the IMF.The post IMF | Fast-Growing $2 Trillion Private Credit Market Warrants Closer Watch first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.