Read More
EACC

IMF | Monetary Policy with Supply Shocks and High Debt

Remarks by Kristalina Georgieva, IMF Managing Director at the Bank for International Settlement
Dear Fabio, dear Pablo, dear governors—thank you for inviting me here to share a few thoughts on the challenges faced by central banks as our stewards of monetary policy.
Over the past 20 years, we have seen the Great Moderation give way to the global financial crisis, followed by a long spell at the effective lower bound, followed by a succession of large shocks, from the pandemic to the war in the Middle East.
And we have seen the unstoppable march of technology, not at an even tempo but, as ever, in discrete jumps—from robotics to stablecoins to AI bots trading 24/7.
Each recent shock has had profound implications for fiscal and monetary policy, making policymaking harder, touching all three core central banking tasks: price stability, financial stability, and payment systems.
Today I will focus on what in many jurisdictions is top of mind for businesses and the general public—price stability—addressing three points: first, demand management in the face of the energy shock; second, what AI means for monetary policy; and third, the pressure on long-term interest rates arising from market concerns about the mix of stubborn inflation and high public debt.
Let me start with the Strait of Hormuz, noting upfront that—rather unusually for me—I am less optimistic than consensus on the size and duration of the supply shock its effective closure has caused.
It is true that six months into the war the global economy has not fallen off a cliff. Oil did not reach $150 per barrel and, despite inflated fuel prices and hardships in several Gulf countries, we remain on track for world growth of about 3 percent this year.
To explain this resilience, let me recognize a few of the countries represented in this forum, without trying to be comprehensive: Saudi Arabia and the UAE for rerouting oil around Hormuz; the U.S. and Norway for ramping up oil and gas exports; China for curtailing its oil imports; Nigeria and India for their refining; and all International Energy Agency members for their coordinated reserve releases.
These steps and others, including gas-to-coal switching in some countries, diversification away from hydrocarbons in many, and demand reduction in all, have helped us get through this shock—so far.
But, to quote the Game of Thrones, winter is coming. Oil, gas, and petroleum product prices remain high—just last Friday, U.S. diesel prices broke a new record. Shipping through Hormuz is at about one-tenth of its pre-war level. Reserve drawdowns will hit their limits. Depleted reserves will need restocking. And now we have AI as the thousand-pound gorilla in the room, with its voracious appetite for energy.
As central bankers, you are in the business of demand management. One key question you confront is how restrictive should policy be if the energy outlook were to worsen? The answer depends on your assessment of the risk that a price-level shift could trigger second-round effects and a broader inflation process.
To make that assessment, you look to the data: output and capacity utilization; job market indicators; financial conditions; underlying inflation and inflation expectations; and much more. And, despite all the data, we know that reading the tea leaves remains as much art as science.
At the IMF, our reading is not only that the price-level shift is less extreme than in the gas supply shock experienced by Europe in 2022, but also that there may have been more slack going in, which would limit the risk of the shock propagating.
But again, let me share my worry that this global ordeal may be far from over.
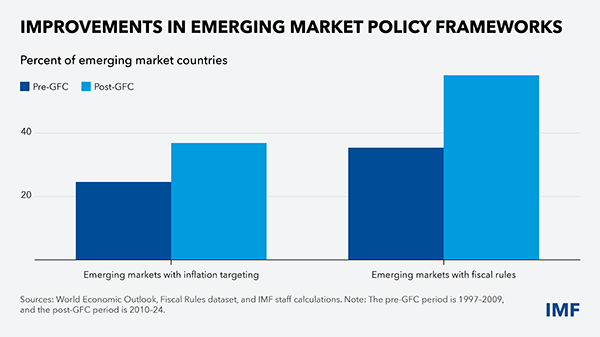
With that in mind, it is comforting to have watched many emerging markets come of age in recent years in terms of central bank independence and the sophistication of their policy frameworks. Here, in my first slide of two, we see this progress.

Next, let me turn to AI and what it means for monetary policy—as a positive demand shock today and a positive supply shock tomorrow, rolled into one.
So, here is my hypothesis: that AI is likely to add to inflation pressures in the short run while its longer-run effects are unclear—views are split on whether it may be deflationary or not.
With large upfront investment in AI infrastructure—reversing a decades-long progression toward lower capital and energy intensity—and with rising equity prices boosting household wealth, a positive demand effect likely dominates in the short run—although this could go into reverse if there were to be a major market correction.
But there is also a positive supply effect, with productivity expected to increase over time. As our new chief economist Silvana Tenreyro argues in a recent Bank of England paper titled “Productivity and Inflation Dynamics,” higher productivity boosts both supply and demand, the latter through its effects on real income.
Whether the outcome is inflationary or deflationary depends on the magnitudes of the two effects and their timing. With AI expected to deliver a lasting uplift to productivity growth, Silvana’s logic suggests it will also raise expected permanent real income, which could lift demand in advance of expanding supply, pushing up the neutral interest rate, r*, and inflation—the leads and lags are crucial.
Ken Rogoff goes a step further, injecting into the argument the demand effects of a changing income distribution. His logic is that if AI hollows out the middle of the job market—which our own research also flags as a risk—and if AI retains its winner-takes-all dynamic, the boost to demand could be muted, possibly to a point where the positive supply effect dominates.
For now, we can safely conclude that the question of whether the recent bout of high inflation would be followed by a return to ultra-low inflation and interest rates has been answered. In the short run, no.
And as for the longer run, yes, there is a possibility that—through the expected uplift in productivity—AI could reduce costs and be deflationary. But in how long is this long run? And how confident are we that we will get the right combination of productivity gains and demand responses?
And one last thought on AI, more for the fiscal authorities than for central bankers: if AI is going to hollow out the middle of the job market, we had better start considering the future of personal income taxation.
That last concern takes me from the gorilla to the elephant in the room: public debt.
The recent years have been defined by vast shocks—with the pandemic in particular necessitating unprecedentedly large fiscal support to households and firms, notably in advanced economies, followed by further rounds of fiscal support during the cost-of-living crisis, especially in Europe.
Regrettably, in far too many countries, post-crisis recovery has not been paired with consolidation. The result is what I call the “stairway-not-to-heaven”: big upward jumps in debt when shocks strike, little or no reduction afterward. Rinse and repeat.
Even after the recent inflation surprise helped lower some debt ratios, the crisis legacy remains a global public debt burden that is at its heaviest since World War II—and on track to exceed 100 percent of GDP within the decade—with many of the highest ratios seen in advanced economies.
At the same time, inflation remains stubborn. In U.S. for instance, inflation has been above target for 5½ years—and we at the IMF have pushed back in our projections the date when we expect it to return to target by no less than two years. In the U.S. and elsewhere, markets judge the recent rate-cutting cycles to be over.
Today, most major advanced economies have public debt paths that call for fiscal policy attention. All of us are aware that U.S., French, and Japanese 10‑year sovereign yields, to highlight just three, are currently at their highest levels since 2007, 2008, and 1996, respectively.
And as these benchmark borrowing costs rise, they lift most of the world’s yield curves up with them—in some emerging markets this more than fully offsets hard-won spread compression.
Core yields are climbing despite central bank bondholdings that keep material amounts of debt and duration off market. Today, even after significant shrinkage, the Bank of Japan still owns 34 percent of own-government debt, the Eurosystem 20 percent, and the Fed 11 percent—as shown here, in my second slide.

Many governments now face high and rising debt-service burdens. Heavy reliance on short-term bills increases gross financing needs—to close to 40 percent of GDP in the U.S. Treasury’s case. This amplifies sensitivity to policy rates and raises the cost of falling behind the curve, failing to control inflation, and then having to double down with higher rates.
It is worrisome that fiscal consolidation seems not to have received the attention it deserves. In Japan, the government has ambitious budget plans to lift potential growth and ease the pain of rising prices. In Europe, significant spending is being accommodated by escape clauses in the fiscal rules. In the U.S., the debt path draws insufficient Congressional attention.
With rising bond yields, the difference between real interest rates and real growth, r – g, is now less supportive than before. For growth to painlessly solve the fiscal problem, large and sustained increases would be needed.
These are the reasons why I chose to use my recent remarks at Jackson Hole to warn about the risk of fiscal dominance. When public debt is high, history has taught us that fears of lower-than-optimal policy rates or future monetization may lurk in the background, pushing bond yields and inflation expectations upward. And, with many central banks now making losses from a mix of low yields on legacy assets and high interest expenses on bank reserves, the challenge for central banks is even greater.
With high debt and fears of fiscal dominance conspiring to increase the risk of inflation expectations moving upward, central banks will need to respond forcefully to future shocks to protect independence, preserve credibility, and deliver on their price stability mandate.
At the Fund, we take very seriously our duty to call out the fiscal risks and create traction for consolidation—this is the underlying problem that needs to be solved. Our annual Article IV consultations with the systemic economies have consistently flagged the fiscal issue and will continue to do so.
But until such time as credible medium-term fiscal plans are put in place, it is important to stand firm with a rock-solid commitment to that most critical purpose of central banking: to ensure inflation is low and stable.
Let me close by proposing for discussion five core features for monetary policy success in these unsettled times:

First, vigilance. When shocks interact, our models may lose some predictive power, calling for especially thorough scrutiny of the data.
Second, agility. Conditions change, and what works in one state of the world may not work in another, so policies must stand ready to pivot and adapt.
Third, communication. Markets need basic guidance on how central banks think, but equally central banks must take care to guard their policy optionality.
Fourth, credibility. The framework that underpins credibility—central bank independence and a clear nominal anchor—must be protected, and keeping inflation anchored when public debt is high may dictate a hawkish bias.
Fifth, humility. This, last but by no means least, is a key ingredient given the speed and magnitude of the changes that central banks confront today, requiring the ability to correct course with no remorse.

Having these five points in mind may come in handy, especially in tough times—times like, for instance, when you are called upon to distinguish between market discipline from orderly increases in bond yields and sudden spikes indicative of vigilantes and malfunction—situations that can necessitate decisive liquidity provision.
Thank you.
 
 
Compliments of the International Monetary Fund The post IMF | Monetary Policy with Supply Shocks and High Debt first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

European Commission | The EU’s Plan to Grow Innovation in Europe

Europe has plenty of world-class research, talent and creativity. However, too often ideas originating in Europe are turned into economic success by others, elsewhere. This is because European innovators face barriers here and find it difficult to bring their ideas to life. As a result, the Commission proposed a new European innovation act to help Europe’s most innovative ideas be developed, financed and scaled up in Europe.
To strengthen the EU innovation system, the proposal will address two main challenges. Firstly, it will help innovative companies access financing by

promoting a common EU framework to value intellectual property
creating a digital marketplace connecting buyers and sellers of intellectual property
offering expert support to help companies bring their ideas to the market

This can unlock €10.2 billion per year in additional financing and generate around €35 million in administrative cost savings.
Second, it will establish a common approach for research and development procurement that

will provide greater legal certainty
help new technologies reach the market faster
make it easier for public buyers from different EU countries to jointly carry out Research and Development procurements.

With this, companies could expect €25.92 billion in additional annual profits, while public buyers could save €1 billion per year.
The European innovation act is an element of the competitiveness compass, to strengthen the EU’s long-term competitiveness, prosperity and technological sovereignty. In parallel, the Commission will help innovators accelerate the transformation of innovative ideas into market solutions through a specific proposal on regulatory sandboxes.
 
 
Compliments of the European Commission The post European Commission | The EU’s Plan to Grow Innovation in Europe first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

IMF | A World Seeking Balance

Surpluses and deficits reflect deeper choices about saving and investment across interconnected economies.
More than 80 years ago, John Maynard Keynes centered his work on the persistence of global imbalances. The great economist tried to resolve what he described as the “secular international problem” at the Bretton Woods conference in 1944 through an international clearinghouse. But the conference’s final agreement included only a weaker set of remedies.
Concern about imbalances has waxed and waned in the decades since, but has returned to the forefront of the policy debate in recent years. Global imbalances widened again in 2025, reversing steady narrowing during the decade after the global financial crisis and reviving difficult questions about their sustainability.
Keynes’s point was simple but profound: In a world of interconnected economies, countries cannot save, spend, or borrow independently. Imagine a small neighborhood. One household saves almost everything it earns. Another spends more than it earns and borrows to make up the difference. For a time, the arrangement works. The thrifty household finds a reliable borrower and earns a return while the spendthrift household enjoys a comfortable lifestyle. But as debts accumulate and positions become entrenched, what began as a mutually convenient arrangement can become fragile and fuel tensions.
Global imbalances are this story’s international version and refer to the pattern of surpluses and deficits across countries. Every country keeps a ledger with the rest of the world, called the current account. This records the value of the goods and services it sells and buys abroad as well as income flows associated with foreign transactions. When a country sells more than it buys, it runs a surplus and lends to the rest of the world. When it buys more than it sells, it has to borrow from other countries and run a deficit.
Saving and investment
At its core, a current account balance reflects a simple idea: the difference between what a country saves and what it spends. This is more than a simple accounting identity; it reflects the complex forward-looking choices of economic agents. For instance, households consume and firms invest when they expect higher income in the future or face temporary shortfalls. They save when their income exceeds their desired consumption, when investment opportunities are limited, or when they worry the economy might weaken and want to put money aside.
Exchange rates play a role, too, but it is often misunderstood. A country’s currency tends to rise or fall to keep trade broadly in line with the saving and investment balance. Exchange rates, in other words, tend to reflect current account positions rather than drive them.
Seen this way, global imbalances are not primarily about trade competitiveness. They reflect structural differences in the pattern of domestic saving and investment across countries—driven, for example, by demographics, growth prospects, financial development, and policy frameworks.
The recent increase in imbalances reflects mostly developments in the world’s two largest economies. A slump in China’s property market five years ago depressed domestic investment as construction of new homes stalled; households responded by slashing spending and saving more. In the United States, meanwhile, the government’s large fiscal deficit—coupled with robust consumer spending—has depleted national savings.
Cause for concern
Not all deficits or surpluses are a problem. They can be a natural and even desirable outcome of efficient resource allocation, if capital flows to younger fast-growing developing economies from aging advanced economies, for example. The concern arises when imbalances become excessive and are rooted in persistent distortions that pose serious risks to global economic and financial stability.
The longer deficit countries rely on external borrowing, the more vulnerable it leaves them to sharp changes in global financial conditions. If investors lose confidence or financing becomes more expensive, capital inflows can reverse suddenly. The result is often currency depreciation, financial stress, and economic recession, as occurred in Mexico in the early 1990s and East Asia later that decade.
Surplus countries do not face the same risks of correction, but their policies can have consequences for other countries that build gradually over time. When surpluses reflect weak domestic demand, underdeveloped financial systems, or policies that encourage saving, it may indicate that a country is using its resources inefficiently. Excess savings from surplus countries channeled abroad put downward pressure on global interest rates and prices.
Where surpluses stem from policies intended to strengthen export competitiveness, the disinflationary effects of cheaper exports can help trading partners struggling with high inflation—but they weigh on partners already facing weak demand, or those whose industries compete head‑to‑head with those of the surplus economy, dragging down their economic growth.
Financial markets can punish countries that run persistent deficits and correct their imbalances—by driving down the value of their currencies and driving up their borrowing costs—but countries with persistent surpluses face no comparable disciplining market forces.
At the global level, imbalances can amplify financial cycles. Large capital flows fuel credit booms and inflate asset prices in deficit countries. Surplus countries accumulate large foreign asset positions that are sensitive to exchange rates and interest rates. These dynamics can make the system more fragile.
Action on both sides
Left unchecked, global imbalances can also fuel geopolitical tensions. Factory closures, job losses, and other dislocations in communities or industries exposed to surging imports can fuel the perception that the playing field is unfair, strengthening support for trade tariffs and other protectionist measures.
So how should the world manage persistent imbalances? Countries may be tempted to reach for unilateral trade protection as a shortcut to rebalancing. But higher tariffs and other trade barriers generally have weak and unreliable effects on external balances because they do little to alter the underlying saving and investment drivers. The protectionist measures can instead trigger tit-for-tat reactions that can further disrupt the global economy.
A more balanced outcome requires action on both sides. Adjustment is never a one-country story. After all, one country’s deficit is another’s surplus, and changes in one economy’s saving and investment patterns affect outcomes elsewhere.
Deficit countries need to strengthen saving and ensure that borrowing supports productive investment. Surplus countries need to boost domestic demand or reduce excess saving. When these adjustments take place together, imbalances can narrow in a way that supports global growth.
A balanced approach like this would facilitate orderly adjustment: Saving and investment shift gradually, supported by policy changes and stable financial conditions; exchange rates adjust; domestic demand rebalances; and external gaps narrow without major disruption. In fact, policy-led reforms to fix domestic distortions could yield a double dividend, boosting growth at home and curbing imbalances abroad.
The alternative is disorderly adjustment, driven by sudden shifts in market sentiment or financial conditions. A reversal of capital flows would force a rapid correction of deficits, a sharp contraction in output, and potentially a serious financial crisis with a material loss of global output.
Everyday decisions
Global imbalances are not the result of mysterious forces. They are an outcome of everyday economic decisions—how much to save, how much to invest, and how to plan for the future. They reflect the fact that countries, like households, do not always spend exactly what they earn.
At their best, imbalances allow countries to share risk, smooth consumption, and allocate capital efficiently across borders. At their worst, they reflect domestic distortions, create vulnerabilities, and risk a costly reckoning. The thrifty household and the borrowing neighbor will eventually have to renegotiate their arrangement. The question is whether they can do so without creating a crisis that neither wanted.
That is the enduring challenge at the heart of the global economy—and the reason Keynes’s “secular international problem” remains with us today.
 
 
Compliments of the International Monetary Fund The post IMF | A World Seeking Balance first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC & Member News

AKD: Applicability of the NIS2: A Practical Guide for the Netherlands

In our previous blog post, we introduced the NIS2 Directive (Directive (EU) 2022/2555) as the EU’s landmark legislation for strengthening cybersecurity across Europe. We outlined its key features, the differences from NIS1, and provided an overview of the transposition progress in Belgium, the Netherlands, and Luxembourg. Since then, all three Benelux countries have completed their transposition with the Netherlands being most recent; the Dutch Cybersecurity Act (Cyberbeveiligingswet, “Cbw”) entered into force on 15 August 2026. Belgium and Luxembourg transposed the NIS2 Directive earlier, through the Belgium NIS2 law of 26 April 2024 (in force since 18 October 2024) and the Luxembourg NIS2 law of 5 May 2026 (in force since 10 May 2026).

Read more

EACC & Member News

Ebury: Blowout Jobs Report Keeps September Fed Hike in Play

Yet neither the Jackson Hole symposium nor the payrolls data have brought real clarity, with a hike still very much a coin-toss heading into Friday’s CPI print. The Fed’s announcement will be just one of a slew of critical central bank decisions this month, all landing against the backdrop of an increasingly nervous bond market, where sovereign yields keep hitting multi-decade highs and investors’ patience for policymakers who miss their inflation targets year after year is wearing thin.

Read more

EACC

European Commission | Gas Coordination Group: No Immediate Security of Supply Risk

Despite lower gas storage levels compared to previous years, the Member States and the Commission consider there is no immediate risk for security of gas supply in the EU. In a meeting of the Gas Coordination Group (GCG) this afternoon, experts from the Commission and Member States confirmed that while the situation on global energy markets remains exceptional and requires close monitoring, it also differs significantly from that of 2021/2022. Today, the EU is better prepared, thanks to increased diversification, higher LNG import capacity, and reduced gas demand.
Based on historical projections, the EU is on track to achieve an adequate level of winter preparedness. Under the current circumstances, the Commission sees no reason to intervene. The EU gas system is resilient enough to cope with lower storage levels for the upcoming winter.
Overall, the situation in the Middle East remains unstable and Qatari LNG production is still shut down. More recently, heatwaves in Europe have driven up gas demand for power generation. Geopolitical uncertainty continues to drive significant price volatility. The Commission will keep monitoring the situation very closely in cooperation with Member States and stakeholders. A further meeting of the Gas Coordination Group is scheduled for 24 September.
 
 
Compliments of the European Commission’s Directorate-General for EnergyThe post European Commission | Gas Coordination Group: No Immediate Security of Supply Risk first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

ECB | Big Tech, Big Debt: When US Tech Giants Tap the Euro Area Bond Market

Blog | US tech giants are increasingly tapping the euro area bond market to fund their investments. The ECB Blog investigates the consequences for this market and the potential for these developments to reshape it.

The infrastructure for artificial intelligence (AI) requires huge investments. Think of the gigantic data centres and the massive electricity consumption to power them. US tech giants, including Google, Amazon and Microsoft, operate massive cloud and AI infrastructure. That is why these companies, known as hyperscalers[1], are tapping into all corners of global financial markets to fund their expansion. And increasingly they are turning to the euro area corporate bond market for some of that funding.
The growing presence of hyperscalers in the euro area corporate bond market has several consequences. For one, it could increase concentration and raise investor exposure to the technology sector and the US economy, similar to trends already felt in equity markets, where hyperscalers have become dominant. Furthermore, the surge in big tech borrowing could make it harder for other companies and other economic sectors to access finance by reshaping investors’ asset allocations. It also raises a key market-functioning question: can euro area financial markets smoothly handle such large and concentrated debt inflows?
The AI investment boom has reached euro area credit markets
Hyperscalers are projected to need more than USD 1 trillion for capital expenditure in total by 2028.[2] That equals a stunning 3% of current annual US GDP. Planned investments are becoming too large to be financed solely through internally generated cash flows. Consequently, big tech companies are shifting away from self-funding towards external sources of finance, including bond issuance.
First, hyperscalers tapped the US dollar corporate bond market and then increasingly other credit markets, not least in the euro area. This is not an unusual strategy in finance. Funding in global credit markets is the bread and butter of global firms, which have an incentive to move beyond their domestic credit market for several reasons. They may be seeking to lower their borrowing costs,[3] diversify funding sources, broaden their investor base or match expenditures in foreign currencies. Big European companies with global activities do this as well.
The large funding needs of US hyperscalers led them to follow this playbook and increase their reliance on “reverse Yankees” (bonds issued by US firms in foreign currency). In their first big wave of issuance outside the United States, hyperscalers picked the euro as the most beneficial currency for foreign funding. The euro accounts for close to 10% of the outstanding stock of bonds issued by these firms.
What volumes are we talking about? These issuers currently account for slightly over 1% of benchmark indices for euro-denominated corporate bonds, with around €40 billion of bonds outstanding. Their share in euro-denominated “reverse Yankee”issuance almost doubled between 2025 and 2026.[4] US big tech companies now represent just shy of 10% of the gross new issuance of euro-denominated bond debt attributable to non-financial corporations (Chart 1, panel a). This year alone, Amazon and Alphabet have been the largest issuers in the euro area non-financial corporate bond market, with the Amazon transaction setting an all-time size record.

Chart 1
Big tech’s rising weight in the euro area corporate bond market

Sources: Dealogic, Bloomberg Finance L.P. and ECB calculations.
Notes: Only euro-denominated tranches issued by non-financial corporations identified using Dealogic data. Excluding private placements and convertible bonds.
Panel a: The share of issuance is the share in total euro-denominated investment-grade issuance by financial and non-financial corporations. The share of outstanding is the share in the ICE-BofA euro investment-grade corporate index. The latest observations are for 20 August 2026.
Panel b: QE stands for quantitative easing, and here specifically to the period during which the Eurosystem bought corporate securities under its corporate sector purchase programme (CSPP) and/or under Pandemic Emergency Purchase Programme (PEPP). The latest observations are for 20 August 2026.

The arrival of US big tech is shaking up old beliefs in the euro area credit market. In an economy known for being historically bank-based, euro area corporate bond markets were often perceived by issuers and investors as not having the breadth and depth to support large issuances. During the period of quantitative easing when central banks bought sovereign and corporate bonds, this started to gradually change. The euro area corporate bond market broadened its network of issuers and became a more reliable stage for funding larger investment needs.[5] Issuance of this scale signals that the euro area can absorb very large corporate bond deals on its own (Chart 1, panel b).
US big tech can broaden euro area corporate bond markets
Hyperscalers are expanding the scope of the euro area corporate bond market by introducing longer maturities, greater exposure to the technology sector and higher-rated debt. First, US big tech issues significantly longer-dated maturities than other economic sectors do. This helps build the long end of the yield curve (Chart 2, panel a), which domestic corporate issuers use less often. Second, the growing presence of hyperscalers in primary markets – and their inclusion in benchmark indices – gives bond investors greater exposure to the technology sector. This is particularly relevant in Europe. The weight of the technology sector in euro area benchmarks remains around three times lower than in comparable US indices.
Finally, hyperscalers have brought higher-rated debt to the euro area corporate bond market (Chart 2, panel b). With the current wave of debt issuance still in its early stages, these firms exhibit strong balance sheets, which translate into favourable assessments by credit rating agencies (e.g. often AA- or higher). This range complements the euro area landscape where most corporate issuers fall in the A to BBB class. As AI is a new sector, however, the way rating agencies approach this sector may be based on assumptions on future revenue growth and leverage which may not stand the test of time, heightening the vulnerability to mispricing of credit risk.

Chart 2
How the US tech sector is diversifying the euro-denominated corporate bond market

Sources: Bloomberg Finance L.P. and ECB calculations.
Notes: Panel a: Distribution of outstanding amount of debt for hyperscalers, as well as for euro area and non-hyperscaler US constituents of the Bloomberg EUR IG credit index within the technology sector, as of 20 August 2026. Panel b: Distribution of outstanding amount of debt for US and euro area constituents of the Bloomberg EUR IG credit index by rating, as of 20 August 2026. Issuers are grouped by country of incorporation of the ultimate parent. The y-axis shows which percentage of the overall debt issued by a specific category of issuer falls in the different maturity buckets. Issuers are grouped by the region of the country of incorporation.

Is there a risk of crowding-out?
Investors active in investment-grade corporate bonds denominated in euro are playing a prominent role in the financing of US hyperscalers’ capital expenditures. But does this mean that there is substantially less interest in bonds issued by euro area companies? Data analysis and market intelligence suggest that this has not been the case during this first issuance wave and that adaptation has helped.
Investors continued to show strong demand for euro-denominated hyperscaler bonds until mid-2026. Support subsequently weakened, and cover ratios − a measure of investor demand relative to the supply of a new bond − started to edge down. But this likely reflected a normalisation, as investors re-evaluated their risk compensation in light of the prospect for continuous flows of long-maturity issuance. By contrast, cover ratios for euro area issuers have remained strong and little changed throughout 2026. Some European issuers reportedly timed their issuance to avoid days when hyperscalers tapped the market, supposedly with a view to avoiding direct competition and preserving investor demand.
Investors also started to adapt, demanding greater compensation for the risks associated with hyperscaler debt. Hyperscalers’ credit spreads have started to increase on news of higher expected AI-related capital expenditure and more issuance announcements. Across all maturity segments, investors are demanding a rising risk premium to absorb the supply and deal with the greater uncertainty over the medium-term earnings outlook (Chart 3).[6]

Chart 3
Hyperscaler euro spreads edge up even as spreads of other issuers remain stable

Average credit spread of hyperscaler euro-denominated bonds across maturities and range between average spread of AA- and BBB-rated corporate issuers excluding hyperscalers
basis points

Sources: Bloomberg Finance L.P. and ECB calculations.
Notes: Asset swap spreads of corporate bond issuers for constituents of the Bloomberg EUR IG corporate index excluding financials. The shaded area represents the range between the index-weighted average spread of AA-rated and BBB-rated issuers, excluding hyperscalers. The curve reflects the index-weighted average of credit spreads of Alphabet, Amazon, and Microsoft, which are AA- and AAA-rated. The vertical dashed lines mark the announcement dates of Amazon Alphabet and Amazon euro-denominated issuance. The latest observations are for 20 August 2026.

Despite this reassuring initial assessment, US big tech companies could push up borrowing costs for all sectors as they accumulate debt and account for a growing share of bond markets, with a potential spillover to the sovereign and supranational segment of the bond market. This would depend in part on whether the investor “pie” is fixed, with big tech taking a larger slice, or whether it can expand to absorb the additional issuance. Spillover effects could happen through three main channels.
First, supply matters. The scale of big tech supply of new bonds may strain investor appetite. That could force hyperscalers − and similarly rated peers − to offer bonds at lower prices with wider yield spreads. The expectation of even greater bond supply in the future amplifies this effect, because investors might be reluctant to accept a current spread level if they expect even higher spreads in the future.
Second, investors have finite balance sheets and portfolio limits. They may reduce holdings of other bonds to make room for large hyperscaler deals. That could create a crowding-out effect that raises costs even for issuers from unrelated industries. Euro area investor exposure to hyperscaler debt remains relatively small for now, but is growing rapidly. Hyperscalers accounted for 15% of the increase in domestic euro-denominated corporate bond holdings in the year to March 2026, with strong demand from pension funds and insurers. For these investors looking for high-quality, long-maturity assets, hyperscaler debt may look like a possible alternative to some safe-haven style securities.
Third, bond index mechanics can amplify the effect. As hyperscalers gain weight in bond indices, passive, benchmark-tracking investors may mechanically rebalance towards them, intensifying the pressure on other bonds and further influencing spreads.
Conclusion
The rising presence of hyperscalers can bring diversification and growth to the euro area corporate bond market. For the time being, spillovers to other corporate issuers’ access to market-based funding remain limited, and the impact on investor portfolios is not substantial. In the United States, AI-driven demand for long-dated funding has reportedly contributed to the recent rise in long-term real yields. No such spillovers are evident in the euro area so far, reflecting smaller big tech issuance and resilient sovereign bond markets.
However, this could be merely the start of a financing wave of unprecedented proportions which could demonstrably reshape bond markets, including in the euro area, prompting issuers, intermediaries and investors to adapt.
While the dynamics of this adaptation are uncertain, the sheer scale of hyperscalers’ future borrowing needs, coupled with expectations of sustained strong yet uncertain earnings, warrants close monitoring. Potential international spillovers, fast-rising leverage (especially if other, less transparent, debt markets start being tapped) and broader implications for the functioning of euro area financial markets all demand close attention.
The views expressed in each blog entry are those of the author(s) and do not necessarily represent the views of the European Central Bank and the Eurosystem.

Hyperscalers are cloud providers that manage extensive networks of data centres, elastically delivering infrastructure, platform, and software services at a very large scale. In this blog, the term “hyperscalers” refers to five US tech companies: Alphabet, Amazon, Meta Platforms, Microsoft and Oracle.

Lower bound of credit analysts’ estimates.

For more details, see Domenech Palacios, M., Jančoková, M. and Tomov, T. (2025), “Reverse Yankee bonds”, The international role of the euro, ECB, June.

For more on euro-denominated bond issuance in 2025, see Section 1.3 in “The international role of the euro”, ECB, June 2026.

See Arce, Ó., Mayordomo, S. and Gimeno, R. (2021), “Making Room for the Needy: The Credit-Reallocation Effects of the ECB’s Corporate QE”, Review of Finance, Vol. 25, Issue 1, February, pp. 43-84, and Darmouni, O. and Papoutsi, M. (2022), “Non-bank lending to mid-size firms in Europe: evidence from corporate securities”, Working Paper Series, No 2663, ECB, revised March 2025.

This premium is significantly higher at the long end, but this is influenced by the longer maturity of hyperscaler bonds compared with other firms.


Compliments of the European Central Bank The post ECB | Big Tech, Big Debt: When US Tech Giants Tap the Euro Area Bond Market first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.