EACC

European Commission | Commission Opens Proceedings to Assist Google in Complying With Interoperability and Online Search Data Sharing Obligations Under the Digital Markets Act

Today, the European Commission has started two sets of specification proceedings to assist Google in complying with its obligations under the Digital Markets Act (‘DMA’). The specification proceedings formalise the Commission’s regulatory dialogue with Google on certain areas of its compliance with two DMA obligations.
The first set of proceedings concerns Google’s obligation under Article 6(7) of the DMA to provide third-party developers with free and effective interoperability with hardware and software features controlled by Google’s Android operating system. Today’s proceedings focus on features used by Google’s own Artificial Intelligence (‘AI’) services, such as Gemini. The Commission intends to specify how Google should grant third-party AI service providers equally effective access to the same features as those available to Google’s own services. The aim is to ensure that third-party providers have an equal opportunity to innovate and compete in the rapidly evolving AI landscape on smart mobile devices.
The second set of proceedings concerns Google’s obligation under Article 6(11) of the DMA to grant third-party providers of online search engines access to anonymised ranking, query, click and view data held by Google Search on fair, reasonable and non-discriminatory (‘FRAND’) terms. These proceedings focus on the scope of data, the anonymisation method, the conditions of access, and the eligibility of AI chatbot providers to access the data. Effective compliance and access to a useful dataset will allow third-party providers of online search engines to optimise their services and offer users genuine alternatives to Google Search.
Next steps
The Commission will conclude the proceedings within six months of their opening. Within the upcoming three months the Commission will communicate its preliminary findings to Google setting out the draft measures it intends to impose on Google to effectively comply with the DMA. Non-confidential summaries of preliminary findings and the envisaged measures will be published to enable third parties to provide comments.
These proceedings, which by their nature do not take a position on compliance with the DMA, are without prejudice to the powers of the Commission to adopt a decision finding non-compliance with any of the obligations laid down in the DMA by a gatekeeper, including the possibility to impose fines or periodic penalty payments.
Background
The DMA aims to ensure contestable and fair markets in the digital sector. It regulates gatekeepers, which are large digital platforms that provide an important gateway between business users and consumers, whose position can grant them the power to create a bottleneck in the digital economy.
On 6 September 2023, the European Commission designated Google Inc.’s Google Search, Google Play, Google Maps, YouTube, Google Android operating system, Google Chrome, Google Shopping and its online advertising services as core platform services. Google has had to fully comply with all applicable DMA obligations in respect of the designated services since 7 March 2024.
The Commission has published an annual report on the implementation of the DMA and the progress made towards achieving its objectives.
 
 
Compliments of the European Commission The post European Commission | Commission Opens Proceedings to Assist Google in Complying With Interoperability and Online Search Data Sharing Obligations Under the Digital Markets Act first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.
EACC

European Commission | EU and India Conclude Landmark Free Trade Agreement

The EU and India concluded negotiations today for a historic, ambitious and commercially significant free trade agreement (FTA), the largest such deal ever concluded by either side. It will strengthen economic and political ties between the world’s second and fourth largest economies, at a time of rising geopolitical tensions and global economic challenges, highlighting their joint commitment to economic openness and rules-based trade.
European Commission President, Ursula von der Leyen, said: “The EU and India make history today, deepening the partnership between the world’s biggest democracies. We have created a free trade zone of 2 billion people, with both sides set to gain economically. We have sent a signal to the world that rules-based cooperation still delivers great outcomes. And, best of all, this is only the start – we will build on this success, and grow our relationship to be even stronger.”
The EU and India already trade over €180 billion worth of goods and services per year, supporting close to 800,000 EU jobs. This deal is expected to double EU goods exports to India by 2032 by eliminating or reducing tariffs in value of 96.6% of EU goods exports to India. Overall, the tariff reductions will save around €4 billion per year in duties on European products.
This is the most ambitious trade opening that India has ever granted to a trade partner. It will give a significant competitive advantage for key EU industrial and agri-food sectors, granting companies privileged access to the world’s most populous country of 1.45 billion people and fastest growing large economy, with an annual GDP of €3.4 trillion.
Opportunities for European businesses of all sizes
India will grant the EU tariff reductions that none of its other trading partners have received. For example, tariffs on cars are gradually going down from 110% to as low as 10%, while they will be fully abolished for car parts after five to ten years. Tariffs ranging up to 44% on machinery, 22% on chemicals and 11% on pharmaceuticals will also be mostly eliminated.
A dedicated chapter will also help small EU businesses take full advantage of the new export opportunities. For instance, both sides will put in place dedicated contact points to provide SMEs with relevant information on the FTA and help them with any specific issue they would face when trying to use the FTA’s provisions. In addition to this, SMEs will particularly benefit from the tariff reductions, removal of regulatory barriers, transparency, stability and predictability provided by the Agreement.
Reducing agri-food tariffs
The agreement removes or reduces often prohibitive tariffs (over 36% on average) on EU exports of agri-food products, opening a massive market to European farmers. For example, Indian tariffs on wines will be cut from 150% to 75% at entry into force and eventually to levels as low as 20%, tariffs on olive oil will go down from 45% to 0% over five years, while processed agricultural products such as bread and confectionary will see tariffs of up to 50% eliminated.
Sensitive European agricultural sectors will be fully protected, as products such as beef, chicken meat, rice and sugar are excluded from liberalisation in the agreement. All Indian imports will continue to have to respect the EU’s strict health and food safety rules.
In parallel, the EU and India are currently negotiating a separate agreement on Geographical Indications (GIs), which will help traditional iconic EU farming products sell more in India, by removing unfair competition in the form of imitations.
Privileged access to services markets and protected Intellectual Property
The agreement will grant EU companies privileged access to the Indian services market, including key sectors such as financial services and maritime transport. It has the most ambitious commitments on financial services by India in any trade agreement, going beyond what they have given to other partners.
The agreement provides a high level of protection and enforcement of Intellectual Property (IP) rights, including copyright, trademarks, designs, trade secrets and plant variety rights. It builds upon existing international IP treaties and brings Indian and EU intellectual property laws closer. This will make it easier for EU and Indian businesses that rely on IP to trade and invest in each other’s markets.
Enhancing sustainability commitments
The agreement has a dedicated trade and sustainable development chapter, which enhances environmental protection and addresses climate change, protects workers’ rights, supports women’s empowerment, provides for a platform for dialogue and cooperation on trade related environmental and climate issues and ensures effective implementation.
The EU and India will also sign a Memorandum of Understanding that intends to establish an EU-India platform for cooperation and support on climate action. The platform will be launched in the first half of 2026. Furthermore, subject to the EU’s budgetary and financial rules and procedures, €500 million in EU support over the next two years is envisaged to help India’s efforts to reduce greenhouse gas emissions and accelerate its long-term sustainable industrial transformation.
Next steps
On the EU side, the negotiated draft texts will be published shortly. The texts will go through legal revision and translation into all official EU languages. The Commission will then put forward its proposal to the Council for the signature and conclusion of the agreement. Once adopted by the Council, the EU and India can sign the agreements. Following the signature, the agreement requires the European Parliament’s consent, and the Council’s decision on conclusion for it to enter into force. Once India also ratifies the Agreement, it can enter into force.
Background
The EU and India had first launched negotiations for a free trade agreement in 2007. The talks were suspended in 2013 and then relaunched in 2022. The 14th and last formal negotiating round took place in October 2025, followed by intersessional discussions at technical and political level.
At the same time as FTA negotiations were relaunched, the EU and India also launched negotiations for a Geographical Indications Agreement and an Investment Protection Agreement. Negotiations for these agreements are still ongoing.


Compliments of the European CommissionThe post European Commission | EU and India Conclude Landmark Free Trade Agreement first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.
EACC

European Council | Oral Conclusions Drawn by President António Costa Following the Informal Meeting of the Members of the European Council of 22 January 2026

Oral Conclusions by President António Costa following the Informal meeting of the members of the European Council, 22 January 2026
The European Union and the United States have long been partners and allies. We have built a transatlantic community forged by history, anchored in common values, and dedicated to the prosperity and security of our peoples.
We believe that relationships between partners and allies should be managed in a cordial and respectful way.
Europe and the United States have a shared interest in the security of the Arctic region, notably working through NATO. The European Union will also play a stronger role in this region.
In this context, I want to be very clear: the Kingdom of Denmark and Greenland have the full support of the European Union. Only the Kingdom of Denmark and Greenland can decide on matters concerning Denmark and Greenland.
This is a reflection of our firm commitment to the principles of international law, territorial integrity and national sovereignty, which are essential for Europe and for the international community as a whole. These principles will continue to guide our action.
Against this backdrop, yesterday’s announcement that there will be no new US tariffs on Europe is positive. The imposition of additional tariffs would have been incompatible with the EU-US trade deal. Our focus must now be on moving forward on the implementation of that deal. The goal remains the effective stabilization of the trade relations between the European Union and the US.
At the same time, the European Union will continue to stand up for its interests and will defend itself, its member states, its citizens and its companies, against any form of coercion. It has the power and the tools to do so and will do so if and when necessary.
Looking ahead, we remain ready to continue engaging constructively with the United States on all issues of common interest, including on creating the conditions for a just and lasting peace in Ukraine.
We have serious doubts about a number of elements in the charter of the Board of Peace related to its scope, its governance and its compatibility with the UN Charter.
We are ready to work together with the US on the implementation of the comprehensive Peace Plan for Gaza, with a Board of Peace carrying out its mission as a transitional administration, in accordance with UN Security Council Resolution 2803.
Let me conclude by recalling that the European Union is focused on delivering an ambitious agenda for our citizens: on defense, on competitiveness, on building a more strategically autonomous Europe.
That is why the next Leaders’ meeting, on the 12th of February, will be a strategic brainstorming dedicated to strengthening the Single Market in a new geoeconomic context.

Visit the meeting page

Compliments of the European Council The post European Council | Oral Conclusions Drawn by President António Costa Following the Informal Meeting of the Members of the European Council of 22 January 2026 first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.
EACC

ECB | ECB and ESRB Issue Joint Report Analysing Financial Stability Risks From Geoeconomic Fragmentation

22 January 2026

Geoeconomic fragmentation and geopolitical risk have become key sources of macro-financial uncertainty, which can affect financial stability
Geopolitical shocks can amplify financial stress and dampen economic growth
Report sets out new monitoring framework integrating geopolitical indicators into financial stability analysis

The European Central Bank (ECB) and the European Systemic Risk Board (ESRB) today published a joint report entitled “Financial stability risks from geoeconomic fragmentation” with technical annex, which examines how rising geopolitical risks and heightened uncertainty can affect financial stability in the euro area and across the European Union. The report identifies the key transmission channels through which geopolitical shocks can propagate to the financial system.
The following findings indicate that geopolitical shocks and policy uncertainty tend to lead to tighter financial conditions, financial market stress, increased risk premia and reduced loan growth.

Geopolitical risks and policy uncertainty have risen markedly since the mid‑2010s, with notable increases in 2024 and 2025. At the same time, financial market volatility has remained contained or short-lived.
Estimates suggest that geopolitical risks lower expected growth outcomes, with significant downside tail risks for the real economy, accompanied by heightened financial stress. Geopolitical events can significantly alter the interconnectedness between bonds, commodities, equities and exchange rates.
The impact of geopolitical shocks is heterogeneous across EU Member States, whereby more open economies and those with higher public debt ratios tend to be more vulnerable to amplification effects.
In response to geopolitical shocks, banks and non-banks adjust their balance sheets by reducing lending, especially cross-border exposures. While this reduces the financial system’s exposure to external shocks, it also limits international diversification.

At a time of accelerating geoeconomic fragmentation and persistent geopolitical uncertainty, the ECB and the ESRB stress the importance of enhanced, more harmonised datasets, as well as complementary scenario analyses, for preserving financial stability and increasing economic resilience.[1]The report’s insights can help policymakers and financial institutions to better detect and evaluate geopolitical risks for the financial sector and calibrate macroprudential policy responses.
Notes

The report was prepared by financial stability experts under a joint workstream of the ECB’s Macroprudential Analysis Group and the ESRB’s Analysis Working Group.

Geopolitical risk is an important consideration for European banks and supervisors as they navigate global risks. In view of this, ECB Banking Supervision made geopolitical risk the focus of the adverse scenario in the 2025 stress test of euro area banks (see Box 6) and will assess banks on their geopolitical risk management in the context of the 2026 reverse stress test.


Compliments of the European Central Bank The post ECB | ECB and ESRB Issue Joint Report Analysing Financial Stability Risks From Geoeconomic Fragmentation first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

Read More
EACC

IMF | Global Economy Shakes Off Tariff Shock Amid Tech-Driven Boom

Blog Post by  Tobias Adrian and Pierre-Olivier Gourinchas
Global Economy Shakes Off Tariff Shock Amid Tech-Driven Boomrisks are rising, including from the concentration of tech investment and the negative effects of trade disruptions, which may build over time.
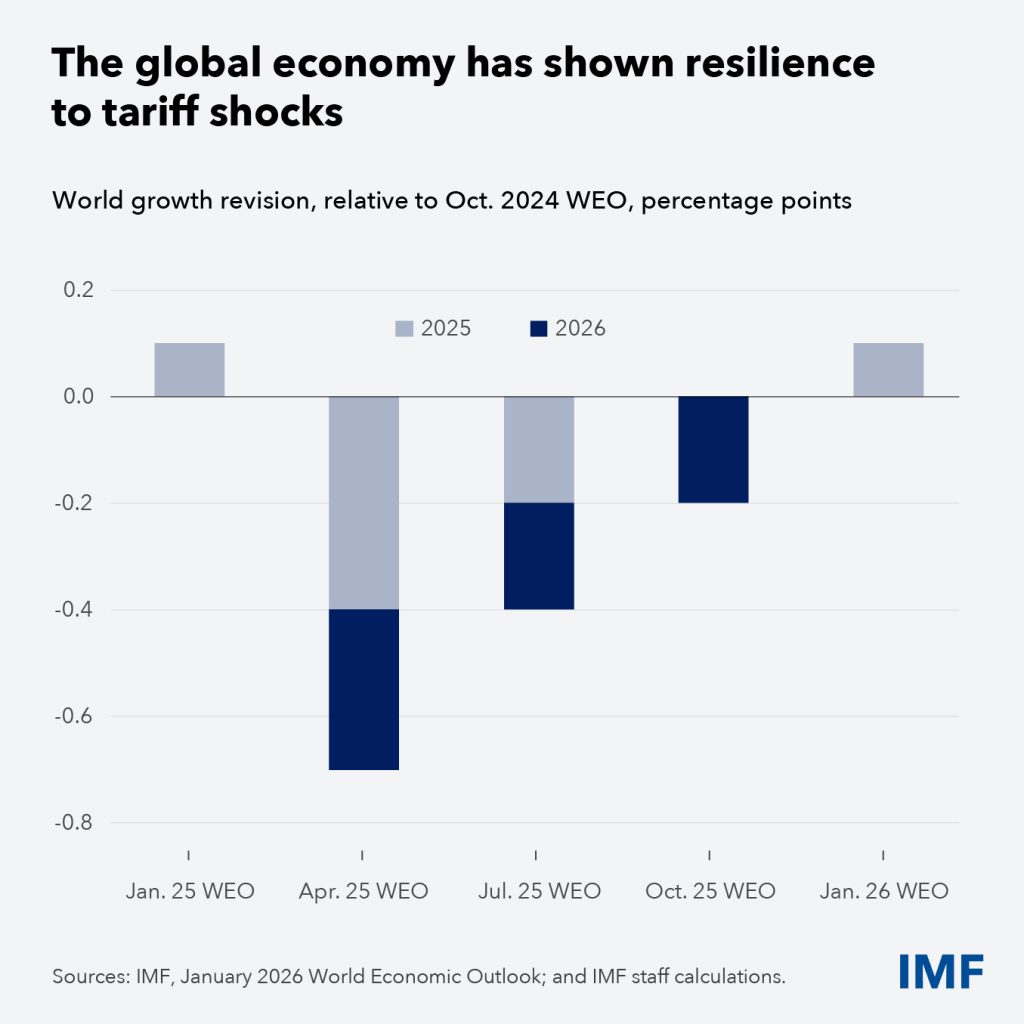
Global economic growth continues to show notable resilience despite significant US-led trade disruptions and heightened uncertainty. Our latest projections indicate that global growth will hold steady at 3.3 percent this year, an upward revision of 0.2 percentage points compared to October estimates, with most of the improvement accounted for by the United States and China. Remarkably, current projections are broadly unchanged from a year earlier, as the global economy shakes off the immediate impact of the tariff shock.

This surprising strength reflects a confluence of factors, including easing trade tensions, higher-than-expected fiscal stimulus, accommodative financial conditions, the agility of the private sector in mitigating trade disruptions and improved policy frameworks especially in emerging market economies.
Another key driver of this resilience is the continued surge in investment in the information technology sector—especially in artificial intelligence. While manufacturing activity remains subdued, IT investment as a share of US economic output has surged to the highest level since 2001, providing a major boost to overall business investment and activity. Although this IT surge has been concentrated in the United States, it is also generating positive spillovers globally, most notably to Asia’s technology exports.

Financial conditions fuel expansion
The IT investment boom reflects businesses and markets’ optimism about the transformative potential of recent tech innovations—in automation and AI—to deliver sizable productivity gains and to lift profits. Since late 2022, coinciding with the introduction of the first widely used generative-AI tools, stock prices have risen sharply.
Favorable financial conditions and robust earnings­­ have supported rising stock prices and helped fund new capital spending. But as the expansion accelerates, debt financing is becoming more prevalent, increasing leverage. This shift introduces notable risks: higher leverage could amplify shocks if returns fail to materialize, or if broader financial conditions tighten, adversely impacting firms and raising concerns about spillovers to the broader financial system.
Moreover, profitability could become sensitive to assumptions around depreciation schedules for advanced processors. Frequent equipment upgrades will squeeze profit margins, weigh on earnings, and require significant additional debt financing. These factors underscore the importance of monitoring leverage accumulation and its potential to amplify vulnerabilities.
Lessons from the dot-com era
The comparison with the dot-com boom of 1995-2000 is instructive. Even though IT investment as a share of gross domestic product is broadly similar to levels then, the recent rise has been more gradual, accelerating markedly only last year. Furthermore, while market valuations relative to economic output have expanded at a similar pace in both episodes, the rise in price-earnings ratios has been more modest in the current boom given more robust earnings.
Overall, our analysis suggests that potential overvaluation for the broad equity index in the United States is only about half that of the dot-com episode. That said, the overall vulnerability of global macroeconomic growth to a repricing of technology stocks may be substantial for three reasons.

First, rising stock prices over the past few years have been driven predominantly by the technology sector, in particular AI-related stocks, and this narrow group has become a major driver of the index. Second, many critical AI-related firms are not currently listed on stock markets. Their debt borrowings could have consequences that were not seen during the dot-com era. Third, market capitalization is now much higher relative to output, from 132 percent in 2001 to 226 percent now for the United States; so even a more modest correction could have a sizable effect on overall consumption.

Risks to the outlook
Looking ahead, the current tech boom raises important upside and downside risks for the global economy. On the upside, AI could start to deliver on its productivity promises, raising US and global activity by 0.3 percent this year, relative to the baseline.
On the downside, AI firms could fail to deliver earnings commensurate with their lofty valuations, and investor sentiment could sour. For reference, a scenario in our October 2025 World Economic Outlook—which included a moderate correction in AI stock valuations with a tightening of financial conditions—reduces global growth by 0.4 percent relative to the baseline. This could have far-reaching consequences if real investment in technology sectors declines more sharply, triggering a costly reallocation of capital and labor. Combined with lower-than-expected total factor productivity gains, and a more significant correction in equity markets, global output losses could increase further, concentrated in tech-heavy regions such as the United States and Asia.
Given the decade-long increase in foreign ownership of US equities, this sharp correction could also trigger sizable wealth losses outside the United States and exert a drag on consumption, spreading the downturn more globally. Even economies that have little exposure to technology, including many high-debt and low-income countries, would be buffeted by negative external demand spillovers and higher external borrowing costs.
Such downside risks arise at a time of heightened geopolitical uncertainty, increased use of export controls on critical inputs and trade-related restraints, and eroded fiscal space in many countries. This could interact with any reassessment of AI-related productivity growth and repricing of risky asset valuations in a self-reinforcing manner.
Policy for stability, discipline, inclusion
With asset valuations stretched, debt financing on the rise, and uncertainty elevated, strong prudential oversight is essential to safeguard financial stability. Supervision and regulation should ensure robust underwriting standards by banks and nonbanks especially those exposed to the technology sector. Internationally agreed standards on bank capital and liquidity should be adhered to. Policymakers must be ready to deploy contingency plans for diverse risks.
Monetary policy faces a delicate balancing act. If the tech boom continues, it may push real neutral interest rates higher—as occurred during the dot-com era—calling for a monetary policy tightening. This would contract fiscal space, especially in countries that do not get a growth boost from AI.
Should the downside scenario materialize, the rapid decline in aggregate demand will call for a speedy reduction in policy rates.
Proper diagnosis and calibration of the monetary policy to achieve price stability requires that central banks operate within their mandate. Central bank independence remains paramount for monetary and financial stability and economic growth, protecting the credibility of monetary policy and anchoring inflation expectations.
On the fiscal side, governments should renew efforts to reduce public debt and restore fiscal space where needed.
AI’s uneven impact on workers is another important consideration. While innovation drives growth, it risks displacing jobs and depressing wages for certain segments of the workforce. Policies should focus on lowering barriers to adoption, helping workers to invest in the right skills, supporting job mobility through targeted programs, and maintaining competitive markets to facilitate entry and ensure that innovation benefits are broadly shared.
Balancing act
Global growth has been impressively resilient amid trade disruptions, but this masks underlying fragilities tied to the concentration of investment in the tech sector. And the negative growth effects of trade disruptions are likely to build up over time.
AI-driven investment offers transformative potential—but also introduces financial and structural risks that demand vigilance. The challenge for policymakers and investors alike is to balance optimism with prudence, ensuring that today’s tech surge translates into sustainable, inclusive growth rather than another boom-bust cycle. This is especially relevant in an environment marked by intensifying geopolitical strains and growing threats to institutional frameworks which make the implementation of good policies more challenging.
 
 
Compliments of the IMFThe post IMF | Global Economy Shakes Off Tariff Shock Amid Tech-Driven Boom first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

European Commission | EU Supports Digital Connectivity with Simpler and Harmonised Rules in Digital Networks Act

The European Commission proposed the Digital Networks Act (DNA) to modernise, simplify and harmonise EU rules on connectivity networks. The current rules must be updated to create the conditions for operators to invest into rolling out advanced fibre and mobile networks. High-capacity networks enable innovative tech, like Artificial Intelligence and Cloud. The widespread availability of advanced connectivity for people and businesses across the EU is the foundation of Europe’s competitiveness.
Strengthening the single market for connectivity
The proposal aims at creating an effective EU single market by harmonising rules and facilitating cross-border business to incentivise operators to scale up, grow and innovate. To enable this, the Digital Networks Act proposal aims to:

facilitate companies to provide services across the EU while having to register in only one Member State;

incentivise the creation of pan-European satellite communication services by establishing an EU-level, as opposed to national level, spectrum authorisation framework;
increase regulatory consistency in national spectrum authorisation, by giving operators longer spectrum licences and by making licences renewable by default to increase predictability;
ensure that all available spectrum is being used by making spectrum sharing among operators more common (‘use it or share it’); and
introduce a voluntary cooperation mechanism between connectivity providers and other players, such as content application and cloud providers.

Transition to advanced connectivity networks
Legacy copper networks do not fit the ambition of making innovative technologies widely available across the EU. The DNA introduces mandatory national transition plans to ensure the phase out of copper networks and the transition to advanced networks between 2030 and 2035. Member States must present their national plans in 2029. The process is accompanied by safeguards to protect all consumers, such as providing clear and timely information about switch-offs and ensuring service continuity.
Simplification and investment
The Digital Networks Act modernises the regulatory framework, reducing administrative burden and reporting obligations, so companies can focus their resources on investment and innovation. The DNA also allows more flexibility for business-to-business relations, while keeping a high level of consumer protection.
Secure and resilient connectivity
The DNA enhances network security and resilience by limiting dependencies in the connectivity ecosystem and promoting EU-level cooperation. The proposal introduces an EU-level Preparedness plan to tackle the rising risks of crises including natural disasters and foreign interference in networks. In addition, the common mechanism for selecting pan-EU satellite communications will incorporate criteria focused on security and resilience.
Protecting net neutrality in innovative services
The DNA fully keeps the principles of net neutrality. It introduces a mechanism to clarify Open Internet rules for innovative services to increase legal certainty and a voluntary ecosystem cooperation mechanism on IP interconnection, traffic efficiency, and other emerging areas.
Next steps
The proposal will be presented to the European Parliament and the Council for approval.
Background
The DNA proposal will replace the 2018 EU Electronic Communications Code.
In February 2024, the Commission’s White Paper “How to master Europe’s digital infrastructure needs?” aimed to explore scenarios and gather insights to shape policy actions for the Union’s digital infrastructure sector.
In her 2025 State of the Union Address, President von der Leyen stressed advancing the Single Market for connectivity by 2028 and encouraged investment in transformative technologies.
 
 
Compliments of the European CommissionThe post European Commission | EU Supports Digital Connectivity with Simpler and Harmonised Rules in Digital Networks Act first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

EUIPO | EUIPO Records the Highest Number of Applications in its History

In 2025, the European Union Intellectual Property Office received 327 735 new applications for EU trade marks and EU designs. It is the highest annual number of intellectual property (IP) applications since the Office began accepting filings in 1996.
Overall, it represents a 7.8% increase compared to 2024, surpassing the previous record set in 2021 (313 928 applications received)
Trade Marks Drive Overall Growth
European Union trade marks (EUTMs) accounted for the largest share of applications in 2025. The EUIPO received 196 886 EUTM applications, an increase of 9.1% compared to 2024.
Applicants based in EU Member States drove this growth, with filings rising by 9.4%. The 27 EU countries together accounted for over 57.5% of all European Union trade marks applications received. Germany (12.7%), Italy (6.9%) and Spain (6.4%) were the most active countries.
Outside of the EU, applications from China also continued to increase, growing by 13.3% (accounting for almost 16% of all EUTMs). The USA (9%) and the UK (4.2%) complete the top three.
Regarding products and services, ‘advertising and business management’, ‘electrical apparatus’ and ‘technological services’ are among the main ones requested. Followed by ‘education and sporting activities’ and ‘clothing and footwear’.
Together, these trends confirm the continued relevance of the EUTM system for businesses operating both within and beyond the European Union.
Design Filings Reach New Highs
Demand for EU designs (EUDs) also increased in 2025. The EUIPO received 130 849 design applications, marking a 6% rise and the second consecutive year of record-breaking figures.
For the first time, applications from outside the EU accounted for the majority of design filings, representing 52% of all EUD applications.
China emerged as the leading source country in 2025, with filings increasing by 18.4% (accounting for 29.9 % of all EUDs applications received), followed by the United Kingdom (+17.8%) and the United States (+8.4%). These figures underline the growing international importance of the EU design system.
Within the EU, filings were led by Germany (13.4%), followed by Italy (10.5%), Poland (4.2%), France (4%) and Spain (3.4%).
New Competence for Craft and Industrial Geographical Indications
In December 2025, the EUIPO began accepting applications for craft and industrial geographical indications (CIGIs), marking a significant expansion of the Office’s mandate.
Within the first weeks of operation, the EUIPO received 45 CIGI applications, with stones and minerals and textiles as the main products represented.
The new system aims to support local value creation and strengthen competitiveness in regions across the European Union.
Looking Ahead
These results provide a strong starting point for the second year of the EUIPO Strategic Plan 2030.
Sustained growth in filings shows that businesses, innovators and creators worldwide continue to invest in protection through the European Union’s IP system.
The record figures recorded in 2025 confirm confidence in the EUIPO and its role in supporting a modern, resilient and inclusive European innovation ecosystem.
 
Click here to explore the charts and figures.
Disclaimer: These figures are provisional and subject to final confirmation.


Compliments of the European Union Intellectual Property Office (EUIPO)The post EUIPO | EUIPO Records the Highest Number of Applications in its History first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

European Council | Artificial Intelligence: Council Paves the Way for the Creation of AI Gigafactories

The Council has adopted today an amendment to the regulation governing the activities of the European High-Performance Computing Joint Undertaking (EuroHPC JU), extending its objectives to facilitate the creation of Artificial Intelligence (AI) gigafactories in Europe and to include a dedicated quantum technologies pillar.
The amended regulation allows for the development and operation of AI gigafactories in Europe, a world-class AI compute infrastructure that will strengthen Europe’s industry and competitiveness, while fostering cooperation through public-private partnerships that include member states and industry stakeholders. It also sets rules for funding and procurement, while safeguarding the interests of start-ups and scale-ups. The amendment provides flexibility for partners, enabling them to optimise results while advancing Europe’s leadership in AI and quantum technologies.

“Today, we’ve taken a bold and swift step towards proceeding with establishing AI gigafactories in Europe. AI is one of the most critical technologies of our time, defining our digital future, and investing in the needed infrastructure capacity for AI is essential for boosting Europe’s resilience, competitiveness, and sovereignty. This move demonstrates our commitment to ensuring that Europe leads in this transformative field.”
Nicodemos Damianou, Cyprus deputy minister of research, innovation and digital policy

Next steps
Following the Council’s approval, the legislative act has been adopted. The regulation will be published in the Official Journal of the European Union on 19th of January and will enter into force on the following day.
Background
EuroHPC aims to develop, deploy, and maintain supercomputing, quantum computing, and data infrastructure in the EU, while also supporting the growth of high performing computing (HPC) systems, technologies, and skills for European science and industry. The EuroHPC regulation was amended in 2024 to include the development and operation of AI Factories —dynamic ecosystems that promote innovation and collaboration in artificial intelligence. The Commission’s proposed second amendment, introduced on 15 July 2025, builds on this by supporting the establishment of AI gigafactories, further advancing Europe’s leadership in AI innovation.


Compliments of the European CouncilThe post European Council | Artificial Intelligence: Council Paves the Way for the Creation of AI Gigafactories first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

ECB | Monetary Policy and Financial Stability in the Euro Area

Speech by Luis de Guindos, Vice-President of the ECB, at the 16th edition of Spain Investors Day

Madrid, 14 January 2026
The global economy is facing a period of profound transformation and heightened uncertainty. The past year has brought major shifts in the international economic environment, driven by significant changes in US policy and the erosion of the multilateral, rules-based system which has long supported global trade and international relations. The introduction of substantial tariffs on US imports has disrupted trade flows, weakened confidence and created ripple effects across economies. Geopolitical risks remain elevated. The shift to a new paradigm – one where rule of law principles are challenged – reflects profound global uncertainties that are likely to persist.
These developments have had tangible implications for economic activity and financial stability in the euro area. Heightened uncertainty weighs on growth prospects through two main channels: by delaying firms’ investment decisions and so affecting euro area exports, and by prompting households to increase precautionary savings and consume less than expected. At the same time, fiscal policy in several euro area countries is set to ease to accommodate higher spending, including for military and security purposes. In this environment, disrupted trade patterns can further complicate inflation dynamics. Financial stability risks remain elevated as valuations are stretched in increasingly concentrated asset markets, non-banks exhibit liquidity and leverage vulnerabilities and increasing interlinkages with banks, while growing private markets remain opaque.
Euro area Monetary Policy
Inflation remains in a good place: having hovered within a narrow range since the spring, it stood at 2.0% in December. Energy prices were lower than a year ago, while core inflation, which excludes energy and food, also fell slightly. Strong wage growth continues to push up underlying inflation. However, more forward-looking indicators point to wage growth easing in the coming quarters, before stabilising towards the end of 2026. Our most recent assessment reconfirms that inflation should stabilise at the 2% target in the medium term.
Despite the challenging environment, economic activity has been resilient. It grew by 0.3% in the third quarter of 2025, mainly reflecting stronger consumption and investment. Growth was largely driven by the services sector, while activity in industry and construction remained flat. The economy also continues to benefit from a robust labour market, with unemployment close to its historical low.
Compared with earlier projections, economic growth has been revised up to stand above 1% this year and rise to 1.4% in the following years. Given the challenging environment for global trade, domestic demand is seen as the main engine of growth in the coming quarters. Business investment and substantial government spending on infrastructure and defence should increasingly underpin the economy. Consumption is also expected to rise but the household saving rate is only gradually coming down from still elevated levels. According to a recent ECB survey, the main reasons for high savings by euro area households include the fear of higher taxes in the future (Ricardian motives) and concerns about their future income (precautionary motives).[1]
Ricardian saving motives are linked to consumers’ expectations about future developments in taxes and welfare spending. Saving scores are thus higher in euro area countries with weaker fiscal positions, such as those with public debt-to-GDP ratios above 100%.[2] Precautionary saving motives are linked to income risk, which is strongly influenced by differences in individual perceptions about uncertainty. Elevated uncertainty and geopolitical developments also pose risks to business investment, with significant repercussions for euro area exports.
Risk Environment
As an open economy deeply integrated into global supply chains and international financial markets, the euro area is exposed to external shocks and vulnerabilities stemming from geopolitical and trade developments. China has become increasingly competitive in key export sectors of euro area countries, with its share of global exports rising steadily, particularly in advanced manufacturing and green technology sectors.
But high uncertainty in the global environment does not appear to be reflected in current market pricing.[3] In fact, negative surprises – such as a re-escalation of trade or other geopolitical tensions, setbacks in AI advances with asset price adjustments or intensifying doubts regarding US fiscal credibility – could trigger abrupt shifts in sentiment, with spillovers across asset classes and geographies.
Geopolitical risk noticeably raises downside risks to growth.[4] Countries more reliant on trade, or burdened with higher levels of public debt, are at greater risk of amplification effects and resulting downside pressures.
Inflation could be affected in different directions: it could be lower if the rise in US tariffs reduced demand for euro area exports and if countries with overcapacity increased their exports to the euro area; or higher if more fragmented global supply chains pushed up import prices, curtailed the supply of critical raw materials and added to capacity constraints in the euro area economy.
On the financial side, the heightened uncertainty could result in higher risk premia, tighter lending conditions and weaker loan growth. While financial markets appear to price in very benign outcomes and downplay tail risks, safe-haven flows into gold have driven up prices to record highs, signaling high geopolitical risk and policy uncertainty.
The materialisation of geopolitical risks could form a common trigger for three of the main sources of risk and vulnerability for euro area financial stability today.[5]
First, stretched valuations in increasingly concentrated asset markets raise the risk of sharp, correlated asset price adjustments. Sudden market drawdowns could pose challenges to euro area non-banks, especially given their liquidity and leverage vulnerabilities, increasing the risk of fire sales. And opaque private equity and private markets could easily cause or amplify market downturns.
Second, growing interlinkages between banks and the non-bank financial sector could expose funding vulnerabilities in stressed market conditions.[6] As non-banks provide short-term funding to banks while banks provide credit for the leveraged activities of the non-bank sector, exposures are at risk on both sides of banks’ balance sheets.
Third, fiscal challenges in some advanced economies could test investor confidence, possibly triggering stress in sovereign bond markets. Market concerns over US fiscal credibility have risen on the back of persistently high fiscal deficits and have contributed to a steepening of yield curves. This may create risk spillovers from the United States to the euro area amplified by policy uncertainty and a depreciating dollar. Fiscal fundamentals in some euro area countries have also been persistently weak. That said, financial markets have so far smoothly accommodated high levels of issuance, but structural challenges could further limit the fiscal space.
Planned defence spending to meet the new NATO target, ageing populations and climate change, with the associated physical and transition risks, represent major challenges. To mitigate the current risks to the sustainability of sovereign debt, excessive fiscal deficits and public debts in the euro area need to be reduced in line with the revised economic governance framework. The consolidation of public finances should be designed in a growth-friendly way and combined with strategic investment and growth-enhancing structural reforms.
EU Challenges Ahead
In this uncertain macro-financial environment, preserving the resilience of banks and the broader financial system remains crucial. Banks should maintain sound solvency and liquidity positions to enable them to absorb potential shocks ahead. At the same time, we are making significant efforts to reduce undue complexities and simplify EU banking rules and the reporting and supervisory framework for banks. In view of the growing importance of the non-bank sector, it is also vital to monitor it more closely and strengthen its regulation from a macroprudential perspective.
We are facing a big change in the world order with mounting geopolitical challenges. The only viable path forward is to sustain our European values and promote stronger cooperation and deeper integration within Europe. To strengthen Europe’s growth prospects and reduce its vulnerability to future shocks, we need more Europe, not less. Unlocking the full potential of the Single Market is crucial, as is completing the banking union. A truly integrated market for goods and services would advance progress towards the savings and investments union, reduce national fragmentation and support deeper and more efficient capital markets.
The world has changed, and Europe has to adapt to this new paradigm. Greater cooperation and integration are not optional – they are the only way forward for Europe.
 

See ECB (2026), ECB Consumer Expectations Survey results – November 2025, 8 January. While other saving motives, such as intertemporal substitution and saving out of habit, are also significant, they scored slightly lower in importance.
In the survey, Ricardian motives are validated by the finding that respondents reporting trust in their national government assign a significantly lower importance to the Ricardian saving motive relative to respondents who distrust their government. These survey results are consistent with those of Tabellini, G. (2010), “Culture and Institutions: Economic Development in the Regions of Europe”, Journal of the European Economic Association, Vol. 8, No 4, pp. 677-716.
See Financial Stability Review, ECB, November 2025.
See ECB/ESRB report on the financial stability risks from geoeconomic risks, forthcoming January 2026.
See footnote 3.
Bochmann, P., Dieckelmann, D., Grodzicki, M., Horan, A., Larkou, C. and Lenoci, F. (2025), “Systemic risks in linkages between banks and the non-bank financial sector”, Financial Stability Review, ECB, November.


Compliments of the European Central Bank The post ECB | Monetary Policy and Financial Stability in the Euro Area first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

World Bank | Global Economy Shows Resilience Amid Historic Trade, Policy Uncertainty

Yet one in four developing economies remains poorer than it was in 2019
WASHINGTON, January 13, 2026—The global economy is proving more resilient than anticipated despite persistent trade tensions and policy uncertainty, according to the World Bank’s latest Global Economic Prospects report.  Global growth is projected to remain broadly steady over the next two years, easing to 2.6% in 2026 before rising to 2.7% in 2027, an upward revision from the June forecast.
The resilience reflects better-than-expected growth—especially in the United States, which accounts for about two-thirds of the upward revision to the forecast in 2026. Even so, if these forecasts hold, the 2020s are on track to be the weakest decade for global growth since the 1960s. The sluggish pace is widening the gap in living standards across the world, the report finds: at the end of 2025, nearly all advanced economies enjoyed per capita incomes exceeding their 2019 levels, but about one in four developing economies had lower per capita incomes.
In 2025, growth was supported by a surge in trade ahead of policy changes and swift readjustments in global supply chains. These boosts are expected to fade in 2026 as trade and domestic demand soften. However, the easing global financial conditions and fiscal expansion in several large economies should help cushion the slowdown, according to the report. Global inflation is projected to edge down to 2.6% in 2026, reflecting softer labor markets and lower energy prices. Growth is expected to pick up in 2027 as trade flows adjust and policy uncertainty diminishes.
“With each passing year, the global economy has become less capable of generating growth and seemingly more resilient to policy uncertainty,” said Indermit Gill, the World Bank Group’s Chief Economist and Senior Vice President for Development Economics. “But economic dynamism and resilience cannot diverge for long without fracturing public finance and credit markets. Over the coming years, the world economy is set to grow slower than it did in the troubled 1990s—while carrying record levels of public and private debt. To avert stagnation and joblessness, governments in emerging and advanced economies must aggressively liberalize private investment and trade, rein in public consumption, and invest in new technologies and education.”
In 2026, growth in developing economies is expected to slow to 4% from 4.2% in 2025 before edging up to 4.1% in 2027 as trade tensions ease, commodity prices stabilize, financial conditions improve, and investment flows strengthen.  Growth is projected to be higher in low-income countries, reaching an average of 5.6% over 2026–27, buoyed by firming domestic demand, recovering exports, and moderating inflation. However, this  will not be sufficient to narrow the income gap between developing and advanced economies. Per capita income growth in developing economies is projected to be 3% in 2026—about a percentage point below its 2000-2019 average. At this pace, per capita income in developing economies is expected to be only 12% of the level in advanced economies. 
These trends could intensify the job-creation challenge confronting developing economies, where 1.2 billion young people will reach working age over the next decade. Overcoming the jobs challenge will require a comprehensive policy effort centered on three pillars. The first is strengthening physical, digital, and human capital to raise productivity and employability. The second is improving the business environment by enhancing policy credibility and regulatory certainty so firms can expand. The third is mobilizing private capital at scale to support investment. Together, these measures can help shift job creation toward more productive and formal employment, supporting income growth and poverty alleviation.
In addition, developing economies need to bolster their fiscal sustainability, which has been eroded in recent years by overlapping shocks, growing development needs, and rising debt-servicing costs.  A special-focus chapter of the report provides a comprehensive analysis of the use of fiscal rules by developing economies, which set clear limits on government borrowing and spending to help manage public finances. These rules are generally linked to stronger growth, higher private investment, more stable financial sectors, and a greater capacity to cope with external shocks.
“With public debt in emerging and developing economies at its highest level in more than half a century, restoring fiscal credibility has become an urgent priority,” said M. Ayhan Kose, the World Bank Group’s Deputy Chief Economist and Director of the Prospects Group. “Well-designed fiscal rules can help governments stabilize debt, rebuild policy buffers, and respond more effectively to shocks. But rules alone are not enough: credibility, enforcement, and political commitment ultimately determine whether fiscal rules deliver stability and growth.”
More than half of developing economies now have at least one fiscal rule in place. These can include limits on fiscal deficits, public debt, government expenditures, or revenue collection. Developing economies that adopt fiscal rules typically see their budget balance improve by 1.4 percentage points of GDP after five years, once interest payments and the ups and downs of the business cycle are accounted for.  Use of fiscal rules also increases by 9 percentage points the likelihood of a multi-year improvement in budget balances.  However, the medium- and long-term benefits of fiscal rules depend heavily on the strength of institutions, the economic context in which the rules are introduced, and how the rules are designed, the report finds.
Click here to download the full report.


Compliments of the World Bank GroupThe post World Bank | Global Economy Shows Resilience Amid Historic Trade, Policy Uncertainty first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.