EACC

EACCNY Labor Post-Pandemic Series Presents | Returning to Work During Covid-19: Managing Vulnerable Workers from a US and UK Perspective

With the help of our members, we are creating a Thought-Leadership series on the impact of COVID-19 on Labor & Employment from the perspective of both sides of the Atlantic. Today, we present Jill Kahn Marshall, Partner at Reavis Page Jump LLP in New York, and Matthew Kyle, Associate Director at Osborne Clarke in the UK, who will address “Returning to Work During Covid-19: Managing Vulnerable Workers from a US and UK Perspective.”  |
As offices reopen throughout the United States and Europe amidst an ongoing pandemic, employers must determine how to handle employee requests for health-related accommodations and how best to keep their workforce safe.  The United States, the United Kingdom and the European Union already have frameworks in place to protect vulnerable workers, and now employers must determine how these apply in light of the Covid-19 pandemic.
The United States and the Americans with Disabilities Act (ADA)
In the United States, the Americans with Disabilities Act (ADA)  requires covered employers to engage in an interactive process to provide reasonable accommodations for disabled employees, absent undue hardship to the employer.  In the midst of the Covid-19 pandemic, employers are receiving such requests from employees with underlying medical conditions which put them at higher risk from contracting Covid-19.  Due to the contagious nature of the virus, employees are also requesting accommodations where it is not they, but a family member with whom they reside, who is in a high risk category.
In response to these trends, the United States Equal Employment Opportunity Commission (EEOC), the federal government agency tasked with enforcing the ADA, has issued guidance to help employers handle these novel requests.  The EEOC guidance confirms that having an underlying medical condition which puts the employee at higher risk from Covid-19 does qualify as a disability for which the employer must consider reasonable accommodations, such as changes to the workspace or remote work to limit the employee’s exposure to others.  Although the Centers for Disease Control and Prevention (CDC) has stated individuals 65 and older are at greater risk of harm from the virus, falling within this age range alone does not trigger protections of the ADA.  The EEOC also clarifies that the ADA does not require accommodations for workers based on the underlying medical conditions of a relative.  Although the ADA prohibits discrimination based on association with an individual with a disability, that protection is limited to disparate treatment or harassment.
Accommodating Workers with Mental Illness
In addition to creating risks for people with underlying physical conditions, the pandemic has also exacerbated the conditions of workers who grapple with mental illness.  While feeling stress related to the pandemic alone would not necessarily qualify as a disability under the ADA, a preexisting anxiety disorder triggered by the pandemic would.  Employers must work with employees to see whether together, they can find an accommodation that works for both parties.
The Undue Hardship Defense
During the pandemic, employers may still utilize the ADA’s “undue hardship” defense, in that they are not required to provide an accommodation if it would impose a “significant difficulty or expense” on the employer.  In recognition that many employers are facing economic hardship as a result of the pandemic, the EEOC has expanded the definition of “significant expense.”  The employer’s sudden loss of income due to the pandemic is now relevant, as is the discretionary funds available to the employer during this difficult period.  This change does not allow employers to reject any accommodation that costs additional money during the pandemic, but rather, employers must weigh the cost of accommodations against their budget, accounting for constraints caused by the pandemic.
Protecting the Workforce
U.S. employers must also consider the ADA when making decisions about employees who may have contracted Covid-19 or are at a higher risk from doing so.  The EEOC advises that in order to protect the workforce from Covid-19, employers may require employees returning to work submit health questionnaires, undergo temperature checks, or take Covid-19 viral tests as a condition for returning to the workplace.  (Employers’ legal obligations surrounding the use and dissemination of the medical information obtained raises a host of privacy issues of which employers must be mindful of as well.)   Employers are not, however, permitted to require antibody tests, as the CDC has stated not enough is known about the immunity conferred by the presence of antibodies to make decisions about who can return to work based on these test results.
Policies for Older Workers and Pregnant Workers
While employers can take precautions to prevent those potentially infected with Covid-19 from entering the workplace, they cannot institute blanket policies related to higher risk individuals, even if the goal is to protect those workers or the general workforce.  For example, employers cannot mandate that workers 65 years or older, or pregnant workers, each of whom have been identified as being at greater risk from the virus, work from home, while allowing workers in other categories to choose whether to come into the office.  Employers can, however give these high risk employees the choice of whether to come into the office, as long as it is ultimately the employee’s decision.
Vulnerable Employees in the United Kingdom and European Union
As employees return to work there will be a renewed focus on the differing requirements of individuals and what employers should be doing to ensure that their health is protected.  In this section we briefly consider the issues arising out of health and safety and employment legislation in the UK.  However, the same themes and broad duties will also be applicable across the European Union as they reflect the same statutory framework.
The UK government recognises two groups of vulnerable people – those who are clinically extremely vulnerable (such as those diagnosed with cancer or who have had organ transplants) and those who are clinically vulnerable (over 70, pregnant or with some underlying health condition).
At present the government guidance for both categories is the same, although this could change if transmission increases, the most likely change being the requirement for extremely clinically vulnerable to return to self-shielding.  Therefore both extremely vulnerable and clinically vulnerable persons can go to work as long as the workplace is Covid-secure, but should carry on working from home wherever possible.  Covid-secure is a catch all term to indicate that those in control of the workplace environment have taken reasonable steps to mitigate the risk of transmission.  However, as a community virus and with people travelling to work often on public transport, for vulnerable individuals concerned it may not provide sufficient reassurance.
Employers have a legal duty under the Health and Safety at Work Etc. Act 1974, to control risks to the health and safety of employees and others affected by its business as far as is reasonably practicable. The starting point is to consider the risk to those who are particularly vulnerable to Covid-19 and put reasonable controls in place to reduce that risk.  Like other material risks to health and safety, the risk of Covid-19 should be assessed in terms of the operation of your business, including issues such as interaction with other parties and the shared use of facilities and equipment.  It is likely that the control measures that this assessment produces such as social distancing, good hygiene, cleaning, ventilation and supervision, will be those also used to protect vulnerable employees.  Whilst there may be no expectation of additional controls for vulnerable persons it is even more critical that those existing controls are stringently applied.  Therefore thinking not just about the initial implementation of procedures, but how compliance will be monitored is essential.
Ensuring that vulnerable workers are protected requires the employer to fully understand their needs, and this can only be achieved through clear and regular communication.  Consideration should extend to those employees living with someone who is clinically extremely vulnerable, something which will not be apparent unless the right questions have been asked and with the appropriate sensitivity.
It is important to explain what will be done to make the workplace safe. By consulting and involving vulnerable people in the steps employers are taking to manage Covid-19 risks they can hear their ideas and make sure changes will work.
Working from home or taking unpaid leave is currently a better approach for vulnerable employees if they are unhappy about returning to work. Many vulnerable employees will also qualify as disabled for the purposes of the Equality Act 2010. This means they have the right to reasonable adjustments, which could potentially include staying at home (if they are still able to perform their role).
It is also unlawful to operate provisions, criteria or practices which would put disabled employees at a disadvantage compared with non-disabled employees, unless this is justified. A policy of requiring vulnerable people to return to work could potentially be indirectly discriminatory and require justification. It may be hard to justify requiring an unwilling vulnerable employee to come back to work if, for example, other employees could cover their role or the employer could recruit temporary cover.
Pregnant employees
Employers must assess and control the specific risks to pregnant employees. It may be possible to do this by taking extra precautions to enforce safe distancing in the workplace. The current guidance does not say that vulnerable employees can never be asked to work, and this includes pregnant employees. It is a matter for employers’ own risk assessment and whether they are confident that they can provide a safe workplace.
If employers cannot ensure safe working conditions, they may need to temporarily alter the pregnant employees’ working conditions or hours, provide suitable alternative work on the same terms and conditions or (as a last resort) suspend the employee on full pay. This right to be suspended on full pay does not apply to other vulnerable employees, and in practice means that pregnant employees are treated differently than other vulnerable people.
What if the employee has anxiety which impacts on their ability to return to work?
If employers require their return, they may not be fit and able to work and may be signed off sick as a result, which would entitle them to sick pay. Even if they are not signed off sick, employees with some long-term mental health conditions may be disabled for the purposes of the Equality Act and it may be a reasonable adjustment to allow them to stay at home. They will not, however, be entitled to pay unless they are on sick leave or working from home.
Whether in the United States, United Kingdom, or the rest of Europe, good communication and an inclusive mindset is key to a successful return to work plan during Covid-19.  Employers need to take individual circumstances into account and act reasonably in considering any requests to stay at home; applying a blanket rule requiring all employees to return will not only raise the risk of a discriminatory impact, but could also damage the relationship of trust and confidence between the employer and its employees.  These are unprecedented circumstances for all parties involved, and employers must remain vigilant as the interpretation of the relevant laws continue to evolve during this pandemic.
AUTHORS:
Jill Kahn Marshall, Partner at Reavis Page Jump LLP, New York 
jmarshall@rpjlaw.com | +1 212 763 4145
Matthew Kyle, Associate Director at Osborne Clarke, UK 
Matt.kyle@osborneclarke.com | +44 781 126 9090
Stay tuned for more on this series! We hope you enjoy these Thought-Leadership pieces written by our members.

Read More
EACC

IMF | Aging Economies May Benefit Less from Fiscal Stimulus

In the midst of the current COVID-19 pandemic, policymakers around the world are undertaking fiscal stimulus—a combination of spending increases and tax reductions—to support their economies. Even before the present crisis, the importance of fiscal policy has been increasing, with monetary policy constrained by near-zero interest rates. Our new staff research finds that age also matters when considering fiscal stimulus. Specifically, we find that fiscal policy isn’t as effective in boosting growth in economies with older populations, compared to economies with younger populations.
As our chart shows, fiscal stimulus in economies with a younger population has a significantly positive effect on growth, but the effect is much weaker in aging economies. We looked at 17 Organization for Economic Cooperation and Development countries from 1985 to 2017, and split the sample into two groups by looking at the ratio of old people among population. In the aging economies, the average old-age dependency ratio (defined as the ratio of people 65 and older to those between 15 and 64 years old) is 26.5 percent whereas in non-aging economies it is 18.9 percent.
Image courtesy of the IMF.
On a more granular level, an aging economy behaves this way because its labor force isn’t growing, while its public debt tends to be high, and, therefore, fiscal stimulus has weaker effects on private consumption and investment. This is because the working age population is more likely than retirees to benefit from fiscal stimulus through effects such as increased corporate hiring. Furthermore, many pensioners are on fixed incomes whose consumption remains steady or even declines over time. In addition, population aging could reduce potential growth (by lowering labor input and productivity), with which fiscal stimulus may induce less private investment. The “older” the economy and the higher its debt, the less impact fiscal stimulus has on growth.
These findings complement existing observations that countries with aging populations have relatively low growth and higher public debt. Yet our findings are especially important because old-age dependency ratios have been rising for several decades and are projected to increase further. Within the next 30 years, more than 20 countries across the world would exceed the old-age dependency ratio of 50 percent—an unprecedented level in global history—with some even reaching 70 percent.
In other words, population aging is posing significant challenges to policymakers. How can we support aggregate demand with the weaker growth impact of fiscal stimulus in aging economies? The paper draws the following implications for policymakers to consider:
A larger fiscal stimulus may be required to support aggregate demand during recessions.
Given the lower output effects of fiscal stimulus, other economic policies (including structural reforms) would need to play a more important role in supporting domestic demand. Policy measures to enhance labor supply (for example, through stronger female labor force participation or labor market needs-based immigration) would help increase the output effects in aging societies.
Secure sufficiently large fiscal space (room to raise spending or lower taxes more than previously planned, without endangering debt sustainability or access to capital markets) during booms, in order to prepare for a larger fiscal stimulus during recessions, without creating concerns for fiscal sustainability.
AUTHORS:
Jiro Honda, Deputy Division Chief in the IMF’s Fiscal Affairs Department
Hiroaki Miyamoto, Professor of Economics and Business Administration at Tokyo Metropolitan University
Compliments of the IMF.

EACC

FSB Continuity of Access to FMIs for firms in resolution: streamlined information collection to support resolution planning

This questionnaire provides common template for gathering information about continuity of access to financial market infrastructures (FMIs) for firms in resolution. The template takes the form of a questionnaire that all FMIs are encouraged to complete. The responses to the questionnaire should be published or made available in other ways to firms that use the FMI services and their resolution authorities to inform their resolution planning. The use of a common questionnaire should reduce the “many to one” nature of inquiries from FMI participants and authorities to FMIs for resolution planning and streamline the provision of this information from FMIs to firms and authorities.
The questionnaire follows from a workshop held in May 2019 with stakeholders about the implementation of the FSB’s Guidance on Continuity of Access to Financial Market Infrastructures (FMIs) for a Firm in Resolution. The Guidance sets out arrangements and safeguards to facilitate continued access to critical clearing, payment, settlement, custody and other services provided by FMIs in cases where firms need to be resolved.
The FSB developed the questionnaire in consultation with FMIs, FMI participants, FMI oversight authorities and with the assistance of the Secretariats of the International Organization of Securities Commissions and of the Committee on Markets and Payments Infrastructures. It covers general information on the FMI and its legal structure; (the rulebook/contractual provisions regarding termination; and arrangements and operational processes to facilitate continued access in resolution. The experience with the use of the questionnaire will be reviewed after one year in consultation with FMIs and FMI participants.
The FSB will hold a webinar for stakeholders in September to explain the questionnaire and answer questions. Representatives of FMIs, FMI participants and authorities who would like to attend should contact fsb@fsb.org for more details.
Compliments of the Financial Stability Board.

EACC

Coronavirus: Commission reaches first agreement on a potential vaccine

Today, the European Commission has reached a first agreement with the pharmaceutical company AstraZeneca to purchase a potential vaccine against COVID-19 as well as to donate to lower and middle income countries or re-direct to other European countries. This is following the positive steps regarding the conclusion of exploratory talks with Sanofi-GSK announced on 31 July and with Johnson & Johnson on 13 August. Once the vaccine has proven to be safe and effective against COVID-19, the Commission now has agreed the basis for a contractual framework for the purchase of 300 million doses of the AstraZeneca vaccine, with an option to purchase 100 million more, on behalf of EU Member States. The Commission continues discussing similar agreements with other vaccine manufacturers.
Ursula von der Leyen, President of the European Commission, said: “The European Commission’s intense negotiations continue to achieve results. Today’s agreement is the first cornerstone in implementing the European Commission’s Vaccines Strategy. This strategy will enable us to provide future vaccines to Europeans, as well as our partners elsewhere in the world.”
Stella Kyriakides, Commissioner for Health and Food Safety, said: “Today, after weeks of negotiations, we have the first EU advance purchase agreement for a vaccine candidate. I would like to thank AstraZeneca for its constructive engagement on this important agreement for our citizens. We will continue to work tirelessly to bring more candidates into a broad EU vaccines portfolio. A safe and effective vaccine remains the surest exit strategy to protect our citizens and the rest of the world from the coronavirus.”
The agreement approved today will be financed with the Emergency Support Instrument, which has funds dedicated to the creation of a portfolio of potential vaccines with different profiles and produced by different companies.
AstraZeneca’s vaccine candidate is already in large-scale Phase II/III Clinical Trials after promising results in Phase I/II concerning safety and immunogenicity.
The decision to support the vaccine proposed by AstraZeneca is based on a sound scientific approach and the technology used (a non-replicative recombinant chimpanzee adenovirus-based vaccine ChAdOx1), speed at delivery at scale, cost, risk sharing, liability and the production capacity able to supply the whole of the EU, among others.
The regulatory processes will be flexible but remain robust. Together with the Member States and the European Medicines Agency, the Commission will use existing flexibilities in the EU’s regulatory framework to accelerate the authorisation and availability of successful vaccines against COVID-19. This includes an accelerated procedure for authorisation and flexibility in relation to labelling and packaging.
Background
The European Commission presented on 17 June a European strategy to accelerate the development, manufacturing and deployment of effective and safe vaccines against COVID-19. In return for the right to buy a specified number of vaccine doses in a given timeframe, the Commission would finance part of the upfront costs faced by vaccines producers in the form of Advance Purchase Agreements. Funding provided would be considered as a down-payment on the vaccines that will actually be purchased by Member States.
Since the high cost and high failure rate make investing in a COVID-19 vaccine a high-risk decision for vaccine developers, these agreement will therefore allow investments to be made that otherwise would simply probably not happen.
The European Commission is also committed to ensuring that everyone who needs a vaccine gets it, anywhere in the world and not only at home. No one will be safe until everyone is safe. This is why it has raised almost €16 billion since 4 May 2020 under the Coronavirus Global Response, the global action for universal access to tests, treatments and vaccines against coronavirus and for the global recovery.
Compliments of the European Commission.

EACC

U.S. Federal Reserve Board announces individual large bank capital requirements, which will be effective on October 1

Following its stress tests earlier this year, the Federal Reserve Board on Monday announced individual large bank capital requirements, which will be effective on October 1.
Under its framework for large banks—those with more than $100 billion in total assets—capital requirements are in part determined by stress test results, which provide a risk-sensitive and forward-looking assessment of capital needs. The below table shows the total common equity tier 1, or CET1, capital requirements for each large bank, which is comprised of several components, including:
Minimum capital requirements, which are the same for each firm and are 4.5 percent;
The stress capital buffer, or SCB, which is determined from the stress test results, and is at least 2.5 percent; and
If applicable, a capital surcharge for global systemically important banks, or GSIBs, which is at least 1.0 percent.
Capital buffers, such as the SCB and GSIB surcharge, are different than minimum capital requirements for each firm. The Federal Reserve supports banking organizations that choose to use their capital buffers to lend to households and businesses and undertake other supportive actions in a safe and sound manner. When using their buffers, banking organizations may make capital distributions up to prescribed limits, which include automatic limitations in the capital framework, as well as any additional limitations determined by the Board.
Also on Monday, the Board affirmed the stress test results for five firms that requested reconsideration. Those firms are BMO Financial Corporation, Capital One Financial Corporation, Citizens Financial Group, Inc., The Goldman Sachs Group Inc., and Regions Financial Corporation.
The reconsideration process involved an independent group—separate from the stress testing group—that analyzed and evaluated the results. The results were checked for errors and to ensure that the stress test models, which project the loan losses for banks, worked as intended and were consistent with the Board’s stress test framework.
As the Board has done with input gained from a variety of stakeholders and events, including its annual stress test model symposium, the Board will assess the information learned from the reconsideration process and use it to continue improving its stress testing methodology.
Bank
Minimum CET1 Capital Ratio
Stress Capital Buffer
GSIB Surcharge*
CET1 Capital Requirement
Ally Financial Inc.
4.5%
3.5%
n/a
8.0%
American Express Corporation
4.5%
2.5%
n/a
7.0%
Bank of America
4.5%
2.5%
2.5%
9.5%
The Bank of New York Mellon Corporation
4.5%
2.5%
1.5%
8.5%
Barclays US LLC
4.5%
5.0%
n/a
9.5%
BMO Financial Corp
4.5%
6.0%
n/a
10.5%
BNP Paribas USA, Inc.
4.5%
6.4%
n/a
10.9%
Capital One Financial Corporation
4.5%
5.6%
n/a
10.1%
Citigroup Inc.
4.5%
2.5%
3.0%
10.0%
Citizens Financial Group, Inc.
4.5%
3.4%
n/a
7.9%
Credit Suisse Holdings USA, Inc.
4.5%
6.9%
n/a
11.4%
DB USA Corporation
4.5%
7.8%
n/a
12.3%
Discover Financial Services
4.5%
3.5%
n/a
8.0%
DWS USA Corporation
4.5%
2.5%
n/a
7.0%
Fifth Third Bancorp
4.5%
2.5%
n/a
7.0%
The Goldman Sachs Group, Inc.
4.5%
6.7%
2.5%
13.7%
HSBC North America Holdings Inc.
4.5%
5.7%
n/a
10.2%
Huntington Bancshares Incorporated
4.5%
2.5%
n/a
7.0%
JPMorgan Chase & Co.
4.5%
3.3%
3.5%
11.3%
KeyCorp
4.5%
2.5%
n/a
7.0%
M&T Bank Corporation
4.5%
2.5%
n/a
7.0%
Morgan Stanley
4.5%
5.9%
3.0%
13.4%
MUFG Americas Holdings Corporation
4.5%
4.4%
n/a
8.9%
Northern Trust Corporation
4.5%
2.5%
n/a
7.0%
The PNC Financial Services Group, Inc.
4.5%
2.5%
n/a
7.0%
RBC US Group Holdings LLC
4.5%
3.6%
n/a
8.1%
Regions Financial Corporation
4.5%
3.0%
n/a
7.5%
Santander Holdings USA, Inc.
4.5%
2.5%
n/a
7.0%
State Street Corporation
4.5%
2.5%
1.0%
8.0%
TD Group US Holdings LLC
4.5%
2.5%
n/a
7.0%
Truist Financial Corporation
4.5%
2.7%
n/a
7.2%
UBS Americas Holdings LLC
4.5%
6.7%
n/a
11.2%
U.S. Bancorp
4.5%
2.5%
n/a
7.0%
Wells Fargo & Company
4.5%
2.5%
2.0%
9.0%
*The GSIB surcharge is updated annually in the first quarter.
For media inquiries, call 202-452-2955
Compliments of the U.S. Federal Reserve Board.

EACC

U.S. Federal Reserve Board announces revised pricing for its Municipal Liquidity Facility

The Federal Reserve Board on Tuesday announced revised pricing for its Municipal Liquidity Facility (MLF). The revised pricing reduces the interest rate spread on tax-exempt notes for each credit rating category by 50 basis points and reduces the amount by which the interest rate for taxable notes is adjusted relative to tax-exempt notes.
Today’s changes will ensure the MLF continues to provide an effective backstop to assist U.S. states and local governments as they weather the pandemic.
The MLF was established under Section 13(3) of the Federal Reserve Act, with approval of the Treasury Secretary. It offers up to $500 billion in lending to states and municipalities to help manage cash flow stresses caused by the coronavirus pandemic.
For media inquiries, call 202-452-2955.
Term sheet: Municipal Liquidity Facility (PDF)
Compliments of the U.S. Federal Reserve Board.

EACC

Coronavirus: 23 new research projects to receive €128 million in EU funding

The Commission will support 23 new research projects with €128 million in response to the continuing coronavirus pandemic. The funding under Horizon 2020, the EU’s research and innovation programme, is part of the Commission’s €1.4 billion pledge to the Coronavirus Global Response initiative, launched by President Ursula von der Leyen in May 2020.
The 23 projects shortlisted for funding involve 347 research teams from 40 countries, including 34 participants from 16 countries outside of the EU. The funding will enable researchers to address the pandemic and its consequences by strengthening the industrial capacity to manufacture and deploy readily available solutions, develop medical technologies and digital tools, improve understanding of behavioural and socio-economic impacts of the pandemic, and to learn from large groups of patients (cohorts) across Europe. These research actions complement earlier efforts to develop diagnostics, treatments and vaccines.
Mariya Gabriel, Commissioner for Innovation, Research, Culture, Education and Youth, said: “Emergency funding from Horizon 2020 will enable researchers to rapidly develop solutions with and for patients, care workers, hospitals, local communities and companies. The results will help them to better cope with and survive coronavirus infections. It’s encouraging to see the research community mobilise so rapidly and strongly.”
Thierry Breton, Commissioner for Internal Market, added: “The excellent response to this call shows the wealth of new ideas to tackle coronavirus, including new digital health solutions. Digital solutions and technologies enabled us to stay connected and interact with each other during the confinement. They will also be an essential part of the long-term response to this virus and to increasing our resilience.”
The Commission is currently negotiating grant agreements with the selected beneficiaries. The new projects will cover:
Repurposing manufacturing for rapid production of vital medical supplies and equipment needed for testing, treatment and prevention – for instance using injection moulding and additive manufacturing (3-D printing), adaptive production and supply chain methods, and repurposing manufacturing as a service network for fast reaction.
Developing medical technologies and digital tools to improve detection, surveillance and patients’ care – for example through the development of new devices for faster, cheaper and easier diagnosis (including remotely) plus new technologies to protect healthcare workers.
Analysing behavioural and socio-economic impacts of the responses of government and public health systems, for instance on mental health, including gender-specific aspects in risk factors and the socioeconomic burden, to develop inclusive guidance for policymakers and health authorities and enhance preparedness for future similar events.
Learning from large groups of patients (cohorts) by connecting existing cohorts in the EU and beyond to assess their exposure to certain risk factors to better understand the possible causes of disease in order to improve responsiveness to the virus and future public health threats.
Enhancing collaboration of existing EU and international cohorts by networking research institutions that are collecting data on patient care to enable studies into patient’s characteristics, risk factors, safety and effectiveness of treatments and potential strategies against coronavirus.
Background
This second emergency request for expressions of interest, launched by the Commission on 19 May 2020 gave researchers just under 4 weeks to prepare collaborative research projects. The research community mobilised rapidly. Research proposals were fast-tracked through evaluation by independent experts, enabling the Commission to shortlist a number of projects of excellent scientific quality and high potential impact. Although funding is conditional on a final Commission decision and the signature of the Horizon 2020 Grant Agreement, the research teams can already start their work.
Many of the 23 short-listed projects have an international dimension beyond the EU and associated countries, with 34 organisations involved from 16 countries outside of the EU including countries associated to the Horizon 2020 programme (Bosnia-Herzegovina, Israel, Norway, Serbia, Switzerland and Turkey) and third countries (Argentina, Australia, Brazil, Columbia, Congo, Gabon, India, Korea, South Africa and the United States).
This new special call under Horizon 2020 complements earlier actions to support 18 projects with €48.2 million to develop diagnostics, treatments, vaccines and preparedness for epidemics, as well as the €117 million invested in 8 projects on diagnostics and treatments through the Innovative Medicines Initiative, and measures to support innovative ideas through the European Innovation Council. It implements Action 3 of the ERAvsCorona Action Plan, a working document resulting from dialogues between the Commission and national institutions.
Compliments of the European Commission.

EACC

EU Commission: Getting ready for the end of the Brexit transition period

The Brexit transition ends December 31, 2020. In 5 months, the UK leaves Single Market and Customs Union. Changes are inevitable, with or without agreement on the new partnership. Companies and citizens must get ready.
Even if the European Union and the United Kingdom conclude a highly ambitious partnership covering all areas agreed in the Political Declaration by the end of 2020, the United Kingdom’s withdrawal from the EU acquis, the internal market and the Customs Union, at the end of the transition period will inevitably create barriers to trade and cross-border exchanges that do not exist today.
There will be broad and far-reaching consequences for public administrations, businesses and citizens as of 1 January 2021, regardless of the outcome of negotiations. These changes are unavoidable and stakeholders must make sure they are ready for them.
To assist, the Commission is reviewing – and where necessary updating – the over 100 sector-specific stakeholder preparedness notices it published during the Article 50 negotiations with the United Kingdom.
Those notices that have already been updated as ‘notices for readiness’ can be found using the following link: Getting ready for the end of the transition period
Compliments of the European Commission.

EACC

Lifting of travel restrictions: EU Council reviews the list of third countries

Following a review under the recommendation on the gradual lifting of the temporary restrictions on non-essential travel into the EU, the Council updated the list of countries for which travel restrictions should be lifted. As stipulated in the Council recommendation, this list will continue to be reviewed regularly and, as the case may be, updated.
Based on the criteria and conditions set out in the recommendation, as from 8 August member states should gradually lift the travel restrictions at the external borders for residents of the following third countries:
Australia
Canada
Georgia
Japan
New Zealand
Rwanda
South Korea
Thailand
Tunisia
Uruguay
China, subject to confirmation of reciprocity
Residents of Andorra, Monaco, San Marino and the Vatican should be considered as EU residents for the purpose of this recommendation.
The criteria to determine the third countries for which the current travel restriction should be lifted cover in particular the epidemiological situation and containment measures, including physical distancing, as well as economic and social considerations. They are applied cumulatively.
Regarding the epidemiological situation, third countries listed should meet the following criteria, in particular:
number of new COVID-19 cases over the last 14 days and per 100 000 inhabitants close to or below the EU average (as it stood on 15 June 2020)
stable or decreasing trend of new cases over this period in comparison to the previous 14 days
overall response to COVID-19 taking into account available information, including on aspects such as testing, surveillance, contact tracing, containment, treatment and reporting, as well as the reliability of the information and, if needed, the total average score for International Health Regulations (IHR). Information provided by EU delegations on these aspects should also be taken into account.
Reciprocity should also be taken into account regularly and on a case-by-case basis.
For countries where travel restrictions continue to apply, the following categories of people should be exempted from the restrictions:
EU citizens and their family members
long-term EU residents and their family members
travellers with an essential function or need, as listed in the Recommendation.
Schengen associated countries (Iceland, Lichtenstein, Norway, Switzerland) also take part in this recommendation.
Next steps
The Council recommendation is not a legally binding instrument. The authorities of the member states remain responsible for implementing the content of the recommendation. They may, in full transparency, lift only progressively travel restrictions towards countries listed.
A Member State should not decide to lift the travel restrictions for non-listed third countries before this has been decided in a coordinated manner.
This list of third countries should continue to be reviewed regularly and may be further updated by the Council, as the case may be, after close consultations with the Commission and the relevant EU agencies and services following an overall assessment based on the criteria above.
Travel restrictions may be totally or partially lifted or reintroduced for a specific third country already listed according to changes in some of the conditions and, as a consequence, in the assessment of the epidemiological situation. If the situation in a listed third country worsens quickly, rapid decision-making should be applied.
Background
On 16 March 2020, the Commission adopted a communication recommending a temporary restriction of all non-essential travel from third countries into the EU for one month. EU heads of state or government agreed to implement this restriction on 17 March. The travel restriction was extended for a further month respectively on 8 April 2020 and 8 May 2020.
On 11 June the Commission adopted a communication recommending the further extension of the restriction until 30 June 2020 and setting out an approach for a gradual lifting of the restriction on non-essential travel into the EU as of 1 July 2020.
On 30 June the Council adopted a recommendation on the gradual lifting of the temporary restrictions on non-essential travel into the EU, including an initial list of countries for which member states should start lifting the travel restrictions at the external borders. This list was updated on 16 July and 30 July.
Compliments of the European Council.

Read More
EACC

COVID-19 Response in Emerging Market Economies: Conventional Policies and Beyond

The economic impact of the COVID-19 pandemic on emerging market economies far exceeded that of the global financial crisis. Unlike previous crises, the response has been decisive just like in advanced economies. Yet, conventional policies are reaching their limit and unorthodox policies are not without risks.
A pandemic still unfolding
COVID-19 is still to play out fully in the emerging market universe (see chart for country list), posing risks to both people and economies. While countries such as China, Uruguay, and Vietnam have managed to contain the virus, others such as Brazil, India, and South Africa continue to grapple with a rise in infections.
Emerging markets are likely to face an uphill battle.
The economic impact has been even more severe as emerging market economies were buffeted by multiple shocks. Compounding the effects of domestic containment measures has been a decline in external demand. Particularly hit are tourism-dependent countries due to a decline in travel and oil exporters as commodity prices plummeted. With global trade and oil prices projected to drop by more than 10 percent and 40 percent respectively, emerging market economies are likely to face an uphill battle. This is even as capital outflows have stabilized and sovereign spreads retreated compared to the sharply volatile market conditions seen in March.
Not surprisingly, the IMF’s latest June World Economic Outlook Update projects emerging market economies to shrink by 3.2 percent this year—the largest drop for this group on record. By way of comparison, in the global financial crisis, growth for the group took a significant hit but still bottomed out at a positive 2.6 percent in 2009.
A decisive policy response
The crisis would have been worse still without the extraordinary policy support. For sure, decisive policy actions in advanced economies led to a turnaround in market conditions that allowed emerging market economies to resume external financing efforts in April and May, which contributed to record levels of bond issuance so far this year—to the tune of $124 billion as of the end of June. But not all countries have seen improved fortunes. Fuel exporters, frontier countries and those with high debt are experiencing a greater financial shock that pushed up borrowing costs, or even worse, denied them further access to markets.
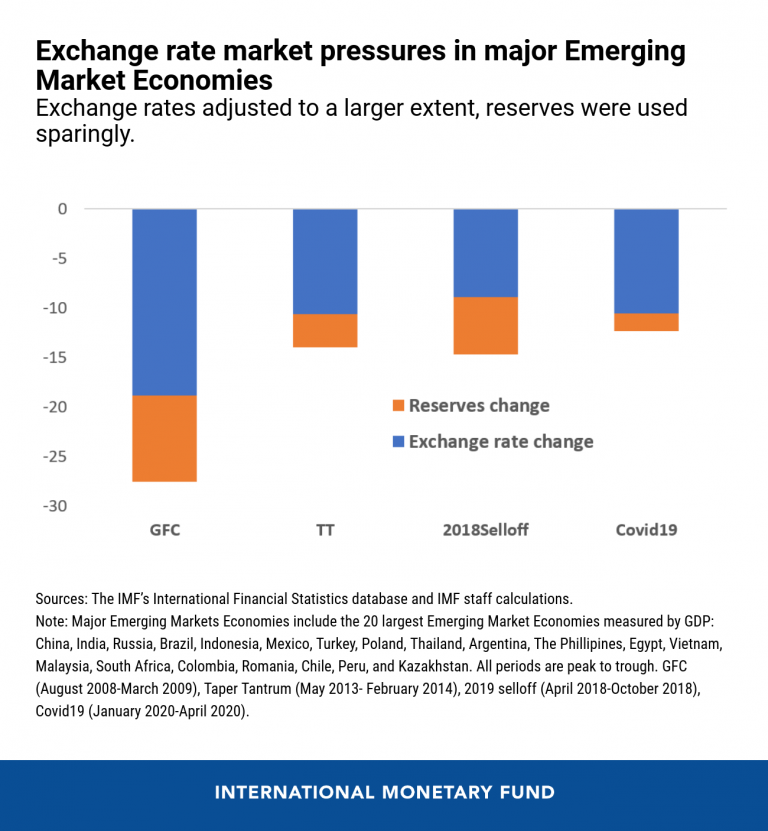
Policy support by advanced economies provided emerging market economy policymakers with wiggle room to soften the economic blow. Unlike previous episodes, where emerging market economies tended to tighten policy to avoid rapid capital outflows and the inflationary effect of exchange rate depreciations, the current crisis has seen emerging market economies’ policy reaction more in line with that of advanced economies (see the IMF’s policy tracker). Most emerging market economies used reserve buffers more sparingly and allowed exchange rates to adjust to a larger extent, while many countries injected liquidity as needed to ensure market functioning. Countries like Poland and Indonesia further eased macroprudential policies to support credit.

Image courtesy of the IMF.
Like their more advanced peers, many emerging market economies, including Thailand, Mexico, and South Africa, eased monetary policy during this cycle. In a few cases, limited room to cut policy rates further and distressed market conditions induced use of unconventional monetary policy measures for the first time. These included purchases of government and corporate bonds, although the amounts remain modest so far compared to the larger advanced economies. Conversely, the use of capital flow measures to deter capital outflows has been quite limited so far.
A similar picture is evident on the fiscal policy front. Emerging market economies have relaxed their fiscal stance in an attempt to tackle the health crisis, support people and firms, and offset the economic shocks. While more modest than that of advanced economies, these efforts were significantly greater than during the global financial crisis.
From conventional to unorthodox policies
Despite these actions, the outlook for emerging market economies remains clouded by considerable uncertainty. Chief among many risks is the possibility of a more prolonged health crisis, which would hurt more lives and could have dire economic consequences. Confronting a more severe downturn will be challenging because most emerging markets entered the current crisis with limited room for traditional fiscal, monetary, and external policy support. And much policy room has already been used up by actions undertaken in recent months.
Dwindling policy space may force some countries to take recourse to more unorthodox measures. From price controls and trade restrictions to more unconventional monetary policy and steps to ease credit and financial regulation. Some of these measures—which are also being implemented by some advanced and low-income economies—have significant costs, particularly if used intensively. Export restrictions, for example, could seriously distort the multilateral trading system, and price controls hamper the flow of goods to those who need it most.
The effectiveness of other unorthodox policies will depend on the credibility of the institutions; for instance, whether a country has a track record of credible monetary policy. As we navigate the contours of the ongoing crisis, little time is available to properly analyze the risks and benefits of these actions in a careful manner.
Not out of the woods yet
Emerging market economies have navigated the first phase of the crisis relatively well, but the next phase could be much more challenging. The virus remains present, financial conditions are still fragile, and policy space is lower, particularly for those countries facing high risks to debt sustainability. The latter group of countries is quite large. Approximately one third of all emerging market economies entered the crisis with high-debt levels and are assessed to have no space for undertaking additional discretionary fiscal policy, or as having that space significantly at risk.
Image courtesy of the IMF.
As the crisis develops, there is also a high risk that liquidity problems morph into solvency concerns. Besides sovereign debt stresses, corporate default risks are alarmingly high in a number of emerging market economies. Moreover, the crisis has hit poor people much harder, and this increase in inequality will amplify policy challenge in many countries.
The complexity of these challenges requires a multi-faceted policy response. First, domestic policies will need to be designed to allow for more durable and inclusive growth. Second, increased support from bilateral and multilateral lenders will be required where market access remains precarious. So far, the IMF has provided 22 emerging market economies with approximately $72 billion (SDR 52 billion) in financial assistance. Finally, for countries where debts prove to be unsustainable, timely and durable resolution of these problems will be needed, by seeking broad burden sharing across creditors including in the private sector. The latter two policy angles will be analyzed in two subsequent blogs on IMF lending and the IMF’s role in debt resolution.
AUTHORS:
Martin Mühleisen, Director of the Strategy, Policy, and Review Department (SPR) of the IMF
Tryggvi Gudmundsson, Economist in the IMF’s SPR
Hélène Poirson Ward, Deputy Division Chief in the IMF’s SPR
Compliments of the IMF.