EACC

What The Brexit Trade Deal Means by John Bruton

By John Bruton, former Taoiseach, Irish Prime Minister, and former EU Ambassador to the United States
The Trade and Cooperation Agreement between the EU and the UK is an exercise in damage limitation. The UK will face numerous obstacles because of its decision to leave the EU, including leaving the Customs Union and Single Market.
But it was in nobody’s interest to add to these obstacles. That was the spirit in which the EU approached the negotiation.
The Agreement may run to 1256 pages, but it boils down to some fairly simple and sensible ideas.
While no longer a member of the EU, the UK still wants to do business with the EU, and the EU members want to do business with it.
So, for the future, there needs to be a system for ensuring that there are no surprises, or unfair trading , that would disrupt mutually beneficial business. That is essentially what the Agreement is all about.
While the UK was a member of the EU, that goal was achieved by having a common set of business rules, made democratically and together, and interpreted in a consistent way by the European Court of Justice (ECJ). These rules could be enforced in national courts. In other words the goal of predictable and fair business conditions between the UK and its fellow EU members was achieved directly by common action.
Under the new Agreement, the same goal will be pursued, but indirectly.
Common rules, made and interpreted in common, will be replaced, as far as trade between the EU and the UK is concerned, by understandings set out in the Agreement, which will be interpreted by arbitrators appointed under the Agreement.
These understandings will have legal force, but will generally only be enforceable under the procedures set out in the Agreement, rather than directly in national courts.
While the EU and the UK will each be free to determine their own policies on the environment, social and working conditions, and subsidy controls, Article 9.4 of the Agreement allows for “rebalancing” measures to be taken by the other side if it feels its own businesses are being put at a disadvantage. This is supposed to restore the level in the level playing field.
The Agreement contains principles, now to be enshrined in international law through the Agreement, that are shared by the EU and the UK. These cover environmental, social and subsidy issues. Arbitration Tribunals to be set up under the Agreement will interpret these agreed principles in specific cases. They will have a legal, but also a political, task.
Most of the text of the Agreement is taken up with procedures for resolving disputes.
Matters, currently resolved in national courts under EU law, will have to be resolved at inter state level between the UK and the EU, rather than in the national courts. This is inherently more cumbersome.
Sometimes the issue will be settled by political agreement in one of the myriad of committees set up under the Agreement.
ARBITRATION…. THE CORE IDEA
If the issue cannot be settled in this way, it will go the arbitration.
So, instead of the interpretation being done by Judges of the ECJ, they will be done by an Arbitration Tribunal set up under the Agreement.
An Arbitration Tribunal will consist of three people. There will be lists of qualified arbitrators from which the three may be chosen, one by the UK and one by the EU and the Chair of the Tribunal will be someone who is not from EU or the UK.
I think this idea that the chair must come from outside either the EU or UK may prove difficult. It will not  always be easy  to find suitable chairs who are not either British or EU citizens, especially as the work will have to be done at short notice and under tight time limits.
To qualify for appointment, an arbitrator will have to have “demonstrated expertise in law and international trade” .  They will all have to be people “whose independence is beyond doubt”. They will serve in their individual capacities, and not take instructions from anyone. They will have to be people who would qualify to be judges in their home countries.
I suspect there will be a lot of intense haggling over the composition of particular Arbitration Tribunals.  The nationality of the arbitrators and their past records will be scrutinised by the governments most affected by the issues in dispute.
There are detailed provisions in the Agreement to prevent stalling by either the EU, or the UK, in appointing Arbitrators. Once established, the Tribunals will have to deliver their ruling within 130 days . Within 30 days after that, the affected party will have to say how they will comply with the ruling.
This entire structure of dispute resolution will be presided over by a Partnership Council to be chaired jointly, by a UK Minister and an EU Commissioner. It will be assisted by over 20 specialised committees and a number of Working Groups, all of which are listed in Title III of the Agreement.
EVEN MORE MEETINGS THAN BEFORE!
I expect that there will, in the future, be even more EU related meetings for UK officials than in the past.  But the dynamic will be different.
Instead of being able to build alliances on particular topics with other EU member states, the UK will in future find itself alone in the room with the European Commission.
The Commission side will have instructions, negotiated in advance with the 27 member states, so there will be a high degree of rigidity in the process.
As the EU member state most affected by relations between the UK and the EU, this will be a particular challenge for Ireland. Irish officials in Brussels and will have to stay on top of all that is going on in the various EU/UK committees. Cultivating an understanding with the Commission officials serving on these committees will be a priority.
No longer in the EU, the UK will, notwithstanding the provisions of the Agreement, encounter significant extra bureaucracy and uncertainty in doing business with the EU.
PARTING COMPANY GRADUALLY
This will lead to a gradual divergence between the UK and all its European neighbours, including Ireland. That, in turn, will have cultural and political effects.
The UK, and the EU states including Ireland will, so to speak, be mixing in different company .They will increasingly be seeing the world from diverging angles of vision. Issues that were previously depoliticised will become more political.
Eventually, this may affect the way the UK sees its physical and military security. NATO is already under strain, and Brexit creates a new fault line within NATO.
While Ireland is not in NATO, we live in a part of the world which has sheltered under the NATO umbrella, and we are deeply interconnected with NATO’s biggest member, the US.
Brexit may be over and done with, but the forces which led to it…identity politics and suspicion of foreigners….have not gone away.The post What The Brexit Trade Deal Means by John Bruton first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

Agreements reached between the United Kingdom of Great Britain and Northern Ireland and the European Union

NOTE: The Trade and Cooperation Agreement and other agreements below are provided for information only. No rights may be derived from them until the date of application. The numbering of the articles is provisional.

The United Kingdom and the European Union have agreed a Trade and Cooperation Agreement, an Agreement on Nuclear Cooperation and an Agreement on Security Procedures for Exchanging and Protecting Classified Information. These Agreements are designed to honour the instruction of the British people – expressed in the referendum of 2016 and the general election last year – to take back control of our laws, borders, money, trade and fisheries. It changes the basis of our relationship with our European neighbours from EU law to free trade and friendly cooperation.
Summary Explainer  [PDF, 460KB, 34 pages]

Foreword from the Prime MinisterThis Agreement with the European Union is designed to honour the instruction of the British people – expressed in the referendum of 2016 and the general election last year – to take back control of our laws, borders, money, trade and fisheries. It changes the basis of our relationship with our European neighbours from EU law to free trade and friendly cooperation.
And this ambitious Agreement – carefully judged to benefit everyone – is the first the EU has ever reached allowing zero tariffs and zero quotas. We will preserve the immense benefits of free trade for millions of people in the United Kingdom and across Europe.
At the same time, our Agreement means that the UK will fully recover its national independence. At 11pm on 31 December, we will take back control of our trade policy and leave the EU customs union and single market. We will take back control of our waters, with this treaty affirming British sovereignty over our vast marine wealth. We will take back control of our money by ending vast payments to the EU. We will take back control of our borders and will introduce our new points-based immigration system at the start of next year. Most importantly, the agreement provides for the UK to take back control of our laws, affording no role for EU law and no jurisdiction for the European Court of Justice. The only laws we will have to obey are the ones made by the Parliament we elect.
While we made our fair share of compromises during the negotiations, we never wavered from the goal of restoring national sovereignty – the central purpose of leaving the EU. I have always said that Brexit was not an end but a beginning: the start of a new era of national change and renewal, the next act in the great drama of our country’s story. We will regain the ability to wield powers that have for too long been the sole preserve of Brussels. We will now take up these tools to deliver the changes that people yearn for and, in so doing, we will restore faith in our democracy.
The UK is, of course, culturally, spiritually and emotionally part of Europe. This agreement provides for close and friendly cooperation with our neighbours in all the many areas where our values and interests coincide. It is my fervent hope that this Treaty, rooted in Britain’s sense of itself as a proudly European country, will help to bring people together and heal some of the divisions created by the referendum over four years ago.
The responsibility now falls on our shoulders to take full advantage of the freedom of action our country has regained. Next year will be our opportunity to show what Global Britain can do, reasserting ourselves as a liberal free trading nation and a force for good in the world.
More information
1. Introduction
2. Trade and Cooperation Agreement: Overview
3. Part 1 – Common and Institutional Provisions
4. Part 2 – Trade, Transport, Fisheries and Other Arrangements
5. Heading Five – Fisheries
6. Part 3 – Law Enforcement and Judicial Cooperation in Criminal Matters
7. Part 4 – Thematic Cooperation
8. Part 5 – Participation in Union Programmes
9. Part 6 – Dispute Settlement and Horizontal Provisions
10. Part 7 – Final Provisions
11. Other Agreements
ADDITIONAL INFORMATION

Trade and Cooperation Agreement (including Annexes and Protocols)  [PDF, 9.21MB, 1246 pages]

Declarations  [PDF, 711KB, 26 pages]

Nuclear Cooperation Agreement  [PDF, 279KB, 18 pages]

Agreement on Security Procedures for Exchanging and Protecting Classified Information  [PDF, 226KB, 8 pages]

Compliments of Her Majesties Government

The post Agreements reached between the United Kingdom of Great Britain and Northern Ireland and the European Union first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

EU-UK Trade and Cooperation Agreement: A new relationship, with big changes – Overview of consequences and benefits

On 1 January 2021, the United Kingdom will leave the EU Single Market and Customs Union, and all EU policies. This was its choice.
As a result, it will lose all the rights and benefits it had as an EU Member State, and will no longer be covered by the EU’s international agreements. This will bring far-reaching changes, affecting citizens, businesses, public administrations and stakeholders in both the EU and the UK. To limit the disruption insofar as possible, the EU and the United Kingdom have spent the past year negotiating the terms of a new “Trade and Cooperation Agreement” to govern their future relations now that the UK is a third country.
On 24 December 2020, an agreement in principle was reached at negotiators’ level. Both parties will now advance with the signature and ratification of the Agreement, in line with their respective rules and procedures, with a view to its provisional application from 1 January 2021.
The new EU-UK Trade and Cooperation Agreement: What has been agreed?
On 24 December 2020, EU and UK negotiators reached an “agreement in principle” on the text of a new “Trade and Cooperation Agreement” to govern their relations now that the UK has left the EU. Both parties must now advance with the signature and ratification of this Agreement in line with their respective rules and procedures, with a view to its provisional application as from 1 January 2021.
While the new EU-UK Trade and Cooperation Agreement will by no means match the level of cooperation that existed while the UK was an EU member, it goes well beyond traditional free trade agreements and provides a solid basis for preserving our longstanding friendship and cooperation going forward.
It consists of:
1. an unprecedented free trade agreement,
2. ambitious cooperation on economic, social, environmental and fisheries issues,
3. a close partnership for citizens’ security,
4. an overarching governance framework.
The Agreement reflects the fact that the UK is leaving the EU’s ecosystem of common rules, supervision and enforcement mechanisms, and can thus no longer enjoy the benefits of membership or the Single Market.
It confers rights and obligations on each party, while fully respecting their regulatory and decision-making autonomy. At the UK’s request, the Agreement does not cover cooperation on foreign policy, external security and defence, even though this was initially foreseen in the Political Declaration. In addition, the Agreement does not cover any decisions relating to equivalences for financial services. Nor does it cover possible decisions pertaining to the adequacy of the UK’s data protection regime, or the assessment of its sanitary and phytosanitary regime for the purpose of listing it as a third country allowed to export food products to the EU. These are and will remain unilateral decisions of the EU and are not subject to negotiation.
Examples of inevitable change on 1 January 2021:

 The free movement of persons will end: UK citizens will no longer have the freedom to work, study, start a business or live in the EU. They will need visas for long-term stays in the EU. Border checks will apply, passports will need to be stamped, and EU pet passports will no longer be valid for UK residents.
 The free movement of goods will end: Customs checks and controls will apply to all UK exports entering the EU. UK agri-food consignments will have to have health certificates and undergo sanitary and phytosanitary controls at Member States’ border inspection posts. This will cost UK businesses time and money.
 The free movement of services will end: UK service providers will no longer benefit from the country-of-origin principle. They will have to comply with the – varying – rules of each Member State, or relocate to the EU if they want to continue operating as they do today. There will be no more mutual recognition of professional qualifications. UK financial services firms will lose their financial services passports.

Below are links to a selection of key documents that explain what is next:

EU-UK Trade and Cooperation Agreement: A new relationship, with big changes – Overview of consequences and benefits

EU-UK Trade and Cooperation Agreement: A new relationship, with big changes – Brochure

EU-UK Relations: From the UK referendum to a new Trade and Cooperation Agreement – Timeline

EU-UK Relations: From the UK referendum to a new Trade and Cooperation Agreement – Infographic

Compliments of the European Commission
IN THIS CONTEXT: Be sure to follow the EACCNY’s announcements on upcoming webinars and thought-leadership articles to learn what Brexit will mean to your company. Members interested in joining the Brexit Working group should reach out to the EACCNY’s Executive Director. We also encourage you to check our our Brexit news section as well as the Brexit Musings podcast series.The post EU-UK Trade and Cooperation Agreement: A new relationship, with big changes – Overview of consequences and benefits first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

Europe fit for the Digital Age: Commission proposes new rules for digital platforms

The Commission has proposed today an ambitious reform of the digital space, a comprehensive set of new rules for all digital services, including social media, online market places, and other online platforms that operate in the European Union: the Digital Services Act and the Digital Markets Act.
European values are at the heart of both proposals. The new rules will better protect consumers and their fundamental rights online, and will lead to fairer and more open digital markets for everyone. A modern rulebook across the single market will foster innovation, growth and competitiveness and will provide users with new, better and reliable online services. It will also support the scaling up of smaller platforms, small and medium-sized enterprises, and start-ups, providing them with easy access to customers across the whole single market while lowering compliance costs. Furthermore, the new rules will prohibit unfair conditions imposed by online platforms that have become or are expected to become gatekeepers to the single market. The two proposals are at the core of the Commission’s ambition to make this Europe’s Digital Decade.
Margrethe Vestager, Executive Vice-President for a Europe fit for the Digital Age, said: “The two proposals serve one purpose: to make sure that we, as users, have access to a wide choice of safe products and services online. And that businesses operating in Europe can freely and fairly compete online just as they do offline. This is one world. We should be able to do our shopping in a safe manner and trust the news we read. Because what is illegal offline is equally illegal online.”
Commissioner for Internal Market Thierry Breton said: “Many online platforms have come to play a central role in the lives of our citizens and businesses, and even our society and democracy at large. With today’s proposals, we are organising our digital space for the next decades. With harmonised rules, ex ante obligations, better oversight, speedy enforcement, and deterrent sanctions, we will ensure that anyone offering and using digital services in Europe benefits from security, trust, innovation and business opportunities.”
Digital Services Act
The landscape of digital services is significantly different today from 20 years ago, when the eCommerce Directive was adopted. Online intermediaries have become vital players in the digital transformation. Online platforms in particular have created significant benefits for consumers and innovation, have facilitated cross-border trading within and outside the Union, as well as opened up new opportunities to a variety of European businesses and traders. At the same time, they can be used as a vehicle for disseminating illegal content, or selling illegal goods or services online. Some very large players have emerged as quasi-public spaces for information sharing and online trade. They have become systemic in nature and pose particular risks for users’ rights, information flows and public participation.
Under the Digital Services Act, binding EU-wide obligations will apply to all digital services that connect consumers to goods, services, or content, including new procedures for faster removal of illegal content as well as comprehensive protection for users’ fundamental rights online. The new framework will rebalance the rights and responsibilities of users, intermediary platforms, and public authorities and is based on European values – including the respect of human rights, freedom, democracy, equality and the rule of law. The proposal complements the European Democracy Action Plan aiming at making democracies more resilient.
Concretely, the Digital Services Act will introduce a series of new, harmonised EU-wide obligations for digital services, carefully graduated on the basis of those services’ size and impact, such as:

Rules for the removal of illegal goods, services or content online;
Safeguards for users whose content has been erroneously deleted by platforms;
New obligations for very large platforms to take risk-based action to prevent abuse of their systems;
Wide-ranging transparency measures, including on online advertising and on the algorithms used to recommend content to users;
New powers to scrutinize how platforms work, including by facilitating access by researchers to key platform data;
New rules on traceability of business users in online market places, to help track down sellers of illegal goods or services;
An innovative cooperation process among public authorities to ensure effective enforcement across the single market.

Platforms that reach more than 10% of the EU’s population (45 million users) are considered systemic in nature, and are subject not only to specific obligations to control their own risks, but also to a new oversight structure. This new accountability framework will be comprised of a board of national Digital Services Coordinators, with special powers for the Commission in supervising very large platforms including the ability to sanction them directly.
Digital Markets Act
The Digital Markets Act addresses the negative consequences arising from certain behaviours by platforms acting as digital “gatekeepers” to the single market. These are platforms that have a significant impact on the internal market, serve as an important gateway for business users to reach their customers, and which enjoy, or will foreseeably enjoy, an entrenched and durable position. This can grant them the power to act as private rule-makers and to function as bottlenecks between businesses and consumers. Sometimes, such companies have control over entire platform ecosystems. When a gatekeeper engages in unfair business practices, it can prevent or slow down valuable and innovative services of its business users and competitors from reaching the consumer. Examples of these practices include the unfair use of data from businesses operating on these platforms, or situations where users are locked in to a particular service and have limited options for switching to another one.
The Digital Markets Act builds on the horizontal Platform to Business Regulation, on the findings of the EU Observatory on the Online Platform Economy, and on the Commission’s extensive experience in dealing with online markets through competition law enforcement. In particular, it sets out harmonised rules defining and prohibiting those unfair practices by gatekeepers and providing an enforcement mechanism based on market investigations. The same mechanism will ensure that the obligations set out in the regulation are kept up-to-date in the constantly evolving digital reality.
Concretely, the Digital Markets Act will:

Apply only to major providers of the core platform services most prone to unfair practices, such as search engines, social networks or online intermediation services, which meet the objective legislative criteria to be designated as gatekeepers;
Define quantitative thresholds as a basis to identify presumed gatekeepers. The Commission will also have powers to designate companies as gatekeepers following a market investigation;
Prohibit a number of practices which are clearly unfair, such as blocking users from un-installing any pre-installed software or apps;
Require gatekeepers to proactively put in place certain measures, such as targeted measures allowing the software of third parties to properly function and interoperate with their own services;
Impose sanctions for non-compliance, which could include fines of up to 10% of the gatekeeper’s worldwide turnover, to ensure the effectiveness of the new rules. For recurrent infringers, these sanctions may also involve the obligation to take structural measures, potentially extending to divestiture of certain businesses, where no other equally effective alternative measure is available to ensure compliance;
Allow the Commission to carry out targeted market investigations to assess whether new gatekeeper practices and services need to be added to these rules, in order to ensure that the new gatekeeper rules keep up with the fast pace of digital markets.

Next steps
The European Parliament and the Member States will discuss the Commission’s proposals in the ordinary legislative procedure. If adopted, the final text will be directly applicable across the European Union.
Background
The Digital Services Act and the Digital Markets Act are the European answer to the deep reflection process in which the Commission, EU Member States and many other jurisdictions have engaged in recent years to understand the effects that digitalisation – and more specifically online platforms – have on fundamental rights, competition, and, more generally, on our societies and economies.
The Commission consulted a wide range of stakeholders in preparation of this legislative package. During the summer of 2020, the Commission consulted stakeholders to further support the work in analysing and collecting evidence for scoping the specific issues that that may require an EU-level intervention in the context of the Digital Services Act and the New Competition Tool, which served as basis for the proposal on the Digital Markets Act. The open public consultations in preparation of today’s package, which ran from June 2020 to September 2020, received more than 3000 replies from the whole spectrum of the digital economy and from all over the world. 
For More Information
Questions and Answers on the Digital Services Act
Questions and Answers on the Digital Markets Act
Facts page: The Digital Services Act
Facts page: The Digital Markets Act
Results of the public consultation on the Digital Services Act
Results of the public consultation on a New Competition Tool
Website on antitrust procedures
European Democracy Action Plan
Political Guidelines of President von der Leyen
Brochure – How do online platforms shape our lives and businesses?

The post Europe fit for the Digital Age: Commission proposes new rules for digital platforms first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

Speech by Michel Barnier in plenary session of the European Parliament Today

Madame President, Ladies and Gentlemen,
Thank you for this new opportunity to take stock of this very long and extraordinary negotiation that I have the honor to lead on behalf of the Commission and on your behalf for more than four years now. Together, with your Parliament and the Council, we have already succeeded in enabling an orderly withdrawal of the United Kingdom, as it wished. It is for this withdrawal agreement that Maroš Šefčovič has just spoken of, that I would like to thank personally, and in front of you, for his tenacity and the efficiency with which he and our teams have succeeded in specifying all the concrete and operational modalities so that this Treaty, ratified last year by your Parliament and the British Parliament, be implemented in due time – as is normal and necessary for peace in Ireland, the economy of the whole island and the protection of the internal market. What I’m here to tell you about is our second negotiation.
Beyond its exit from the European Union, it is a question of knowing whether the United Kingdom will leave in ten days, the single market and the customs union with an agreement or without an agreement. We are at the moment of truth. We have very little time left, a few useful hours in this negotiation, if we want this agreement to enter into force on January 1.
As our President Ursula von der Leyen told you two days ago here, the possibility of an agreement is there, I think as a negotiator, but the road is very narrow. Now is the time to make decisions. It is also the moment for everyone to take responsibility. For my part, I will take mine – as I have always done throughout my public engagement – in accordance with the mandate that was set for me by the 27 Member States of the European Union and which was supported and confirmed by the vast majority of political groups here in the European Parliament, through your resolutions.
Today I would like to recall three fundamental elements of this negotiation. It was the British who set this very short deadline to which we are now forced, by refusing in June any form of extension of the transition period. What it is about is an extraordinary negotiation, carried out in 9 months, as never we have had in the past – never – on so many subjects, which are at the heart of your resolutions and our mandate.
Even if we regret that the British did not want to go further, through an agreement, which we were ready to negotiate, on foreign policy, defense and cooperation. It’s their choice. It takes two to negotiate and to reach an agreement. But we have nevertheless covered a considerable field. On virtually every subject, we have sought to establish new cooperation with the UK, in other forms, in a new framework, in areas where we have for 47 years worked and acted together under the Union. And that is why this partnership is unprecedented.
Both by the time of negotiation – I would remind you that it took 4 or 5 years to negotiate an even more modest agreement with Canada, or with Japan – and by the scope of the subjects dealt with. Finally, in such an agreement, it is our mandate, it is your resolution, all the parties form a cohesive whole. There is no agreement on anything, as long as there is no agreement on everything. (“Nothing is agreed until everything is agreed.”) It is therefore not surprising that in the last hours when we find also concentrated the very great difficulties of the negotiation, the most difficult and hard points. The British have set since the start of these negotiations, and this is even the reason for Brexit, a fundamental requirement: they want to regain their sovereignty. We have always respected this requirement, because it is the very purpose of Brexit.
At the same time, the British must respect the sovereignty of the Member States of the European Union. They must respect the fact that this Union of 27 Member States, which functions democratically on a voluntary basis and under the control and impulse of your Parliament, is founded on values, common policies, an economic and social foundation which is the single market, which is more of an ecosystem than a free trade area, and that we ask to preserve these values, these principles and this single market. We want open and ambitious trade and economic cooperation. But it must also be fair and equitable. Free and fair. It must therefore be based on a “level playing field”. I prefer to say fair competition, fair competition. Fair competition rules and high standards in terms of the environment, climate and social standards.
If the UK wishes to diverge in the future, that is its right. But this cannot be without consequences when it comes to having access to our market without tariffs and without quotas. With regard to fishing, the United Kingdom also wishes to regain its sovereignty, to be able to control access to its waters. As I just said, we accept it and we respect it. But if the United Kingdom wants, after a period of credible and sufficient adjustment, to be able to cut off access to its waters at any time, the European Union must also have a sovereign right to react or to compensate.
By then adjusting the conditions of access to its market for all products, and in particular for fishery products, and this is where one of the major current difficulties in negotiation is found. It would be neither fair nor acceptable for European fishermen to have only transitional rights in UK waters, which one day evaporated, while everything else in the deal – especially for UK companies – would remain stable. It would not be fair or just. These are the main points that separate us today. Of course, there are many other very important dimensions in the partnership that we have negotiated.
I am thinking of a very broad economic cooperation through an ambitious free trade agreement, unique and such as we have never offered to a third country, which includes market access without tariffs and without quotas, with credible rules in terms of level playing field. I am thinking of connectivity in air and road transport, and in energy. Or even cooperation in the field of social security. I am also thinking of our partnership on internal security, where we have a common interest in the protection of our citizens.
That is why we have already agreed on close cooperation in eight specific areas: Europol, Eurojust, Prüm, extradition, exchange of information on criminal registers as well as the freezing and confiscation of criminal records. active. And this cooperation is based on two prerequisites: respect for fundamental rights, in particular as they are enshrined in the European Convention on Human Rights, and the protection of personal data. This is where we are.
The points which remain open in these crucial hours are fundamental points for the Union. Because we are asking for nothing more than a balance between rights and obligations, and reciprocity when it comes to access to water and to markets. Nothing more, but nothing less.
While it is obvious that we want an agreement, it is just as obvious as this agreement, we will not do it at any cost. As I speak to you, I cannot tell you what will be the outcome of this final straight line of negotiations. We need to be prepared for all scenarios. And that is why you will vote today on contingency measures to prepare us for a possible no deal. On this point, I would like to thank you, thank the European Parliament for its speed and its availability to adopt these measures very quickly, which will allow their entry into force without delay, if there is no agreement, January 1 next. And tell you that we are working in parallel to quickly operationalize the new Brexit Adjustment Reserve.
On leaving you, as the President asked me yesterday, I will resume negotiations with David Frost and his team for a final attempt to find an acceptable agreement, in particular on the question of fisheries. We are not sure that we will achieve this if everyone does not make a real and concrete effort to find a compromise. Once again, I thank you for your trust and support which has never been denied since the beginning of our common journey.
This confidence is based on a method that I proposed from day one and which was supported by President Jean-Claude Juncker and then by President Ursula von der Leyen, which is that of dialogue and permanent transparency. I know there are additional requests. We are trying to answer them. There is also the general balance of this agreement which is not finished. I have tried, our services, the team of the Task Force, to be as available as possible to provide you with the elements you need throughout this long negotiation. I think that is the reason for the trust that you have always shown in me, for which I want to thank you. I know and I understand the constraints which are yours for the democratic examination to which you are entitled and which is normal. I was a member of your assembly and I was a national parliamentarian for a very long time. This democratic question is at the heart of this negotiation which must be known, detailed and approved by national parliaments and the European Parliament.
Economic actors must also have the means to appropriate it. There is a much more important stake than the only relation between the European Union and the United Kingdom; it is the European project that is in question.
Throughout this negotiation, I kept in mind three points of perspective and reference.
> The first point is peace in Ireland. It was a fundamental point, and it remains a fundamental point, for me. And that is why I thank Maros Šefčovič for the work that has been done to ensure the conditions for this stability in Ireland.
> Second point, obviously, I was mandated to defend the interests of the Union, the single market, consumers, citizens and businesses.
> Third point: beyond Brexit, the UK is a great country that we respect, a partner country, neighbor, friend, ally, with which we must have, one way or another – if not It’s not today, because we don’t come to an agreement, it would be later – a strong and extremely ambitious bond.

That is the whole point of this negotiation, hence the serious, very serious moment at which we find ourselves for its possible conclusion.

Compliments of the European Commission
The post Speech by Michel Barnier in plenary session of the European Parliament Today first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

Read More
EACC

IMF | What is Really New in Fintech

The financial industry is undergoing rapid technological change. Traditional banks face competition from online start-ups with no physical branches. Social media and other digital platforms are expanding into payments and credit. The increase in demand for digital services triggered by COVID-19 is turbo-charging this transformation. The confluence we are witnessing is driving fintech innovation and raises important questions. What are the transformative aspects of recent financial innovation that can uproot finance as we know it? Which new policy challenges will the transformation of finance bring?

Fintech’s potential to reach out to over a billion unbanked people around the world, and the changes in the financial system structure that this can induce, can be revolutionary.

Recent IMF and ECB staff research distinguishes two areas of financial innovation. One is information: new tools to collect and analyse data on customers, for example for determining creditworthiness. Another is communication: new approaches to customer relationships and the distribution of financial products. We argue that each dimension contains some transformative components.
New types of information
The most transformative information innovation is the increase in use of new types of data coming from the digital footprint of customers’ various online activities—mainly for credit-worthiness analysis.
Credit scoring using so-called hard information (income, employment time, assets and debts) is nothing new. Typically, the more data is available, the more accurate is the assessment. But this method has two problems. First, hard information tends to be “procyclical”: it boosts credit expansion in good times but exacerbates contraction during downturns.
The second and most complex problem is that certain kinds of people, like new entrepreneurs, innovators and many informal workers might not have enough hard data available. Even a well-paid expatriate moving to the United States can be caught in the conundrum of not getting a credit card for lack of credit record, and not having a credit record for lack of credit cards.
Fintech resolves the dilemma by tapping various nonfinancial data: the type of browser and hardware used to access the internet, the history of online searches and purchases. Recent research documents that, once powered by artificial intelligence and machine learning, these alternative data sources are often superior than traditional credit assessment methods, and can advance financial inclusion, by, for example, enabling more credit to informal workers and households and firms in rural areas.
New communication channels
Communication innovation is driven by the variety of digital platforms in social media, mobile communication, and online shopping that have penetrated much of consumers’ everyday lives, thus increasing their digital footprint and the available data. Platforms like Amazon, Facebook or Alibaba incorporate more and more financial services into their ecosystems, enabling the rise of new specialized providers that compete with banks in payments, asset management, and financial information provision.
Technology again boosts an existing trend. The shift from in-person bank branch visits to remote, online communication generally improves customer convenience and makes financial intermediation more cost-efficient. It also boosts geographic competition among banks, which can now service more distant customers.
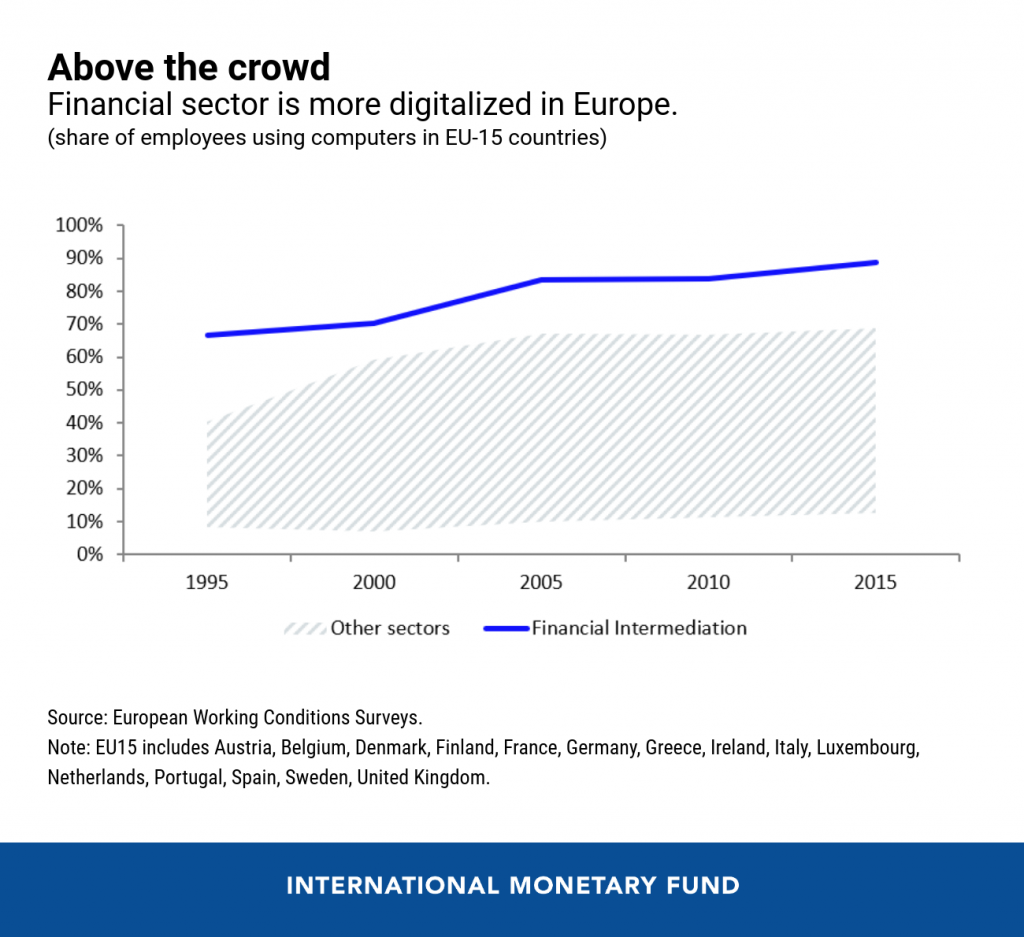
The effects of digital transformation are powerful for the financial sector, already the industry most heavily reliant on computers. That is compounded by the doubling in use of online banking having in the past two decades in the European Union’s 15 largest economies. And with usage at 50 percent on average, it still has significant room to grow.
Image courtesy of the IMF.
Policy challenges
That growth potential ensures that digital innovation in information and communication is bound to deepen even further and give rise to new priorities in several policy areas. Prudential regulation faces perhaps the most substantial challenges. Regulators need to assess the operational risks of new lending technologies and business models facing their first real-life stress test during the COVID-19 downturn.
Other risks also loom large: more cybersecurity risks (financial institutions and customers using more online services creates potential new opportunities for criminals), and regulatory arbitrage (tailoring business models to reduce regulatory oversight). To address all these challenges, regulatory agencies need to ensure that their expertise matches that of the industry—something historically difficult that may become even harder as more talent enters the financial technology sphere and the pace of innovation accelerates.
The environment for monetary policy will change too. The procyclical bias of hard information (exacerbating up- and downswings) might require central bankers to be more “countercyclical,” (i.e., potentially overcompensate with stimulating or cooling measures stronger than actual economic developments would warrant). New monetary policy transmission channels will need to be fully understood. And, as new players make banks less relevant for the financial system, central banks may need to adjust their monetary policy implementation toolbox, potentially allowing nonbanks access to liquidity lines and incorporating them in their operations.
Other critical areas include competition policy, to address the monopolistic tendencies of large digital platforms, related to network effects and the natural tendency to converge to a few large platforms; and data policies to ensure consumer privacy and efficient and safe collection, processing, and exchange of data.
Overall, while much of the technological progress in finance is evolutionary, its pace is accelerating fast. Fintech’s potential to reach out to over a billion unbanked people around the world, and the changes in the financial system structure that this can induce, can be revolutionary.
Governments should follow and carefully support the technological transition in finance. It is important to adjust policies accordingly and stay ahead of the curve.
Authors:

Arnoud Boot is professor of finance at the UNIVERSITY OF AMSTERDAM

Peter Hoffmann and Luc Laeven are economists with the ECB

Lev Ratnovski is an economist with the IMF

Compliments of the IMF.
The post IMF | What is Really New in Fintech first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

Agriculture and Fisheries Council, 15-16 December 2020

Main results – Fisheries
2021 fishing opportunities
Ministers agreed the catch limits for over 200 commercial fish stocks in the Atlantic, the North Sea, the Mediterranean and the Black Sea for 2021. More than 100 of these stocks in the Atlantic and North Sea have been co-managed with the UK during the last decades. Given the ongoing EU-UK negotiations on their future relationship, ministers agreed to set provisional quotas for the fish stocks shared with the UK. The provisional quotas are designed to ensure the continuation of sustainable fishing in the concerned areas until consultations with the UK are concluded. A similar approach was agreed for the stocks co-managed with Norway.

The agreements reached during the last two days showcase how we can go beyond set expectations. It was not easy to agree on fish catch limits in the context of Brexit and COVID-19 but I firmly believe that we now have the best possible plan in place. It was challenging to reconcile the many divergent views on front-of-pack nutritional labelling but I am convinced we sent a solid political message supported by the vast majority of member states. And we also received overwhelming support for an EU-wide animal welfare label. Setting and achieving ambitious targets has been our guiding principle throughout the last six months and I think that another concrete example is the Council’s position for a more environmentally friendly common agricultural policy. I am proud of our achievements and I am confident that the incoming Portuguese presidency will follow up on them.
Julia Klöckner, Germany’s Federal Minister of Food and Agriculture and the president of the Council

Compliments of the Council of the EU.
The post Agriculture and Fisheries Council, 15-16 December 2020 first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

Council of the EU | Multiannual financial framework for 2021-2027 adopted

Following the European Parliament’s consent yesterday, the Council has adopted the regulation laying down the EU’s multiannual financial framework for 2021-2027.
The regulation provides for a long-term budget of €1 074.3 billion for the EU27 in 2018 prices, including the integration of the European Development Fund. Together with the Next Generation EU recovery instrument of €750 billion, it will allow the EU to provide an unprecedented €1.8 trillion of funding over the coming years to support recovery from the COVID-19 pandemic and the EU’s long-term priorities across different policy areas.
The next long-term budget will cover seven spending areas. It will provide the framework for the funding of almost 40 EU spending programmes in the next seven-year period.
Key features
Under the next multiannual financial framework, EU funding will be geared towards new and reinforced priorities across the EU’s policy areas, including green and digital transitions. Cohesion policy and the common agricultural policy will continue to receive significant funding and undergo modernisation to ensure that they best contribute to Europe’s economic recovery and the EU’s green and digital objectives.
In total, around a third of EU spending under the long-term budget will contribute to new and reinforced policy areas. Funding under the new recovery instrument will help EU member states to tackle the consequences of the COVID-19 crisis, thereby strengthening modernisation and resilience.
The EU will be spending €132.8 billion in the spending area of single market, innovation and digital and €377.8 billion on cohesion, resilience and values. These amounts will increase to €143.4 billion and €1.099.7 billion, respectively, with additional funding from the Next Generation EU, including loans to member states. A further €356.4 billion of funding will go to the area of natural resources and environment (€373.9 billion with the contribution from the Next Generation EU).
Spending in the areas of migration and border management will amount to €22.7 billion over the next seven years, and €13.2 billion will be spent in the fields of security and defence. Funding for the EU neighbourhood and the world will amount to €98.4 billion.
New and reinforced programmes
In order to support the digital transition, a new funding programme, Digital Europe, is established to promote the large-scale roll-out and uptake of key digital technologies such as artificial intelligence applications and state-of-the-art cybersecurity tools. The digital strand of the Connecting Europe Facility will also get a significant boost in funding.
A new EU4Health programme will provide a strong basis for EU action in the health field based on lessons learned during the COVID-19 pandemic.
In the field of research and innovation, the Horizon Europe programme will benefit from a significant increase once funding on the basis of the EU’s recovery instrument becomes available.
Support for migration and border management has also been considerably reinforced, including to fund up to 10 000 border guards at the disposal of the European Border and Coast Guard Agency by 2027. In the field of security and defence, a new European Defence Fund will be established to promote the competitiveness, efficiency and innovation capacity of the EU’s defence, technological and industrial base.
Programmes for young people, such as Erasmus+ and the European Solidarity Corps, will also be strengthened, with the Erasmus+ programme expected to triple the number of participants in the course of the new multiannual financial framework.
To support the most vulnerable carbon intensive regions in their transition towards a climate-neutral economy, a new Just Transition Fund is created. It will receive funding under both the next long-term budget and the EU recovery instrument.
Next steps
Most of the sectoral EU funding programmes are expected to be adopted in early 2021 and will apply retroactively from the beginning of 2021.
For the implementation of the Next Generation EU recovery instrument, the EU’s own resources decision will need to be approved in all member states in accordance with their constitutional requirements. Under the decision, the Commission will be authorised, on an exceptional basis, to borrow up to €750 billion in 2018 prices on the capital markets to address the consequences of the COVID-19 crisis.
Most of this funding will be channelled through a €672.5 billion Recovery and Resilience Facility which will support public investments and reforms in member states through grants and loans, helping them to address the economic and social impact of the COVID-19 pandemic, as well as the challenges posed by the green and digital transitions.
Compliments of the Council of the European Union.
The post Council of the EU | Multiannual financial framework for 2021-2027 adopted first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

Eurosystem staff macroeconomic projections for the euro area, December 2020

How will our economy evolve over the next few years? The ECB and Eurosystem staff produce quarterly macroeconomic projections. These aim to assess how the economy in the euro area will develop.
Today we again published a baseline scenario as well as two alternative scenarios, taking into consideration the high uncertainty surrounding the impact of the coronavirus on the eurozone economic outlook
Overview
Following a drop of 15.0% in the first half of 2020, euro area real GDP rebounded by 12.5% in the third quarter, which was a significantly stronger increase than expected in the September 2020 ECB staff projections. Nevertheless, the recent intensification of containment measures in response to a strong resurgence of coronavirus (COVID-19) infections across countries is expected to result in another decline in activity in the fourth quarter. Activity is also expected to be subdued in the first quarter of 2021. Despite this near-term setback, positive news on the development of vaccines gives cause for greater confidence in the assumption of a gradual resolution of the health crisis throughout 2021 and in early 2022. This, together with substantial support from monetary and fiscal policies – partly related to the Next Generation EU (NGEU) package – and the ongoing recovery in foreign demand, should allow a firm rebound during the course of 2021, with real GDP expected to return to its pre-crisis level by mid-2022. Thus, even though the near-term outlook has deteriorated, the path of euro area GDP from 2022 is expected to be broadly similar to that foreseen in the September 2020 ECB staff projections. As the policy measures are expected to be successful in averting large financial amplification effects and limiting the economic scars of the crisis, real GDP in 2023 is expected to stand 2½% above its 2019 pre-crisis level.
As regards inflation, upward base effects associated with the earlier slump in oil prices and upward impacts from the reversal of the VAT rate cut in Germany imply a rebound in headline inflation in 2021. HICP inflation excluding energy and food is expected to show a much more muted recovery in 2021 as broad-based disinflationary effects from weak demand, especially across the services sectors, dominate upward cost pressures from supply side constraints. Over the medium term headline inflation is expected to gradually increase, mainly reflecting a slight rise in the contribution of HICP inflation excluding energy and food which, however, is seen to remain rather subdued, at 1.2%, in 2023. Overall, the baseline foresees HICP inflation rebounding from 0.2% in 2020 to 1.0% in 2021 and then gradually increasing further to 1.1% in 2022 and 1.4% in 2023. Compared with the September 2020 ECB staff projections, HICP inflation has been revised down for 2020 and 2022, on account of weaker incoming data for HICP inflation excluding energy and food and a downward reassessment of inflationary pressures since the previous projections in the context of abundant but diminishing slack in the goods and labour markets.[1]
In view of the continued significant uncertainty regarding the evolution of the pandemic, potential medical solutions (including the distribution and take-up of vaccines) and the degree of economic scarring, two alternative scenarios have again been prepared. The mild scenario sees a more successful containment of the virus, a swift roll-out of vaccines and limited scarring. In this scenario, real GDP would rebound by 6.0% next year, reaching pre-crisis levels as early as the end of 2021, with inflation rising to 1.5% in 2023. In contrast, the severe scenario, with a delayed resolution of the health crisis and substantial and permanent losses to economic potential, would imply a marginal increase in 2021 in real GDP, which would stand in 2023 still almost 2% below its pre-crisis levels, with inflation at only 0.8% in that year.
Read the  FULL REPORT HERE.
Compliments of the European Central Bank.
The post Eurosystem staff macroeconomic projections for the euro area, December 2020 first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

Coronavirus response: Tackling non-performing loans (NPLs) to enable banks to support EU households and businesses

The European Commission has today presented a strategy to prevent a future build-up of non-performing loans (NPLs) across the European Union, as a result of the coronavirus crisis. The strategy aims to ensure that EU households and businesses continue to have access to the funding they need throughout the crisis.
Banks have a crucial role to play in mitigating the effects of the coronavirus crisis, by maintaining the financing of the economy. This is key in order to support the EU’s economic recovery. Given the impact coronavirus has had on the EU’s economy, the volume of NPLs is expected to rise across the EU, although the timing and magnitude of this increase is still uncertain. Depending on how quickly the EU’s economy recovers from the coronavirus crisis, banks’ asset quality – and in turn, their lending capacity – could deteriorate.
Valdis Dombrovskis, Executive Vice-President for an Economy that Works for People, said: “History shows us that it is best to tackle non-performing loans early and decisively, especially if we want banks to continue supporting businesses and households. We are taking preventive and coordinated action now. Today’s strategy will help contribute to Europe’s swift and sustainable recovery by helping banks to offload these loans from their balance sheets and keep credit flowing.”
Mairead McGuinness, Commissioner responsible for financial services, financial stability and the Capital Markets Union, said: “Many firms and households have come under significant financial pressure due to the pandemic. Making sure that European citizens and businesses continue to receive support from their banks is a top priority for the Commission. Today we put forward a set of measures that, while ensuring borrower protection, can help prevent a rise in NPLs similar to the one after the last financial crisis.”
In order to give Member States and the financial sector the necessary tools to address a rise of NPLs in the EU’s banking sector early on, the Commission is proposing a series of actions with four main goals:

Further developing secondary markets for distressed assets: This will allow banks to move NPLs off their balance sheets, while ensuring further strengthened protection for debtors. A key step in this process would be the adoption of the Commission’s proposal on credit servicers and credit purchasers which is currently being discussed by the European Parliament and the Council. These rules would reinforce debtor protection on secondary markets. The Commission sees merit in the establishment of a central electronic data hub at EU level in order to enhance market transparency. Such a hub would act as a data repository underpinning the NPL market in order to allow a better exchange of information between all actors involved (credit sellers, credit purchasers, credit servicers, asset management companies (AMCs) and private NPL platforms) so that NPLs are dealt with in an effective manner. On the basis of a public consultation, the Commission would explore several alternatives for establishing a data hub at European level and determine the best way forward. One of the options could be to establish the data hub by extending the remit of the existing European DataWarehouse (ED).

Reform the EU’s corporate insolvency and debt recovery legislation: This will help converge the various insolvency frameworks across the EU, while maintaining high standards of consumer protection. More convergent insolvency procedures would increase legal certainty and speed up the recovery of value for the benefit of both creditor and the debtor. The Commission urges the Parliament and Council to reach an agreement swiftly on the legislative proposal for minimum harmonisation rules on accelerated extrajudicial collateral enforcement, which the Commission proposed in 2018.

Support the establishment and cooperation of national asset management companies (AMCs) at EU level: Asset management companies are vehicles that provide relief to banks that are struggling by enabling them to remove NPLs from their balance sheets. This helps banks re-focus on lending to viable firms and households instead of managing NPLs. The Commission stands ready to support Member States in setting up national AMCs – if they wish to do so – and would explore how cooperation could be fostered by establishing an EU network of national AMCs. While national AMCs are valuable because they benefit from domestic expertise, an EU network of national AMCs could enable national entities to exchange best practices, enforce data and transparency standards and better coordinate actions. The network of AMCs could furthermore use the data hub to coordinate and cooperate with each other in order to share information on investors, debtors and servicers. Accessing information on NPL markets will require that all relevant data protection rules regarding debtors are respected.

Precautionary measures: While the EU’s banking sector is overall in a much sounder position than after the financial crisis, Member States continue to have varying economic policy responses. Given the special circumstances of the current health crisis, authorities have the possibility to implement precautionary public support measures, where needed, to ensure the continued funding of the real economy under the EU’s Bank Recovery and Resolution Directive and State aid frameworks

Background
The Commission’s NPL strategy proposed today builds upon a consistent set of previously implemented measures. In July 2017, finance ministers in the ECOFIN agreed on a first Action Plan to tackle NPLs.
In line with the ECOFIN Action Plan, the Commission announced in its Communication on completing the Banking Union of October 2017 a comprehensive package of measures to reduce the level of NPLs in the EU. In March 2018, the Commission presented its package of measures to tackle high NPL ratios.
The proposed measures included the NPL backstop, which required banks to build minimum loss coverage levels for newly originated loans, a proposal for a Directive on credit servicers, credit purchasers and for the recovery of collateral and the blueprint for the set-up of national asset management companies. To mitigate the impact of the coronavirus crisis, the Commission’s Banking Package from April 2020 has implemented targeted “quick fix” amendments to the EU’s banking prudential rules. In addition, the Capital Markets Recovery Package, adopted in July 2020, proposed targeted changes to capital market rules to encourage greater investments in the economy, allow for the rapid re-capitalisation of companies and increase banks’ capacity to finance the recovery.
The Recovery and Resilience Facility (RRF) will also provide substantial support to reforms aimed at improving insolvency, judicial and administrative frameworks and underpinning efficient NPL resolution.
The post Coronavirus response: Tackling non-performing loans (NPLs) to enable banks to support EU households and businesses first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.