EACC

ECB Interview | A worldwide phenomenon

Interview with Philip R. Lane, Member of the Executive Board of the ECB, conducted by Markus Zydra on 26 January and published on 1 February 2021 as a shortened version in Süddeutsche Zeitung |

Mr Lane, the ECB aspires to be closer to the people. Distributing helicopter money would be a good way to go about that. Why does the ECB prefer to channel its support to banks rather than directly to citizens? Is this a taboo topic?
Of course we track the academic and the wider debate. But at the ECB we should focus on the policies that we are actually pursuing and the options that are on the table, and not the outer reaches of monetary theory.
Is the idea of helicopter money off the table for good?
It’s not particularly productive to engage in hypothetical discussions, but let me come back to the basic issue. We expect economic growth and inflation in the euro area to return to their pre-pandemic levels before the end of this year. Prior to the pandemic, inflation was hovering around 1 per cent, but with a dynamic where inflation would, over time, rise closer towards 2 per cent, it was not a crisis situation. If economic developments are reasonably stable and moderate, monetary policy should be similarly stable and moderate.
The ECB repeatedly emphasises that it would be prepared to loosen monetary policy even more in an emergency. What options are still open to you? Purchases of equities or bank bonds or something like that?
The ECB and the Eurosystem have many excellent monetary economists, so everything is considered at some level. But these measures are not part of our current toolbox. Our active toolbox is a combination of our short term rates, asset purchases, targeted lending and our forward guidance, which is not only about explaining today’s policy, but also about how we would respond to unfolding conditions in the future.
The ECB is working on a new strategy, one aspect of which is communication. The public expects you to better explain your decisions. Rightly so?
We are living in extrordinary times. Compared to 15 years ago, the role of central banks is very different now to perhaps its more traditional role. For example we are very active in quantitative easing and targeted lending to banks. All of this needs explaining. And the way people absorb information is also very different now, with the use of social media and a greater focus on visuals, for example. Through our “ECB Listens” event, for instance, we have received thousands of comments. It is clear that we need to explain our decisions to people clearly and in the simplest possible terms.
So let’s give it a try: many Germans take a poor view of the ECB’s zero rate policy. Convince the critics in simple words.
Low interest rates are a global development. We are experiencing a major structural change in the global economy. People want to save more but the global demand for investment is low. By comparison, the role of the central bank is secondary. Would it be that helpful to increase interest rates in this environment? Hardly, because it would make the situation worse, leading to more unemployment and less growth.
Is there no simpler way of explaining monetary policy?
I know of some comic strip-type presentations which attempt to do just that. We try as hard as we can to simplify, but we always need to be careful that simplification is not misleading. The most important factor is trust in the ECB: as a driver, I don’t need to know exactly how the engine operates. I need to trust the car dealer and the mechanic to do a good job. The same goes for monetary policy. Not everybody needs to be a financial expert.
Trust in the ECB has declined considerably over the past few years. That’s a bad thing for a central bank which sees itself as providing a service for citizens.
That’s true. The surveys show that people have more trust in the euro than they do in the ECB. This is a clear signal that we need to better explain our task and policies. Perhaps then the level of trust in us would go up.
Some say central banks are plumbers. Are you a plumber?
There are two dimensions to this. The first is: when we talk about the economy and interest rates, there is a whole machinery behind how the central bank connects the financial system and that really is similar to plumbing. The second is: Keynes once referred to economists as dentists, which is maybe similar to a plumber in some respect. People go to the dentist or call a plumber when they need one. Perhaps the same applies to central bankers.
Was it your childhood dream to become a central banker?
I grew up in Ireland in the 1980s, a time when the economy was in a bad state and unemployment was high. That was reinforced by the global financial crisis, during which Ireland suffered a lot from the boom-and-bust cycle. It was clear to me that economic policy had an important role to play in preventing these terrible outcomes. But the reason I studied economics was not just to understand the world, but maybe where I can, to play my part in making sure that economic policy, and in my particular role monetary policy, was supporting society and the economy. My move from academia to the Central Bank of Ireland, and now to the ECB, was very much in line with that.
The ECB has become the white knight in the euro area. Would you agree that without the ECB, the euro area governments would be incapable of carrying the debt burden?
Actually, over the past year, the far more important aspect has been the joint actions of European governments, especially the Next Generation EU facility. The major issue has been Europe standing together. That said, central banks are playing an important supporting role. But the reason for the low interest rates and our bond purchases are the low inflation pressures, which is also true in the United States and in the United Kingdom. We need to have a very supportive monetary policy, because without that we’re not going to maintain stable prices and we’re not going to bolster a recovery.
Still, the central bank is now the largest creditor of the euro area countries. Is there an upper limit to that support?
It’s important to keep in mind that sovereign bond purchasing is a worldwide phenomenon. There are increasingly high holdings by the Federal Reserve, Bank of England, Bank of Japan and other central banks. We now hold around 30% of all sovereign debt outstanding in the euro area. And we have safeguards in place. What we do is driven by the price stability mandate and asset purchase programmes are only required when inflation pressures are too weak and interest rates are already very low.
European Commission surveys regularly show that people’s perception of the inflation rate is much higher than the official figure. Does this perceived level of inflation undermine the ECB’s credibility? After all, the ECB bases its monetary policy on the inflation rate.
It is inevitable that there are different perceptions of price changes in the general population. We look at whether our monetary policy decisions move perceptions of the inflation rate in the right direction. If anything, the fact that people across Europe perceive the inflation rate in different ways suggests that prices are stable overall. In countries with really high inflation rates, everyone is acutely aware of just how much the prices have increased.
Some economists have called for the ECB to cancel sovereign debt at some point. What is your response to that?
The simple answer is: no, we cannot do that, because the Treaties don’t allow sovereign debt cancellation. But, regardless of the legal aspects, cancelling debt would not be a good idea in general, and the debate is a digression. We are seeing that governments are able to issue a lot of debt and to do it at low interest rates in a sustainable way.
The ECB and European politicians have been speaking with one voice throughout the coronavirus crisis. They coordinate their actions, cooperate over support measures. Isn’t this closeness dangerous?
We all have a problem to solve. I don’t need to speak to a finance minister to discover that we need a loose monetary policy. Equally, every politician knows that governments need to invest more. So it is quite obvious that in this situation monetary policy and fiscal policy are pushing in the same direction. But I think life is made easier for everyone by good communication between the Eurogroup and the ECB so that they have a good understanding of our policy and we have a good understanding of what the finance ministers are up to. But this does not affect our independence. Indeed, the ECB is the most independent central bank. And there are plenty of examples where the ECB has tightened policy even if it might not have been convenient for governments.
The ECB wants to develop a “green” monetary policy. Environmental protection is a job for the politicians, not the central bank.
All sectors of the economy have to make sure that the way they operate is green and consistent with carbon transition, and that applies to the central bank as well. But the role of the central bank in the financial system means we can be a leader and a catalyst.
What is your relationship with ECB President Christine Lagarde like?
We have a very good strong relationship. She is an extremely impressive leader of the ECB, with decades of leadership experience at the IMF, running a global law firm, and of course her time in the French government. Leadership is also about making sure that the senior team works well, and there is a strong team spirit at the ECB.
For a while, the two of you were struggling with communicating your decisions. Ms Lagarde presented the decisions at the press conference and a day later you wrote your own blog. Are you better placed to explain the technical details than Ms Lagarde?
It was not my intention to give that impression, and it’s wrong. Our monetary policy is a team effort – I, as chief economist, work in close coordination and agreement with the President. The intention was to reinforce and support the communication of our monetary policy decisions across multiple channels. But perhaps it was all a bit too much. I stopped doing the blog on the day after the press conference in the autumn, because if it led to perceptions of difference, then it was problematic.
The ECB’s working language is English, and you are the only member of the Executive Board who is a native speaker. What is it like?
People at the ECB have very good English. Of course, it makes my life easier because it’s my primary language. That said, my Irish accent maybe adds a facet to the diversity of spoken English at the ECB!

Compliments of the European Central Bank.
The post ECB Interview | A worldwide phenomenon first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.
EACC

Vaccines: contract between European Commission and AstraZeneca now published

Following the renewed request from the European Commission on 27 January 2021, pharmaceutical company AstraZeneca has agreed to publish the redacted contract signed between the two parties on 27 August 2020.
The Commission welcomes the company’s commitment towards more transparency in its participation in the rollout of the EU Vaccines Strategy.
Transparency and accountability are important to help build the trust of European citizens and to make sure that they can rely on the effectiveness and safety of the vaccines purchased at the EU level.
The Commission hopes to be able to publish all contracts under the Advance Purchase Agreements in the near future.
The contract published today contains redacted parts pertaining to confidential information such as details of invoices. The AstraZeneca contract is the second one to be published, after CureVac has agreed to publish the Advance Purchase Agreement with the European Commission.
Background
For the Commission the protection of public health and securing the best possible agreements with companies so that vaccines are affordable, safe and efficacious is crucial.
The contract the European Commission negotiated together with the EU Member States was approved on 14 August and entered into force on 27 August. It is financed by the Emergency Support Instrument.
Through the contract, all Member States are able to purchase 300 million doses of the AstraZeneca vaccine, with an option for a further 100 million doses, to be distributed on a population-based pro-rata basis. The contract also allows the Member States to donate their vaccine doses to lower and middle income countries or to re-direct them to other European countries.
Compliments of the European Commission.
The post Vaccines: contract between European Commission and AstraZeneca now published first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

EUIPO | Payment of fees with credit card: Strong Customer Authentication required

Recently, some of our users have been unable to complete their fee payments with credit/debit cards due to non-compliance with the Strong Customer Authentication (SCA) requirements. To avoid this situation, we recommend that users contact their bank to ensure that their credit/debit cards meet the requirements to complete secure payments.
The SCA is a requirement of the second Payment Services Directive (PSD2) within the European Economic Area. It is an authentication process that validates the identity of the user of a payment service or payment transaction. The SCA requirement makes it easier and safer for consumers to pay for goods and services online and helps fight fraud.
This requirement adds extra layers of security to electronic payments and ensures that they are verified with multi-factor authentication. To make any electronic payment, a combination of two of the following elements is needed:

Knowledge: something only the user knows, e.g. a password or a PIN code
Possession: something only the user possesses, e.g. a mobile phone, and
Inherence: something the user is, e.g. the use of a fingerprint or facial recognition

More information can be found in the FAQs on the European Commission’s PSD2 webpage.
Compliments of the European Union Intellectual Property Office.
The post EUIPO | Payment of fees with credit card: Strong Customer Authentication required first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

EU Commission puts in place transparency and authorisation mechanism for exports of COVID-19 vaccines

In an effort to ensure timely access to COVID-19 vaccines for all EU citizens and to tackle the current lack of transparency of vaccine exports outside the EU, the Commission has today put in place a measure requiring that such exports are subject to an authorisation by Member States.
President of the European Commission Ursula von der Leyen said: “The pandemic is having devastating effects in Europe and all around the world. Protecting the health of our citizens remains our utmost priority, and we must put in place the necessary measures to ensure we achieve this. This transparency and authorisation mechanism is temporary, and we will of course continue to uphold our commitments towards low and middle income countries.”
Executive Vice-President and Commissioner for Trade Valdis Dombrovskis said: “This time-limited and targeted system covers only those COVID-19 vaccines that were agreed by Advanced Purchase Agreements with the EU. The aim is to provide greater clarity on vaccine production in the EU and their exports – this transparency has been lacking and is vital at this time. This mechanism includes a wide range of exemptions to fully honour our humanitarian aid commitments and protect vaccines deliveries to our neighbourhood, and to countries in need covered by the COVAX-facility.”
Commissioner for Health and Food Safety Stella Kyriakides said: “For the best part of the last year we worked hard to get Advance Purchase Agreements with vaccine producers to bring vaccines to the citizens, in Europe and beyond. We gave upfront funding to companies to build the necessary manufacturing capacity to produce vaccines, so deliveries can start as soon as they are authorised. We now need transparency on where the vaccines we secured are going and ensure that they reach our citizens. We are accountable towards the European citizens and taxpayers – that is a key principle for us.”
The Commission has invested large amounts in the development of the production capacity of vaccine developers in the EU. This with the aim to ensure quicker delivery of vaccines to the European citizens, support planning and vaccination strategies with the ultimate goal to protect public health. It is therefore reasonable for the EU to monitor how the funds disbursed under the Advance Purchase Agreements (APA) have been used, especially in a context of potential shortages of essential COVID-19 vaccines. The main purpose is to offer public transparency to the European citizens. The transparency and authorisation system will require companies to notify the Member State authorities about the intention to export vaccines produced in the European Union.
The export authorisation scheme
This implementing act, adopted by urgency procedure and published today, provides for authorisations of exports outside the EU of COVID-19 vaccines until the end of March 2021. This scheme only applies to exports from companies with whom the EU has concluded Advance Purchased Agreements.
Based on the previous experience with a similar measure on personal protective equipment in Spring 2020, the Commission will assist Member States in setting up the relevant mechanism to ensure a smooth and coordinated implementation of the regulation.
This measure is targeted, proportionate, transparent and temporary. It is fully consistent with the EU’s international commitment under the World Trade Organization and the G20, and in line with what the EU has proposed in the context of the WTO trade and health initiative. Committed to international solidarity, the EU excluded from this scheme vaccine supplies for humanitarian aid or destined to countries under the COVAX facility, as well as our neighbourhood.
About the EU’s vaccine strategy
The European Commission presented on 17 June a European strategy to accelerate the development, manufacturing and deployment of effective and safe vaccines against COVID-19. In return for the right to buy a specified number of vaccine doses in a given timeframe, the Commission finances part of the upfront costs faced by vaccines producers in the form of Advance Purchase Agreements (APA). Funding provided is considered as a down-payment on the vaccines that will actually be purchased by Member States. The APA is therefore a de-risk investment upfront against a binding commitment from the company to pre-produce, even before it gets marketing authorisation. This should allow for a quick and steady delivery as soon as the authorisation has been granted.
Compliments of the European Commission.
The post EU Commission puts in place transparency and authorisation mechanism for exports of COVID-19 vaccines first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

ESMA consults on changes to CRA supervisory fees

The European Securities and Markets Authority (ESMA), the EU’s securities markets regulator, today launches a public consultation on the revision of the Delegated Regulation regarding fees charged to CRAs.

The consultation paper contains proposals which ensure that the supervisory fees charged to credit rating agencies (CRAs) reflect the costs of registration, certification and on-going supervision whilst remaining proportionate to CRAs’ turnover.
ESMA’s main proposals are to charge:

A single registration fee of €45,000;
Annual supervisory fees of €20,000 to registered CRAs with annual revenues of between €1 million and €10 million;
An annual endorsement fee of €20,000 to all CRAs endorsing credit ratings for use in the EU; and
Annual fees to all certified CRAs.

ESMA’s proposals are also intended to align the approach to collecting CRA supervisory fees with the approach taken under ESMA’s other supervisory mandates so that the fee collection process becomes easier to administer in future.
The aim of this consultation is to gather stakeholder views on the appropriateness of the proposals and their likely impact. These views will help ESMA prepare Technical Advice for the European Commission on changes to the Delegated Regulation on fees charged to CRAs.
ESMA seeks feedback on its proposals from CRAs and their auditors, firms considering registration as Credit Rating Agencies and firms applying for certification status. The consultation paper may also be of interest to trade associations representing CRAs and users of credit ratings.
Next steps
The public consultation is open until 15 March 2021. Responses should be submitted using the form available on ESMA’s website. The responses to the Consultation Paper will inform ESMA’s Technical Advice to the European Commission on the revision of the Delegated Regulation, by 31 June 2021.
Compliments of the European Securities and Markets Authority.

The post ESMA consults on changes to CRA supervisory fees first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

ECB Speech | The sovereign-bank-corporate nexus: A virtuous or a vicious circle?

Speech by Isabel Schnabel, Member of the Executive Board of the ECB, at the LSE conference on “Financial Cycles, Risk, Macroeconomic Causes and Consequences” | Frankfurt am Main, 28 January 2021 |
One year after the first cases were reported in Europe, the coronavirus (COVID-19) pandemic continues to take a tragic human toll and to pose enormous challenges to workers, firms, the financial system and policymakers in the euro area.[1]
Without the forceful responses of fiscal, monetary and prudential authorities the economic and social costs of this crisis would have been significantly higher. Governments, in particular, have stabilised aggregate demand and incomes by absorbing economic and financial risks of the private sector as the crisis unfolded.
Through the generous issuance of guarantee schemes, governments secured a continuous flow of credit to firms, which supported economic growth and protected financial stability. Monetary policy has complemented these efforts by providing ample liquidity and restoring favourable financing conditions.
As a consequence, the policy response to the pandemic has visibly intensified the interdependencies between sovereigns, banks and firms. It has created a “sovereign-bank-corporate” nexus.[2]
In my remarks today, I will argue that the extent to which such interdependencies may create challenges in the future depends, to a large extent, on the types of feedback loops they create. Broad fiscal and monetary policy support today minimise the realisation of contingent liabilities in the future, and thus limit the scarring effects of the pandemic on the economy, creating a virtuous circle.
So, contrary to the vicious “sovereign-bank” nexus[3] that plagued the euro area throughout most of the last decade, the current nexus, if managed properly, can be an engine for a faster recovery, which also supports the ECB’s price stability mandate.
A virtuous circle between sovereigns, banks and corporates
At the onset of the pandemic, the strict lockdown measures hit large parts of the corporate sector hard, raising its vulnerability to levels last seen during the global financial crisis (Chart 1). Many firms saw their revenues collapse and were facing acute liquidity shortages that threatened to turn into solvency problems.

Chart 1
Composite indicator of corporate vulnerabilities and underlying driving factors in the euro areaZ-scores

Sources: Eurostat and ECB calculations.Notes: The composite measure is based on a broad set of indicators along five dimensions: debt service capacity (measured by the interest coverage ratio, corporate savings and revenue generation); leverage/indebtedness (debt-to-equity, net debt-to-EBIT and gross debt-to-income ratios); financing/rollover (ratio of short-term debt to long-term debt; quick ratio (defined as current financial assets divided by current liabilities); overall cost of debt financing and credit impulse (defined as the change in new credit issued as a percentage of GDP)); profitability (return on assets, profit margin and market-to-book value ratio) and activity (sales growth, trade creditors ratio and change in accounts receivable turnover). Except for the overall cost of debt financing and GDP, all indicators are based on data from the ECB’s quarterly sector accounts. The overall cost of debt financing indicator is calculated as a weighted average of the costs of bank borrowing and market-based debt, based on their respective amounts outstanding.

In response to these developments, governments swiftly launched broad-based measures to support households and firms, including job retention schemes, direct transfers, tax cuts and deferrals, as well as loan guarantees (Chart 2).
At the same time, the ECB supported bank lending to firms by providing ample liquidity at favourable conditions, while prudential authorities took comprehensive supervisory relief measures. The decisive policy response allowed firms to draw down their credit lines in order to finance their working capital, leading to an unprecedented increase in bank lending in the spring of 2020.

Chart 2
Loan guarantees and remaining envelopes relative to sovereign debt in 2020 in selected euro area countriesPercentages of GDP and percentages of outstanding sovereign debt

Sources: National authorities and ECB calculations.Notes: Data are based on national sources and cover guarantees committed or announced until the end of 2020. “Remaining envelope” denotes announced envelopes of guarantees that have not yet been committed.

Together, these measures helped prevent an abrupt contraction of credit to firms and a wave of corporate defaults, and protected banks’ profitability and balance sheets. Thereby, they created a virtuous circle between sovereigns, banks and corporates (Chart 3).
The wide-ranging policy support protected employment and stabilised aggregate demand, thereby substantially reducing the depth of the recession and the risk of scarring effects in the long run.

Chart 3
A virtuous circle between sovereigns, banks and corporates

Source: ECB.

At the same time, the pandemic sparked a marked increase in both sovereign and corporate debt levels (Chart 4).

Chart 4
Indebtedness of the general government and the non-financial corporate sector across the euro areapercentages of GDP

Sources: ECB and ECB calculations.Notes: Non-financial corporate sector debt figures are on a consolidated basis. The red horizontal line represents the estimated MIP benchmark of 76% of GDP for consolidated non-financial corporate debt, whereby the 133% of GDP MIP benchmark for fully consolidated non-financial private sector debt is split between households and firms based on their average past shares in the stock of euro area non-financial private debt. Consolidated non-financial corporate debt figures also include cross-border inter-company loans, which tend to account for a significant part of debt in countries where a large number of foreign entities, often multinational groups, are located (e.g. Belgium, Cyprus, Ireland, Luxembourg and the Netherlands). The red vertical line represents the threshold of 60% of GDP for sovereign debt as defined in the excessive deficit procedure under the Maastricht Treaty.

In addition to rising debt levels, the interlinkages between sovereigns, banks and firms resulting from the broad-based fiscal support have grown.
On the one hand, the sensitivity of public finances to future corporate and financial sector developments has increased, beyond the traditional impact of automatic stabilisers during a recession, such as lower tax revenues and higher social security expenses.[4]
On the other hand, banks and corporates have become more dependent on government support. Only recently, possibly in view of the potential phasing out of fiscal support measures, changes in banks’ risk perceptions have resulted in tighter credit standards for firms, according to our latest Bank Lending Survey (Chart 5).[5]

Chart 5Bank lending to euro area non-financial corporations and bank credit standardsAnnual percentage changes; weighted index

Sources: ECB (BSI statistics, Bank Lending Survey) and ECB calculations.

The sovereign-bank-corporate nexus – this time is different
But the nature of these interdependencies differs fundamentally from previous crises.
Most notably, this time, the crisis did not originate in the financial sector, as in the global financial crisis[6], but in the real economy, and public support was granted to firms, not banks.
Moreover, the pandemic has not raised concerns of moral hazard. While the global financial crisis resulted in the mutualisation of risks that should have been borne by the ultimate risk-takers, government support during the pandemic has protected the economy in the face of an exogenous shock that was not caused by excessive risk-taking.
In the pandemic crisis, broad-based fiscal support has been both necessary and proportionate to mitigate the economic and social costs of the containment measures for large parts of society.
At the same time, with the Banking Union still incomplete, the pandemic has once again exposed old vulnerabilities. For example, by absorbing some of the newly issued sovereign debt, banks have increased their exposures to the general government in many euro area countries, reinforcing the links between sovereigns and banks (Chart 6).[7]

Chart 6
Euro area bank exposures to domestic sovereign debt securities relative to total assetsJan. 2007-Sep. 2020, observed; end-2022, potential; percentage of total assets

Sources: ECB (BSI and GFS statistics, and macroeconomic projections).Notes: The dots are based on a simple projection of potential increase based on the average share of domestic sovereign debt securities held by euro area banks from March to September 2020 and public debt projected from 2020 to 2022.

In fact, bank and sovereign credit ratings remain highly correlated in the euro area (Chart 7).[8]

Chart 7
Issuer ratings of sovereigns and banks in the euro areaRating buckets

Sources: Fitch Ratings, Moody’s, Standard & Poor’s, DBRS and ECB calculations.Notes: The rating shown represents the median of the long-term issuer ratings assigned by Standard & Poor’s, Moody’s, Fitch Ratings and DBRS. The bubble size indicates the combined debt of sovereigns and banks (debt securities issued) in a country as a share of the euro area total.

Given that corporate health has become more dependent on the domestic sovereign’s fiscal support, the withdrawal of government support could lead to cliff effects, giving rise to financial instabilities.[9]
It could trigger corporate defaults, a rapid rise in non-performing loans (NPLs) and tighter financing conditions. This, in turn, could cause problems in the banking sector, deepening the recession and further eroding the sovereign’s revenues, while requiring even more guarantees and higher public debt, putting pressure on the sovereign’s credit standing.
In other words, the interlinkages between banks, sovereigns and corporates, which were crucial for stabilising the economic and financial situation during the pandemic, could turn into a vicious circle, giving rise to destabilising feedback loops (Chart 8).

Chart 8
A vicious circle between sovereigns, banks and corporates

Source: ECB.

Policy implications of the sovereign-bank-corporate nexus
The extent to which these interlinkages may give rise to vulnerabilities in the future depends on two broad conditions.
First, it depends on the effectiveness of the wide-ranging policy support that is currently in place. An accelerating pace of vaccinations, favourable financing conditions and significant pent-up demand in the form of large savings can prepare the ground for a strong rebound in economic activity in the second half of this year. This would relieve stretched corporate balance sheets.
The responsible and timely use of funds provided under the Next Generation EU instrument, in combination with additional national investment efforts, can reinforce the cyclical recovery. It can bring the economy back to a higher sustainable growth path by accelerating structural change towards a more digital and less carbon-intensive economy.
Higher and more sustainable economic growth will be the most important factor in ensuring that reinforced interlinkages will not give rise to vulnerabilities and risks in the future.
Second, the potential materialisation of vulnerabilities will depend on the degree of divergence among euro area countries.
Despite generally stronger interdependencies, the extent to which these might give rise to challenges in the future differs across the euro area. Banks in more highly indebted countries also tend to exhibit higher domestic sovereign exposures and higher corporate NPL ratios. To a large extent, this reflects unresolved legacy issues with respect to the banking sector and sovereign indebtedness (Chart 9).

Chart 9
Banks’ domestic government bond holdings and corporate NPL ratios across the euro areax-axis: percentage of total assets, y-axis: percentage of total corporate loans

Sources: Bloomberg and ECB.Notes: White bubbles indicate negative values. There are no ten-year sovereign debt securities for Latvia and Estonia; two-year sovereign bond yields are shown instead as a proxy for Latvia, whereas no suitable proxy could be identified for Estonia. The red horizontal and vertical lines indicate sample medians.

The asymmetric impact of the pandemic on different industries has exacerbated prevailing vulnerabilities. Countries with high sovereign debt levels are also those that are more dependent on industries hardest hit by the pandemic, such as tourism, resulting in a larger drop in corporate profits (Chart 10).

Chart 10
Non-financial corporate profits by sovereign indebtednessindex Q4 2019 = 100

Sources: European Commission (AMECO database) and ECB calculations.Notes: Countries are split into highly and less highly indebted based on the median debt-to-GDP ratio of 13 sovereigns in 2019 for which data on the NFC gross operating surplus are available. Highly indebted (above median): ES, FR, BE, PT, IT, GR. Less highly indebted (below/equal to median): EE, NL, IE, FI, DE, SI, AT.

This underlines the importance of support at the European level. The Next Generation EU instrument helps alleviate potential strains on national fiscal space, thereby partly decoupling corporate financing conditions from the fiscal space of their respective sovereigns and directly attenuating the sovereign-bank-corporate nexus.
At the same time, these vulnerabilities are a reminder of the urgent need to make further progress on reforming the euro area’s institutional architecture, in particular by completing the Banking Union, advancing the Capital Markets Union and reviewing the European fiscal framework.
These reforms will foster risk sharing, enhance resilience and reduce procyclicality.
From the viewpoint of monetary policy, the potential emergence of an adverse macro-financial feedback loop between sovereigns, banks and corporates would matter for at least two reasons.
First, it could measurably slow down the return of inflation to our medium-term aim. Increasing corporate defaults through a premature withdrawal of fiscal support would deepen the contraction in output and, ultimately, exert additional disinflationary pressures.
Second, there is a risk that the sovereign-bank-corporate nexus could impair the smooth transmission of monetary policy through financial instabilities, a credit crunch and self-fulfilling price spirals.
The risk of a premature phasing out of fiscal support is largely outside the ECB’s control. But governments need to be mindful of cliff effects that might set off a vicious circle of corporate defaults, tighter bank lending conditions and growing sovereign vulnerabilities.
We therefore continue to call on governments to extend targeted government support for as long as needed and to use public funds responsibly, with a clear focus on raising productivity and long-term growth potential.
What we can do, however, is preserve favourable financing conditions for as long as necessary to reinforce and amplify the fiscal support and to ensure that private investment is not crowded out. This is what the Governing Council reaffirmed at its meeting last week.
On the one hand, this means insulating the bank lending channel from adverse developments, to the extent possible. At our Governing Council meeting in December we therefore decided to further recalibrate our targeted longer-term refinancing operations (TLTRO III) by extending the period of more favourable terms by 12 months and by raising the total amount that counterparties are entitled to borrow.
Preserving favourable financing conditions also means protecting relevant borrowing rates in financial markets from a tightening that would be inconsistent with countering the downward impact of the pandemic on the projected path of inflation.
We therefore decided to extend and expand our pandemic emergency purchase programme, PEPP. We will now conduct purchases under the PEPP until at least March 2022 and we will purchase flexibly according to market conditions.
This means that if favourable financing conditions can be maintained with asset purchase flows that do not exhaust the envelope over the net purchase horizon of the PEPP, the envelope need not be used in full. Equally, the envelope can be recalibrated if required to maintain favourable financing conditions and help counter the negative pandemic shock to the path of inflation.
The focus on duration and preservation combines two mutually reinforcing benefits.
First, the longer duration of the PEPP itself has a stabilising impact on financial markets. It significantly mitigates the risks of a sudden repricing and of self-fulfilling price spirals that threatened to impair the transmission of our policy in March last year.
Second, this calming effect has the potential to increase the efficiency of our purchases. It allows us to calibrate our purchases flexibly according to market conditions, consistent with our commitment to preserve favourable financing conditions. As President Lagarde highlighted last week, this requires the Eurosystem to maintain a strong presence in euro area bond markets.
In summary, by focusing on duration and preservation, we are sending a clear signal to markets that the current broad-based policy mix will continue to provide the necessary support to bridge the time until the economy can stand on its own feet once again.
Conclusion
Let me conclude.
The decisive policy response to the COVID-19 pandemic by fiscal, monetary and prudential authorities has successfully prevented a much deeper economic contraction and averted threats to financial stability.
Government support measures, in combination with the ECB’s ample liquidity provision, have secured bank lending to firms throughout the crisis.
Now it must be ensured that the current virtuous sovereign-bank-corporate nexus does not turn into a vicious circle in the future. This starts with minimising the risks of cliff effects associated with an abrupt and premature withdrawal of public support.
It extends to the swift implementation of the Next Generation EU package and a commitment to use public funds in a way that raises potential growth and nurtures the trust needed to make progress with reforming and completing the euro area’s institutional architecture.
The ECB, for its part, has committed to preserve favourable financing conditions for as long as necessary, reinforcing the fiscal response.
The complementarity of fiscal and monetary policy has been instrumental in effectively countering the pandemic crisis. When the health crisis has been successfully overcome and authorities start to phase out the relief measures, this complementarity should remain an important consideration.
Thank you for your attention.
Compliments of the European Central Bank.
The post ECB Speech | The sovereign-bank-corporate nexus: A virtuous or a vicious circle? first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

Screening of websites for ‘greenwashing’: half of green claims lack evidence

Today, the European Commission and national consumer authorities released the results of a screening of websites (“sweep”), an exercise carried out each year to identify breaches of EU consumer law in online markets. This year, for the first time ever, the sweep focused on ‘greenwashing’, the practice by which companies claim they are doing more for the environment than they actually are. The “sweep” analysed green online claims from various business sectors such as garments, cosmetics and household equipment. National consumer protection authorities had reason to believe that in 42% of cases the claims were exaggerated, false or deceptive and could potentially qualify as unfair commercial practices under EU rules. ‘Greenwashing’ has increased as consumers increasingly seek to buy environmentally sound products.
Didier Reynders, Commissioner for Justice, said: “More and more people want to live a green life, and I applaud companies that strive to produce eco-friendly products or services. However, there are also unscrupulous traders out there, who pull the wool over consumers’ eyes with vague, false or exaggerated claims. The Commission is fully committed to empowering consumers in the green transition and fighting greenwashing. This is precisely one of the main priorities of the New Consumer Agenda adopted last autumn.”
Main findings:
After a broader screening, the Commission and consumer authorities examined 344 seemingly dubious claims in more detail and found that:

In more than half of the cases, the trader did not provide sufficient information for consumers to judge the claim’s accuracy.
In 37% of cases, the claim included vague and general statements such as “conscious”, “eco-friendly”, “sustainable” which aimed to convey the unsubstantiated impression to consumers that a product had no negative impact on the environment.
Moreover, in 59% of cases the trader had not provided easily accessible evidence to support its claim.

In their overall assessments, taking various factors into account, in 42% of cases authorities had reason to believe that the claim may be false or deceptive and could therefore potentially amount to an unfair commercial practice under the Unfair Commercial Practices Directive (UCPD).
Next steps
National authorities will contact the companies concerned to point out the issues detected and to ensure that these are rectified where necessary. The findings of this sweep will feed into the impact assessment to be prepared for the new legislative proposal to empower consumers for the green transition, which was announced in the New Consumer Agenda.
Background
A “sweep” is a set of checks carried out simultaneously on different websites to identify possible breaches of EU consumer law in a particular sector. This year the “sweep” focused on companies claiming to sell environmentally friendly products.
Sweeps are coordinated by the European Commission and carried out yearly by national enforcement authorities in the EU, gathered in the Consumer Protection Cooperation Network (CPC). Information on previous sweeps can be found here.
This year’s sweep was not only coordinated with consumer enforcement authorities in Europe, but around the globe, under the umbrella of the International Consumer Protection and Enforcement Network (ICPEN). Today ICPEN are also releasing their results, which show similar trends.
The screening of websites with the focus on ‘greenwashing’ is one of several initiatives the Commission undertakes in order to empower consumers to make more sustainable choices. Another initiative is the Green Consumption Pledge which Commissioner Reynders launched on the 25th of January 2021 as well as a legislative proposal to empower consumers for the green transition with better information on products’ sustainability and better protection against certain practices, such as ‘greenwashing’ and early obsolescence. Furthermore, a legislative proposal on the substantiation of green claims based on the Environmental Footprint methods will follow.
As part of its Farm to Fork Strategy, the Commission will propose harmonised mandatory front-of-pack nutrition labelling to empower consumers to make informed, healthy, and sustainable food choices. For various household appliances, the EU energy label already provides a clear and simple indication of the energy efficiency of products, thus making it easier for consumers to save money on household energy bills while reducing greenhouse gas emissions across the EU.
According to a recent Consumer Market Monitoring Survey, 78% of consumers found the likely environmental impact of household appliances very important or fairly important when making their choice.
Compliments of the European Commission.
The post Screening of websites for ‘greenwashing’: half of green claims lack evidence first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

Read More
EACC

IMF | Financial Perils in Check for Now, Eyes Turn to Risk of Market Correction

“The vaccines are here!”—the cry heard and welcomed the world over—has boosted hopes of a global economic recovery in 2021. Yet until vaccines are widely available, the market rally and the economic recovery rest on continued monetary and fiscal policy support.
‘While there is for now no alternative to continued monetary policy support, there are legitimate concerns around excessive risk-taking and market exuberance.’
Financial stability risks have been in check so far, but we cannot take this for granted.
Prices for stocks, corporate bonds, and other risk assets have risen higher on the news of vaccine rollouts. Financial markets have shrugged off rising COVID-19 cases, betting that continued policy support will offset any bad economic news in the short term and provide a bridge to the future. As the apparent disconnect between exuberant financial markets and the still-lagging economic recovery persists, it raises the specter of a possible market correction should investors reassess the economic outlook or the extent and duration of policy backstop.
Unwavering faith
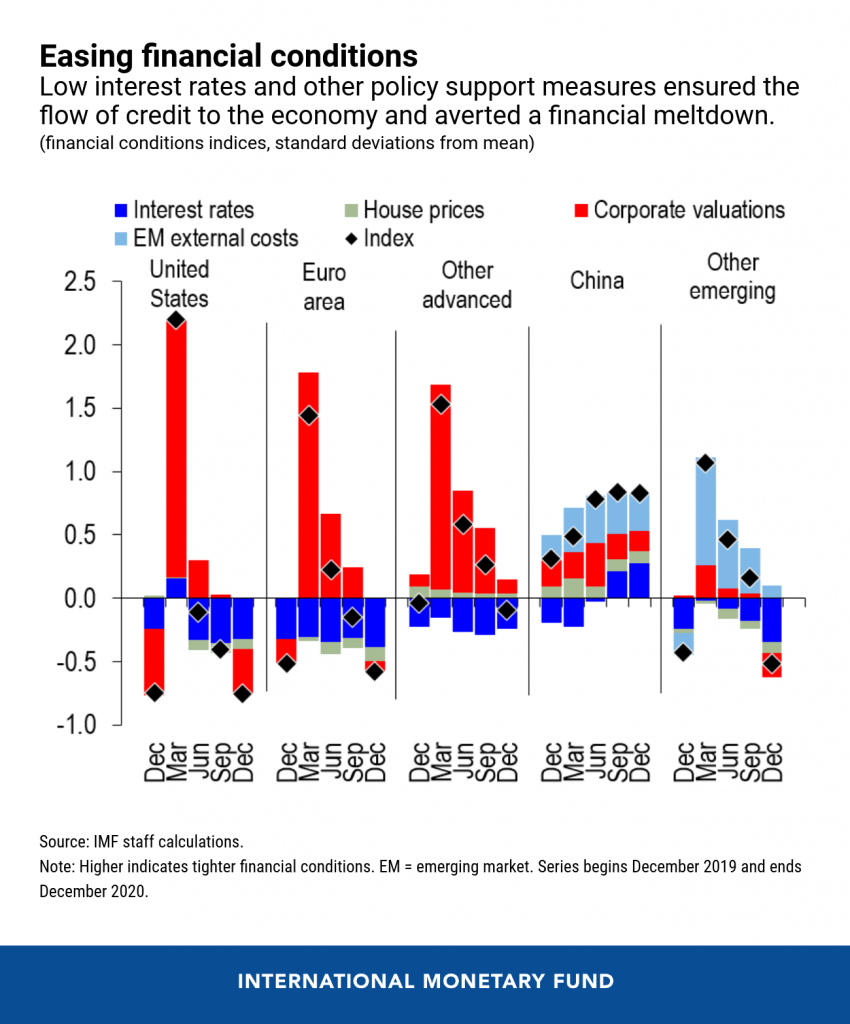
Reflecting unprecedented policy support, financial conditions have eased significantly last year, reversing the sharp tightening experienced during the March 2020 turmoil in most countries, thus supporting economic growth.
Image courtesy of the IMF.
Despite rising COVID-19 cases, the stock prices of firms in sectors like airlines, hotel chains, and consumer services have rebounded as investors continue to move into these previously battered segments in search of good bargains. In advanced economies, credit spreads—the difference between yields on corporate bonds and comparable-maturity Treasury securities—have narrowed sharply both for higher- and lower-rated firms, close to or below levels that prevailed before COVID-19. Interest rates have reached record lows, lowering funding costs for firms, but also incentivizing investors to take on more risk as they search for higher returns on their investments.
Emerging-market countries and corporations have also benefited from the buoyant market sentiment, issuing bonds at record-high levels in 2020. Here too the difference between the yields on the sovereign and corporate debt of emerging-markets and U.S. Treasury securities has contracted sharply. And foreign investment in emerging-market financial assets (equities and bonds) has rebounded, providing more options for financing large debt-rollover needs in 2021.
Image courtesy of the IMF.
The surge of COVID-19 infections and the associated public health restrictions imposed by governments since late 2020 may hurt economic activity in many countries. Yet investors appear optimistic about growth prospects in 2021, confident that policymakers will backstop financial markets along the path to recovery.
Bifurcated reality
Various analysts and investors continue to raise concerns that the true value of risk assets like stocks and corporate bonds seems out of line with market value. For example, they point to misalignments between (very high) equity market prices and valuations implied by (still weak) economic fundamentals, especially when considering the sizable economic uncertainties.
Other market participants, however, note that current market valuations can be explained after accounting for the “lower-for-longer” interest-rate environment.
As justification for the equity market rally, they point to expectations of very low interest rates for the foreseeable future (despite the most recent rise in long-term rates in the United States) and to upward revisions in corporate earnings expectations since the vaccine announcements. They also mention the still relatively high volatility in equity markets as measured by the S&P500 VIX—a barometer of market sentiment—which one could expect to be lower if investors were indeed exuberant. Similar considerations about policy support have been made for credit markets.
Image courtesy of the IMF.
Policy support remains crucial
Policymakers should safeguard the progress made so far and build on the rollout of vaccines to return to sustainable growth by preserving monetary policy accommodation, ensuring liquidity support to households and firms, and keeping financial risks at bay.
Reducing or withdrawing support at this stage could jeopardize the global economic recovery.
Exuberance and Complacency—how serious is the risk of a market correction?
While there is for now no alternative to continued monetary policy support, there are legitimate concerns around excessive risk-taking and market exuberance. This situation creates a difficult dilemma for policymakers. They need to keep financial conditions easy to provide a bridge to vaccines and to the economic recovery. But they also need to safeguard the financial system against unintended consequences of their policies, while remaining in line with their mandates.
With investors betting on persistent policy backstop, a sense of complacency appears to be permeating markets; coupled with apparent uniform investor views, this raises the risk of a market correction or “repricing.” A sharp, sudden asset-price correction—for example, as a result of a persistent increase in interest rates—would cause a tightening of financial conditions. This could interact with existing financial vulnerabilities, creating knock-on effects on confidence and jeopardizing macro-financial stability.
Financial stability risks have been in check so far, but action is needed to address vulnerabilities exposed by the pandemic. These include rising corporate debt, fragilities in the nonbank financial institutions sector, increasing sovereign debt, market access concerns for some developing economies, and declining profitability in some banking systems.
Policymakers need to use this time to safeguard financial stability by employing macroprudential measures (for example, stricter supervisory and macroprudential oversight, including targeted stress tests at banks and prudential tools for highly levered borrowers) and developing new tools as needed. For example, policymakers are considering whether the macroprudential framework for nonbank financial institutions may need to be strengthened to address weaknesses that became apparent during the March turmoil.
Tackling vulnerabilities through these policies is crucial to avoid putting economic growth at risk and to prevent financial instability from disrupting the global economy.
Authors:

Tobias Adrian, Financial Counsellor and Director of the IMF’s Monetary and Capital Markets Department

Fabio Natalucci, Deputy Director of the Monetary and Capital Markets Department at the IMF.

Compliments of the IMF.
The post IMF | Financial Perils in Check for Now, Eyes Turn to Risk of Market Correction first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

Statement by the Eurogroup President, Paschal Donohoe, on the signature of ESM Treaty and the Single Resolution Fund Amending Agreements

Eurogroup | Statements and remarks by Paschal Donohoe | 27 January 2021 |
Today, we mark an important milestone in the further development of the Economic and Monetary Union, which will strengthen euro area’s crisis prevention and resolution capabilities as well as the Banking Union. We also demonstrate our unity of purpose to deliver progress on important issues for the benefit of all our citizens.
Representatives from the Member States have signed the amending agreements to the Treaty on the European Stability Mechanism and the Single Resolution Fund Intergovernmental Agreement[1]. This signature launches the ratification procedures in the Member States, in accordance with their national constitutional requirements.
On 30 November 2020, the Eurogroup reached a political agreement in relation to the ESM reform package. The agreement will make the ESM more effective and flexible. This includes the ESM providing a common backstop to the Single Resolution Fund by means of a credit line as of the beginning of 2022, two years ahead of schedule. The decision taken by Eurogroup regarding the early introduction of the backstop recognises the considerable efforts by the European banking sector, supervisors, and Member States in significantly improving all risk reduction indicators during recent years.
The common backstop will help to ensure that a bank failure does not harm the broader economy or cause financial instability. It will be financed by contributions from the banking sector and not by taxpayers’ money, thereby reducing the link between banks and sovereigns in the Banking Union.
The ESM Treaty reform will expand the ESM’s mandate with new tasks and responsibilities: it will be equipped with a more accessible precautionary credit line and have a stronger role in financial assistance programmes and crisis prevention. Together with the early introduction of the common backstop, this will help to ensure that the euro area is capable of handling challenges if they arise.
I look forward to the completion of national ratification procedures to allow the entry into force of both agreements as of next year.
Compliments of the Council of the European Union.
The post Statement by the Eurogroup President, Paschal Donohoe, on the signature of ESM Treaty and the Single Resolution Fund Amending Agreements first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

Travel restrictions: EU Council reviews the list of third countries for which member states should gradually lift restrictions on non-essential travel

Following a review under the recommendation on the gradual lifting of the temporary restrictions on non-essential travel into the EU, the Council updated the list of countries for which travel restrictions should be lifted. As stipulated in the Council recommendation, this list will continue to be reviewed every two weeks and, as the case may be, updated.
Based on the criteria and conditions set out in the recommendation, as from 28 January member states should gradually lift the travel restrictions at the external borders for residents of the following third countries:

Australia
New Zealand
Rwanda
Singapore
South Korea
Thailand

China, subject to confirmation of reciprocity

Travel restrictions should also be gradually lifted for the special administrative regions of China Hong Kong and  Macao, subject to confirmation of reciprocity.
Residents of Andorra, Monaco, San Marino and the Vatican should be considered as EU residents for the purpose of this recommendation.
The criteria to determine the third countries for which the current travel restriction should be lifted cover in particular the epidemiological situation and containment measures, including physical distancing, as well as economic and social considerations. They are applied cumulatively. Reciprocity should also be taken into account regularly and on a case-by-case basis.
Schengen associated countries (Iceland, Lichtenstein, Norway, Switzerland) also take part in this recommendation.
Background
On 16 March 2020, the Commission adopted a communication recommending a temporary restriction of all non-essential travel from third countries into the EU for one month. EU heads of state or government agreed to implement this restriction on 17 March. The travel restriction was extended for a further month respectively on 8 April 2020 and 8 May 2020.
On 11 June the Commission adopted a communication recommending the further extension of the restriction until 30 June 2020 and setting out an approach for a gradual lifting of the restriction on non-essential travel into the EU as of 1 July 2020.
On 30 June the Council adopted a recommendation on the gradual lifting of the temporary restrictions on non-essential travel into the EU, including an initial list of countries for which member states should start lifting the travel restrictions at the external borders. The list is reviewed every two weeks and, as the case may be, updated.
The Council recommendation is not a legally binding instrument. The authorities of the member states remain responsible for implementing the content of the recommendation. They may, in full transparency, lift only progressively travel restrictions towards countries listed.
A Member State should not decide to lift the travel restrictions for non-listed third countries before this has been decided in a coordinated manner.
Contact:

Verónica Huertas Cerdeira, Press officer | veronica.huertas-cerdeira@consilium.europa.eu

Compliments of the Council of the European Union.
The post Travel restrictions: EU Council reviews the list of third countries for which member states should gradually lift restrictions on non-essential travel first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.