EACC

ECB | January 2021 euro area bank lending survey

Credit standards tightened for loans to enterprises and households
Firms’ demand for loans continued to decline, while demand for housing loans increased
Government guarantees on loans to firms supported bank lending conditions

Credit standards – i.e. banks’ internal guidelines or loan approval criteria – tightened across all loan categories, namely loans to enterprises, loans to households for house purchase and consumer credit and other lending to households in the fourth quarter of 2020, according to the January 2021 bank lending survey (BLS). The net percentage of banks reporting a tightening of credit standards for loans or credit lines to firms (net percentage of banks at 25%, see Chart 1) was somewhat higher than in the previous round. Credit standards for loans to households also tightened (a net percentage of 7% for loans to households for house purchase and 3% for consumer credit and other lending to households), but at a slower pace than in the previous quarters of 2020. Banks referred to the deterioration of the general economic outlook, increased credit risk of borrowers and a lower risk tolerance as relevant factors for the tightening of their credit standards for loans to firms and households. In the first quarter of 2021, banks expect credit standards to continue to tighten for loans to firms and households.
Banks’ overall terms and conditions – i.e. the actual terms and conditions agreed in loan contracts –tightened in the fourth quarter of 2020 for new loans to enterprises, with more stringent collateral requirements and wider loan margins, especially for riskier loans. For loans to households for house purchase, banks’ overall terms and conditions also tightened in the fourth quarter of 2020.
Firms’ demand for loans or drawing of credit lines declined further in net terms in the fourth quarter of 2020, with a larger percentage of banks indicating a decline than an increase in firms’ loan demand. Demand for inventories and working capital continued to contribute to an increase in demand, although its positive contribution was lower than in the first half of 2020. This might be explained by the precautionary liquidity buffers built up in previous quarters. Demand for loans for fixed investment declined for the fourth consecutive quarter (see Chart 2). Net demand for housing loans continued to increase in the fourth quarter of 2020, reflecting a catching-up in demand after the first lockdown period in the second quarter. For consumer credit and other lending to households a net percentage of banks reported a decline in demand, following a moderate increase in the previous quarter. Net demand for housing loans and consumer credit was supported by the low general level of interest rates, while lower consumer confidence continued to dampen demand. In the first quarter of 2021, banks expect net demand for loans to firms and for consumer credit to increase, while net demand for housing loans is expected to decline.
Euro area banks indicated that regulatory or supervisory action continued to strengthen banks’ capital position and had a strong easing impact on their funding conditions in 2020. Banks also reported that supervisory or regulatory action continued to have a net tightening impact on their credit standards across all loan categories.
Euro area banks reported that non-performing loans (NPLs) had a tightening impact on credit standards and on terms and conditions for loans to enterprises and consumer credit in the second half of 2020 (and a broadly neutral impact for housing loans). Risk perceptions and risk aversion were the main drivers of the tightening impact of NPL ratios.
Looking at a sectoral breakdown, respondent banks indicated a net tightening of credit standards for loans to enterprises across all main sectors of economic activities in the second half of 2020. The net tightening was most pronounced for loans to firms in the commercial real estate and the wholesale and retail trade sectors.
Banks reported that coronavirus (COVID-19)-related government guarantees supported credit standards and helped keep terms and conditions for loans to firms more favourable in 2020. Banks also indicated a very strong net increase in demand for loans or credit lines with government guarantees in the first half of 2020, while the net increase in the second half was moderate, reflecting reduced liquidity needs.
The euro area bank lending survey, which is conducted four times a year, was developed by the Eurosystem in order to improve its understanding of banks’ lending behaviour in the euro area. The results reported in the January 2021 survey relate to changes observed in the fourth quarter of 2020 and expected changes in the first quarter of 2021, unless otherwise indicated. The January 2021 survey round was conducted between 4 and 29 December 2020. A total of 143 banks were surveyed in this round, with a response rate of 100%.
For media queries, please contact Silvia Margiocco tel.: +49 69 1344 6619.

Chart 1
Changes in credit standards for loans or credit lines to enterprises and contributing factors(net percentages of banks reporting a tightening of credit standards and contributing factors)

Source: ECB (BLS).Notes: Net percentages are defined as the difference between the sum of the percentages of banks responding “tightened considerably” and “tightened somewhat” and the sum of the percentages of banks responding “eased somewhat” and “eased considerably”.

Chart 2
Changes in demand for loans or credit lines to enterprises and contributing factors(net percentages of banks reporting an increase in demand and contributing factors)

Source: ECB (BLS).Notes: Net percentages for the questions on demand for loans are defined as the difference between the sum of the percentages of banks responding “increased considerably” and “increased somewhat” and the sum of the percentages of banks responding “decreased somewhat” and “decreased considerably”.
Compliments of the ECB.

The post ECB | January 2021 euro area bank lending survey first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.
Read More
EACC

IMF | What the Continued Global Uncertainty Means for You

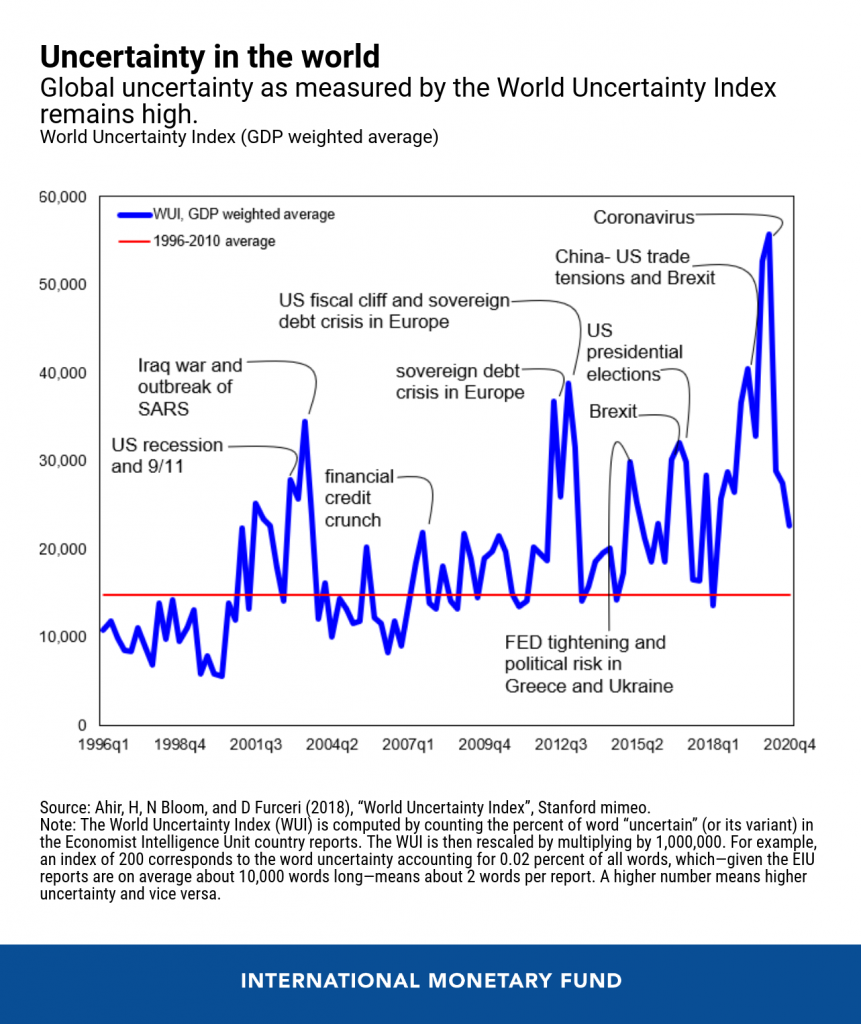
Global uncertainty reached unprecedented levels at the beginning of the COVID-19 outbreak and remains elevated. The World Uncertainty Index—a quarterly measure of global economic and policy uncertainty covering 143 countries—shows that although uncertainty has come down by about 60 percent from the peak observed at the onset of the COVID-19 pandemic in the first quarter of 2020, it remains about 50 percent above its historical average during the 1996–2010 period.

‘Uncertainty in systemic economies matters for uncertainty around the world.’

What drives global uncertainty?
Economic growth in key systemic economies, like those of the United States and European Union, is a key driver of economic activity in the rest of the world. Is this also true when it comes to global uncertainty? For example, given the higher interconnectedness across countries, should we expect that uncertainty from the U.S. election, Brexit, or China-U.S. trade tensions spill over and affect uncertainty in other countries?
To answer this question, we construct an index that measures the extent of “uncertainty spillovers” from key systemic economies—the Group of 7 (G7) countries plus China—to the rest of the world. In particular, we identify uncertainty spillovers from systemic economies by text mining the Economist Intelligence Unit country reports, covering 143 countries from the first quarter of 1996 to the fourth quarter of 2020.
Uncertainty spillovers from each of the systemic economies are measured by the frequency that the word “uncertainty” is mentioned in the reports in proximity to a word related to the respective systemic-economy country. Specifically, for each country and quarter, we search the country reports for the words “uncertain,” “uncertainty,” and “uncertainties” appearing near words related to each country. The country-specific words include country’s name, name of presidents, name of the central bank, name of central bank governors, and selected country’s major events (such as Brexit).
To make the measure comparable across countries, we scale the raw counts by the total number of words in each report. An increase in the index indicates that uncertainty is rising, and vice versa.
Our results reveal two key facts:
First: Yes, uncertainty in systemic economies matters for uncertainty around the world.
Second: Only the United States and the United Kingdom have significant uncertainty spillover effects, while the other systemic economies play a little role, on average.
Starting with the United States, the chart below displays the global (excluding the United States) average of the ratio of uncertainty related to the United States to overall uncertainty. It shows that uncertainty related to the United States has been a key source of uncertainty around the world since the past few decades
For instance, during the 2001–2003 period, U.S.-related uncertainty contributed to about 8 percent of the uncertainty in other countries—about 23 percent of the increase in global uncertainty from the historical mean. n the last 4 years, U.S.-related uncertainty has contributed to about 13 percent of uncertainty in other countries—with peaks of about 30 percent—and approximately 20 percent of the increase in global uncertainty from historical mean.
Uncertainty related to the U.K.-EU Brexit negotiations has also had significant global spillovers in the last 4 years, with a peak of more than 30 percent and contributing to about 11 percent in the rise in global uncertainty during this period.

Finally, the ratio of uncertainty related to the other systemic countries to overall uncertainty shows Canada, China, France, Germany, Italy, and Japan combined have little uncertainty spillover effects on the rest of the world. An exception is China in the recent years, but most of the China-related uncertainty is due to trade tensions with the United States. That said, while other systemic economies have limited global uncertainty spillovers, they have important regional uncertainty effects—such as for example, Germany for the other European economies and China and Japan for several Asian economies.

Authors:

Hites Ahir is a senior research officer in the IMF’s Research Department

Nicholas (Nick) Bloom is a Professor of Economics at Stanford University, and a Co-Director of the Productivity, Innovation and Entrepreneurship program at the National Bureau of Economic Research

Davide Furceri is Deputy Division Chief of the Regional Studies Division of the Asia and Pacific Department of the IMF

Compliments of the IMF.
The post IMF | What the Continued Global Uncertainty Means for You first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

European Commission reorganises the “Task Force for Relations with the United Kingdom” into the “Service for the EU-UK Agreements”

The conclusion of the EU-UK Trade and Cooperation Agreement on 24 December 2020 means that the very successful mandate of the Task Force for Relations with the United Kingdom (UKTF) will come to an end. The UKTF will cease to exist on 1 March 2021.
To support the efficient and rigorous implementation and monitoring of the Agreements with the UK, the European Commission has decided to establish a new Service for the EU-UK Agreements (UKS). The UKS will be part of the presidential services’ Secretariat-General and will be operational as of 1 March 2021. The mandate and duration of the newly created service will be reviewed on a continuous basis. The UKS will closely cooperate with the HRVP.
Michel Barnier will become Special Adviser to President von der Leyen as of 1 February 2021. He will advise the President on the implementation of the EU-UK Withdrawal Agreement and provide expertise in view of the finalisation of the EU’s ratification process of the EU-UK Trade and Cooperation Agreement.
Vice-President Maroš Šefčovič, the Vice-President in charge of interinstitutional relations and foresight, has been appointed as the Member of the Commission to co-chair and represent the European Union in the Partnership Council, established by the EU-UK Trade and Cooperation Agreement.
Compliments of the European Commission.
The post European Commission reorganises the “Task Force for Relations with the United Kingdom” into the “Service for the EU-UK Agreements” first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

ECB digital euro consultation ends with record level of public feedback

Over 8,000 responses received in online survey
Privacy, security and pan-European reach ranked highest in European citizens’ preferences
Detailed analysis to be published in spring, ahead of decision on project launch

The European Central Bank (ECB) concluded its public consultation on the digital euro yesterday and will now analyse in detail the large number of responses. 8,221 citizens, firms and industry associations submitted responses to an online questionnaire, a record for ECB public consultations.
The public consultation was launched on 12 October 2020, following the publication of the Eurosystem report on a digital euro. The ECB will publish a comprehensive analysis of the public consultation in the spring, which will serve as an important input for the ECB’s Governing Council when deciding whether to launch a digital euro project.
An initial analysis of raw data shows that privacy of payments ranked highest among the requested features of a potential digital euro (41% of replies), followed by security (17%) and pan-European reach (10%).
“The high number of responses to our survey shows the great interest of Europe’s citizens and firms in shaping the vision of a digital euro,” said Fabio Panetta, Member of the ECB’s Executive Board and Chair of the task force on a digital euro. “The opinions of citizens, businesses and all stakeholders are of utmost importance for us as we assess which use cases a digital euro might best serve.”
The Eurosystem task force, bringing together experts from the ECB and 19 national central banks of the euro area, identified possible scenarios that would require the issuance of a digital euro. These scenarios include an increased demand for electronic payments in the euro area that would require a European risk-free digital means of payment, a significant decline in the use of cash as a means of payment in the euro area, the launch of global private means of payment that might raise regulatory concerns and pose risks for financial stability and consumer protection, and a broad take-up of central bank digital currencies issued by other central banks.
A digital euro would be an electronic form of central bank money accessible to all citizens and firms – like banknotes, but in a digital form – to make their daily payments in a fast, easy and secure way. It would complement cash, not replace it. The Eurosystem will continue to issue cash in any case.
A digital euro would combine the efficiency of a digital payment instrument with the safety of central bank money. The protection of privacy would be a key priority, so that the digital euro can help maintain trust in payments in the digital age.
For media queries, please contact Alexandrine Bouilhet, e: Alexandrine.Bouilhet[at]ecb.europa.eu | tel.: +49 172 174 93 66.
Compliments of the European Central Bank.
The post ECB digital euro consultation ends with record level of public feedback first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

Read More
EACC

IMF | Legally Speaking, is Digital Money Really Money?

Countries are moving fast toward creating digital currencies. Or, so we hear from various surveys showing an increasing number of central banks making substantial progress towards having an official digital currency.
But, in fact, close to 80 percent of the world’s central banks are either not allowed to issue a digital currency under their existing laws, or the legal framework is not clear.
To help countries make this assessment, we reviewed the central bank laws of 174 IMF members in a new IMF staff paper, and found out that only about 40 are legally allowed to issue digital currencies.
Not just a legal technicality
Any money issuance is a form of debt for the central bank, so it must have a solid basis to avoid legal, financial and reputational risks for the institutions. Ultimately, it is about ensuring that a significant and potentially contentious innovation is in line with a central bank’s mandate. Otherwise, the door is opened to potential political and legal challenges.
Now, readers may be asking themselves: if issuing money is the most basic function for any central bank, why then is a digital form of money so different? The answer requires a detailed analysis of the functions and powers of each central bank, as well as the implications of different designs of digital instruments.
Building a case for digital currencies
To legally qualify as currency, a means of payment must be considered as such by the country’s laws and be denominated in its official monetary unit. A currency typically enjoys legal tender status, meaning debtors can pay their obligations by transferring it to creditors.
Therefore, legal tender status is usually only given to means of payment that can be easily received and used by the majority of the population. That is why banknotes and coins are the most common form of currency.
To use digital currencies, digital infrastructure—laptops, smartphones, connectivity—must first be in place. But governments cannot impose on their citizens to have it, so granting legal tender status to a central bank digital instrument might be challenging. Without the legal tender designation, achieving full currency status could be equally challenging. Still, many means of payments widely used in advanced economies are neither legal tender nor currency (e.g., commercial book money).
Uncharted waters?
Digital currencies can take different forms. Our analysis focuses on the legal implications of the main concepts being considered by various central banks. For instance, where it would be “account-based” or “token-based.” The first means digitalizing the balances currently held on accounts in a central banks’ books; while the second refers to designing a new digital token not connected to the existing accounts that commercial banks hold with a central bank.
From a legal perspective, the difference is between centuries-old traditions and uncharted waters. The first model is as old as central banking itself, having been developed in the early 17th century by the Exchange Bank of Amsterdam—considered the precursor of modern central banks. Its legal status under public and private law in most countries is well developed and understood. Digital tokens, in contrast, have a very short history and unclear legal status. Some central banks are allowed to issue any type of currency (which could include digital forms), while most (61 percent) are limited to only banknotes and coins.
Another important design feature is whether the digital currency is to be used only at the “wholesale” level, by financial institutions, or could be accessible to the general public (“retail”). Commercial banks hold accounts with their central bank, being therefore their traditional “clients.” Allowing private citizens’ accounts, as in retail banking, would be a tectonic shift to how central banks are organized and would require significant legal changes. Only 10 central banks in our sample would currently be allowed to do so.

A challenging endeavor
The overlapping of these and other design features can create very complex legal challenges—and could well influence the decisions made by each monetary authority.
The creation of central bank digital currencies will also raise legal issues in many other areas, including tax, property, contracts, and insolvency laws; payments systems; privacy and data protection; most fundamentally, preventing money laundering and terrorism financing. If they are to be “the next milestone in the evolution of money,” central bank digital currencies need robust legal foundations that ensure smooth integration to the financial system, credibility and broad acceptance by countries’ citizens and economic agents.
Authors:

Catalina Margulis is a consulting counsel in the IMF Legal Department’s Financial and Fiscal Law unit

Arthur Rossi is a Research Officer in the IMF Legal Department’s Financial and Fiscal Law unit

Compliments of the IMF.
The post IMF | Legally Speaking, is Digital Money Really Money? first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

EU-UK future relations: MEPs to debate the agreement reached on 24 December

Members on the Foreign Affairs and International Trade Committees will debate the new EU-UK Trade and Cooperation Agreement on Thursday at 10.00 CET.

The joint meeting of the lead committees will intensify the democratic parliamentary scrutiny process for the new EU-UK Trade and Cooperation Agreement reached by EU and British negotiators on 24 December.
The two committees will in due course vote on the consent proposal prepared by the two standing rapporteurs Christophe Hansen (EPP, Luxembourg) and Kati Piri (S&D, The Netherlands), to allow for a plenary vote before the end of the provisional application of the agreement.
In addition to the plenary vote, Parliament will also vote on an accompanying resolution prepared by the political groups in the UK Coordination Group and the Conference of Presidents.
The meeting
When: Thursday, 14 January, at 10.00 CET.Where: Room 6Q2 in Parliament’s Antall building in Brussels and remote participation.
You can follow it live here. (10.00-12.00 CET).
Here is the agenda.
Background
The new Trade and Cooperation agreement has been provisionally applied since 1 January 2021. For it to enter into force permanently, it requires the consent of the Parliament.
MEPs on the International Trade Committee held a first meeting on the new EU-UK deal on Monday 11 January, during which they promised thorough scrutiny of the agreement. Read more here.
Compliments of the European Parliament. 

The post EU-UK future relations: MEPs to debate the agreement reached on 24 December first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

Read More
EACC

TechDispatch | EU Personal Information Management Systems

Personal Information Management Systems (PIMS) are new products and services that help individuals to have more control over their personal data. PIMS enable individuals themselves to manage and control their online identity.
1. What are Personal Information Management Systems?
The PIMS concept offers a new approach in which individuals are the “holders” of their own personal information. PIMS allow individuals to manage their personal data in secure, local or online storage systems and share them when and with whom they choose. Individuals would be able to decide what services can use their data, and what third parties can share them. This allows for a human centric approach to personal data and to new business models, protecting against unlawful tracking and profiling techniques that aim at circumventing key data protection principles.
There is a growing interest in our “digital societies” in how individuals can better control their personal data. A Eurobarometer survey from March 2019 revealed that half of the respondents (51%) felt only in partial control over the information they provided online, while 30% believed that they had no control at all. Only 14% of the respondents thought they were in complete control. A US survey from 2019 even showed 80% of respondents feeling they were not in control of their personal data.
In the European Union, Article 8 of the EU Charter enshrines the protection of personal data as a fundamental right for every person and the EU General Data Protection Regulation (GDPR) aims to empower individuals to be in control of their data. For this purpose, practical and effective tools and services are needed.
Personal data is constantly collected in the digital environment, leading to individuals leaving digital footprints. The GDPR provides for several data subject rights, such as the right to access and rectification of personal data. The current architecture of information society services makes it however challenging for individuals to have full control of how their data are used, who should have access to them and how to provide effective restrictions and objections to data processing.

Figure 1: A simple schema for a Personal Information Management System with a local personal data storage.A basic feature of a common concept of PIMS (see Figure 1) is providing access control and an access trail. Individuals, service providers and applications would need to authenticate to access a personal storage centre. This enables individuals to track back who has had access to their digital behaviour. Individuals are able to customize what categories of data they want to share and with whom. Other usually common elements of PIMS are secure data storage, secure data transfers (transporting data safely between systems and applications) and data-level interoperability and data portability.
There are several examples of initiatives and projects claiming PIMS features. They include: Nextcloud enables individuals and organisations to use their own cloud services for file sharing and collaboration services, as well as sharing files across different Nextcloud servers. People can install the free and open source software themselves or receive the software as a service (SaaS) from professional providers. Many universities, governments and companies already employ Nextcloud.
Solid is a ‘proposed set of conventions and tools for building decentralised social applications’. Data such as contacts, calendars and photos may be stored in a so-called personal online datastore (POD). These data can be accessed by compatible apps. Users are allowed a continuous experience across apps within the ecosystem, keeping the data within their pods without unnecessarily replicating them.
MyDex is a UK-based Community Interest Company providing a portable, interoperable online identifier. Users can access a particular service online through a secure personal store, where all personal ‘verified’ records are managed. They can be securely accessed by other applications using Application Programming Interfaces (APIs). It provides the ability to grant and revoke access permissions on a general or ad-hoc basis.
MyData is a non-profit association teaming up initiatives around the world to ‘empower individuals by improving their right to self-determination regarding their personal data’. MyData claims to combine industry needs for data access with digital human rights, through promoting open standards and sharing the same set of principles, for a ‘shift from data protection to data empowerment’.
2. What are the data protection issues?
2.1 Individual empowerment plus Data protection by design and by default
When correctly designed, PIMS could help data controllers to implement the obligations of privacy and data protection by design and by default and to support them to demonstrate compliance with the GDPR. If however these tools or systems fail to be properly designed, for example, there is a risk that data subjects will not be empowered to manage their own digital identity, but will instead unwittingly find themselves on a path of being determined by others or which result in data subjects taking decisions contrary to their own interests under the influence of these tools/system.
2.2 Consent management
PIMS deliver their full potential when they rely on users’ consent. Individuals would keep full control and would be free to share their personal data according to their own preference and delete them whenever they want. In some circumstances however, the law decides how data should be processed (e.g. storing tax declarations for some years). Control in such cases would achieve transparency in the way personal data are processed, and being able to verify their accuracy, retention time etc.
A basic feature for PIMS is managing the use and sharing preferences of an individual’s personal data such as photos, videos, contact lists, and even geolocation. For each category of personal data, individuals should be able to decide what services can use them, for what purposes and with whom they can share them. When consent is withdrawn, advanced PIMS might provide reliable evidence that a service no longer uses one’s data.
2.3 Transparency and traceability
Online service providers often collect users’ personal data in exchange for allegedly ‘free’ services. The data subject is often faced with a ‘take it or leave it’ approach, with little or no transparency for the individuals on how his or her personal data is handled. PIMS would allow for transparency both at the level of shared policies and by technical design, disclosing what services are processing which data for what specific purposes. Information can be given in real time. Personal data dashboards can help individuals to follow their data and their processing.
The use of PIMS can also support eGovernment services providing advantages such as greater traceability and transparency on which public administration has access to what personal data.
2.4 Exercise of individual’s rights of access, to rectification and erasure or “right to be forgotten”
PIMS provide features for individuals to be able to access their personal data, as well as to rectify or erase them, as provided for by the GDPR, either because the data are in repositories under their direct control or because all shared data are linked to a source, which is again in the control of the individual.
2.5 Data accuracy
In PIMS, individuals are responsible for the data they provide. At the same time, when other organisations are accountable for personal data (e.g. banks, utility providers), certain PIMS can provide proof of origin/validity from those organisations, thus granting the necessary level of reliability. Greater data accuracy is a benefit also to those third parties that have an interest in accessing the data, thus enabling synergies between individuals and organisations.
2.6 Data portability and interoperability
PIMS can usually offer personal data and other metadata describing their properties in machine readable formats, as well as programming interfaces (APIs) for data access and processing. This last feature implies the use of standard policies and system protocols. This is an essential element, the lack thereof currently also represents a limit for PIMS adoption.
2.7 Data security
PIMS must also ensure the security of personal data at rest and in transit from unauthorised or accidental access or modification. In order to be fully implemented, PIMS should be able to rely on Privacy Enhancing Technologies (PETs), a wide range of techniques that include trusted execution environments, homomorphic encryption, secure multi-party computation and differential privacy. Data minimisation and anonymisation services should also be provided. One feature of many PETs is the use of cryptography.
Cryptographic features may be used to verify the authenticity of data and to implement users’ privacy preferences such as authorised purposes and permitted retention periods against service providers and third parties. A common use of cryptography is data encryption, which supports confidentiality and integrity of communications, databases and other repositories. Current cryptographic researches are developing ways to allow for calculations without decrypting the data. This would mitigate risks of unauthorised access or disclosure. Cryptography also provides mathematical evidence that data and communications come from a certain source as well as proof that an entity (for example a service, an organisation, or an individual) is authorised to access categories of (personal) data for certain purposes or perform any other actions on those data, even on a granular basis. Data would then be disclosed only to those services bearing that cryptographic evidence.
Finally, it supports data minimisation techniques (e.g. attribute-based credentials), to ensure that third parties can access only necessary pieces of information, thus avoiding the disclosure of the full identity of the individual.
Currently, a big challenge for PIMS is the low market application of these technologies, in a digital world dominated by a few big tech companies that are making use of the current online tracking models. This situation so far prevents the growth of PIMS and consequently their adoption. If adopted, the EU Commission’s Data Governance Act would provide conditions for intermediation services between data subjects that seek to make their personal data available and potential data users, including making available the technical or other means to enable such services, in the exercise of the rights provided in the GDPR.
Contacts:

Massimo Attoresi
Thiago Moraes
Thomas Zedrick
Email: techdispatch@edps.europa.eu

Compliments of the Technology and Privacy Unit of the European Data Protection Supervisor (EDPS).
The post TechDispatch | EU Personal Information Management Systems first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

John Bruton | The UK/EU Trade & Cooperation Agreement

By John Bruton, former Prime Minister of Ireland (Taoiseach) & former EU Ambassador to the US |
UK gained a little extra sovereignty of the island of Britain, by giving up some UK sovereignty in Northern Ireland
The EU/UK trade deal maintains Ireland’s agricultural export market in Britain. A “No Deal” would have destroyed it. The imposition of tariffs would have imposed huge costsm on consumers and disruption to business.
That said, the fact that the Agreement had to be rushed through at the last minute left little time for debate which side lost the least in the negotiation.  For it is in the nature of a divorce, like Brexit, that both sides actually lose.
First let us look at the British side.
For them, the goal was “sovereignty”. In sum, Boris Johnson gained more UK sovereignty over the island of Britain, but did so by sacrificing a considerable measure of UK sovereignty over Northern Ireland.
Traditionally sovereignty in Britain was seen as the unfettered power of the British Parliament to legislate.  Brexiteers have interpreted it as taking back control into the hands of British Ministers, rather than into the hands of Parliament as such.
On the other hand, EU rules, in which neither the UK, nor the people of Northern Ireland, will have  a direct say, will continue to be made for, and apply in, Northern Ireland. This creates a democracy deficit, even if the subject matter will be highly technical.
After much effort and controversy, the UK has won the right to diverge from EU rules for the island of Britain. To show that the effort was worthwhile, it will be tempted to adopt different rules on trade and regulatory matters just for the sake of it.
The more Britain diverges from the EU, the more will it diverge from Northern Ireland
But the more British rules diverge from EU rules, the more will Northern Ireland diverge from the rest of the United Kingdom.
This creates a political mine field and a strategic dilemma.
The implications for NI unionists could be quite destabilising. A sense of losing control over their future, and of not being represented when decisions are being made, could encourage irrational politics. This will require serious reflection in Brussels, London and especially Dublin before there is any new divergence between the UK and the EU.
The Joint EU/UK Committee, already set up under the Withdrawal Agreement, will need to monitor the political and security consequences. Title X of the Agreement requires advance notice, and consultations, on any changes in regulations as between the UK and the EU. It will be important for peace and security of these islands  that these consultations include representatives of all major interests in Northern Ireland.
The gains for the UK side, at a price
On the other hand, the Agreement contains significant gains for the UK side from a “sovereignty” perspective, at least as far as the island of Britain is concerned.
Firstly, there will be no direct application of decisions of the European Court of Justice on the island of Britain.
Secondly, while the UK has accepted that it will not regress from present high social and environmental standards, it will be free to set for itself the detail of those standards. These may be different from those in the EU and thus in Northern Ireland.  This right to diverge is what UK Brexiteers saw as an expression of UK’s sovereignty. There will be strong temptations to use this power if only to show that Brexit was worth the effort.
But the UK also accepts that divergence will not come for free.
It has had to accept that services exports from the UK have lost automatic access to the EU market, a large and incalculable sacrifice. It has also lost the European Arrest Warrant and access to eU data bases.
As one advocate of Brexit, Dr Liam Fox MP, put it in Westminster last week
“If we want to access the Single Market, there has to be a price to be paid.  If we want to diverge from the rules of the Single Market, there has to a price to be paid”
The Agreement establishes detailed mechanisms to settle what ”price” will  have to be paid for any new  divergence .
Already, the UK is contemplating allowing genetically edited crops. If these are not permitted in the EU, there could be trade frictions and competitive losses for EU farmers.
How will disputes be settled?
These new mechanisms , a Partnership Council, Joint Committees, and Arbitration Tribunals, are completely untested at this stage.
A great deal will depend on how much use the UK will make of its new freedoms. The more EU and British policies diverge, the greater will be the strain on the Agreement.
In the last 5 years of debate about Brexit, UK politicians have actually advanced very few ideas of how they might use the new freedom conferred by Brexit.
So it is impossible to assess, at this stage, whether or not they might do things that would push the EU to seek redress through the mechanisms of the Agreement, or contribute to instability in Northern Ireland.
If problems arise and these cannot be settled in the committee system, there is an agreed provision for arbitration. Three person Arbitration Tribunals which will operate on strict time limits. If the Arbitrators find that either the EU or the UK has breached the agreed principles, the other party will be allowed to impose tariffs or prohibitions, to compensate for losses it has suffered.
Better than no deal
This Dispute settlement aspect of the Agreement is valuable from an EU point of view.
Without it, any disputes would have had to be referred to the WTO.  The WTO system is both cumbersome and narrow. Parties can stall, adopt delaying tactics, or  ignore WTO rulings.
Disputes in the WTO can drag on for years, as we have seen with the US/EU dispute about subsidies to Boeing and Airbus.
That said, we will now  be replacing a single set of rules, interpreted by the European Court of Justice (ECJ), with individual Arbitration Tribunals, operating under tight deadlines.
This could lead to inconsistent decisions in different areas of trade. If a Tribunal interprets EU law differently to the interpretation later made by the ECJ, there could be real difficulties. Some of the problems that have arisen in EU relations with Switzerland could be replicated in EU relations with the UK, but with added complications in respect of Northern Ireland.
The UK will also be free to negotiate trade agreements of its own with non EU countries. These negotiations may create additional pressure for even more divergence between UK and EU standards, than the UK authorities themselves might have chosen.
It may come under pressure to allow the imports to the UK that would not meet EU standards, for example chlorinated chicken, hormone treated beef, or genetically modified food . If these products are then incorporated into exports to the EU, the EU will have to ban them.
UK or EU policy decisions could also skew the level playing field on which EU and British producers must compete.
In Title XI of Part One, and in Part Six of the Agreement, there are provisions for resolving disputes .
If the dispute is about unfair subsidies, firms can go directly to the courts, citing the text of Title XI.
If the dispute is about something else, the remedy  will be under Part Six  and  will be indirect, requiring either the EU or UK side to take the matter up in one of the many Committees set up under the Agreement. There could eventually be recourse to an Arbitration Tribunal.
In global terms, the continent of Europe as a whole has been weakened by Brexit. The day to day effect remains to be seen.
Compliments of John Bruton.
The post John Bruton | The UK/EU Trade & Cooperation Agreement first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

Coronavirus: EU Commission concludes exploratory talks with Valneva to secure a new potential vaccine

Today, the European Commission concluded exploratory talks with the pharmaceutical company Valneva with a view to purchasing its potential vaccine against COVID-19. The envisaged contract with Valneva would provide for the possibility for all EU Member States to purchase together 30 million doses, and they could further purchase up to 30 million more doses.
Today’s finalisation of exploratory talks with Valneva come in addition to an already secured broad portfolio of vaccines to be produced in Europe, including the contracts already signed with AstraZeneca, Sanofi-GSK, Janssen Pharmaceutica NV, BioNtech-Pfizer, CureVac, and Moderna and exploratory talks concluded with Novavax. This diversified vaccines portfolio will ensure Europe is well prepared for vaccination, once the vaccines have been proven to be safe and effective, as is already the case for BioNTech/Pfizer and Moderna, recently authorised in the EU. Member States are able to donate vaccines to lower and middle-income countries or to re-direct it to other European countries.
President of the European Commission, Ursula von der Leyen, said: “The continuing COVID-19 pandemic in Europe and around the globe makes it more important than ever that all Member States have access to the broadest possible portfolio of vaccines to help protect people in Europe and beyond. Today’s step toward reaching an agreement with Valneva further complements the EU’s vaccines portfolio and demonstrates the Commission’s commitment to find a lasting solution to the pandemic.”
Stella Kyriakides, Commissioner for Health and Food Safety, said: “With this eighth vaccine, we are adding to our already broad and diversified range of vaccines in our portfolio. By doing this, we can maximise our chances of making sure that all citizens can have access to safe and effective of vaccinations by the end of 2021. All Member States have now started their vaccination campaigns and will start receiving an increasing number of doses in order to cover all their needs during this year.”
Valneva is a European biotechnology company developing an inactivated virus vaccine. This is a traditional vaccine technology, used for 60-70 years, with established methods and a high level of safety. Most of the influenza vaccines and many childhood vaccines use this technology. This is currently the only inactivated vaccine candidate in clinical trials against COVID-19 in Europe.
The Commission, with the support of EU Member States, has taken a decision to support this vaccine based on a sound scientific assessment, the technology used, the company’s experience in vaccine development and its production capacity to supply all EU Member States.
Background
The European Commission presented on 17 June a European strategy to accelerate the development, manufacturing and deployment of effective and safe vaccines against COVID-19. In return for the right to buy a specified number of vaccine doses in a given timeframe, the Commission finances part of the upfront costs faced by vaccines producers in the form of Advance Purchase Agreements. Funding provided is considered as a down-payment on the vaccines that will actually be purchased by Member States.
Since the high cost and high failure rate make investing in a COVID-19 vaccine a high-risk decision for vaccine developers, these agreements will therefore allow investments to be made that otherwise might not happen.
Once vaccines have been proven to be safe and effective and have been granted market authorisation by the European Medicines Agency, they need to be quickly distributed and deployed across Europe. On 15 October, the Commission set out the key steps that Member States need to take to be fully prepared, which includes the development of national vaccination strategies. The Commission is putting in place a common reporting framework and a platform to monitor the effectiveness of national vaccine strategies and has adopted further actions  to reinforce preparedness and response measures across the EU and a strategy on staying safe from COVID-19 during winter offering further support to Member States in the deployment of vaccines.
The Commission is also committed to ensuring that everyone who needs a vaccine gets it, anywhere in the world and not only at home. No one will be safe until everyone is safe. This is why it has raised almost €16 billion since 4 May 2020 under the Coronavirus Global Response, the global action for universal access to tests, treatments and vaccines against coronavirus and for the global recovery and has confirmed its interest to participate in the COVAX Facility for equitable access to affordable COVID-19 vaccines everywhere. As part of a Team Europe effort, the Commission announced is contributing with €400 million in guarantees an additional €100 million in grant funding to support COVAX Facility and its objectives in the context of the Coronavirus Global Response. This €500 million from the EU budget combined with contributions from EU Member States and the EIB will be a key contribution for the COVAX Facility to ensure over one billion vaccine doses will be made available to people in low- and middle-income countries by the end of 2021.
Compliments of the European Commission.
The post Coronavirus: EU Commission concludes exploratory talks with Valneva to secure a new potential vaccine first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.

EACC

IMF | Denmark’s Ambitious Green Vision

Denmark aspires to become one of the most climate-friendly countries in the world. In June, its Parliament overwhelmingly passed a new climate law that aims to reduce greenhouse gas emissions by 70 percent below 1990 levels by 2030, with net zero emissions targeted for 2050.
This is an even more ambitious goal than the EU’s target to cut emissions by 55 percent over the same time period.

70%Amount by which Denmark plans to reduce greenhouse gas emissions by 2030 relative to 1990 levels

A new IMF staff paper takes a closer look at Denmark’s green strategy and proposes a few adjustments to help the country realize its ambitious goals. In line with earlier IMF recommendations, the paper proposes a comprehensive strategy with enhanced carbon pricing, reinforced by fiscal incentives across different sectors. It also urges using revenues from carbon pricing to cut labor taxes.
The package proposed in the paper would provide powerful incentives for climate mitigation, while shielding households and firms from higher energy prices. Crucially, the paper argues, spreading measures to different sectors is a good way to avoid carbon prices that are too high, capping them at half the level currently suggested by the Danish Council for Climate Change. The economic cost from this lower carbon price would be fairly low—estimated at about 0.2 percent of GDP.
“Feebates”—fees on products with high emissions combined with rebates on products with low emissions—are recommended for sectors with high emissions. They could be especially useful to curb Denmark’s large agricultural emissions from the country’s huge number of farmed animals. Because feebates raise the costs of producers who farm unsustainably but reward them as they shift to sustainable farming, this program can deliver a fair low-carbon transition that preserves profitability and jobs.
By crafting an effective climate policy that protects the majority of people, Denmark’s strategy to make large cuts in its emissions could be more attainable.
Compliments of the IMF.
The post IMF | Denmark’s Ambitious Green Vision first appeared on European American Chamber of Commerce New York [EACCNY] | Your Partner for Transatlantic Business Resources.